



Massage Chair Market: Why the 6.98% CAGR Trajectory Signals More Than Just Growth

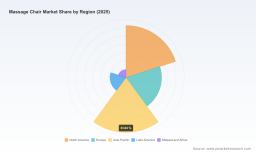
The Massage Chair Market: Strategic Trends and Commercial Opportunities
The global massage chair market has transitioned from a niche wellness accessory to a strategically significant segment within the broader health and home comfort ecosystem. Over a five-year historical window, the market demonstrated steady expansion, with annual revenue growing from approximately $163.15 million in 2020 to an estimated $215.0 million in 2025. Looking ahead to the forecast horizon ending in 2032, the sector is projected to reach $344.8 million, reflecting a compound annual growth rate of 6.98 percent. This trajectory signals more than incremental demand growth; it indicates a structural shift in how households, wellness providers, and commercial operators view massage chairs as integrated health infrastructure rather than discretionary furniture.
For executives and strategic planners, the numbers alone do not capture the full story. The market’s evolution is being shaped by converging forces: advanced robotics, AI-driven personalization, shifting consumer health behaviors, and a regulatory and cost environment that rewards speed to market and engineering differentiation. Understanding where the market is heading requires looking beyond headline revenue figures and examining the underlying dynamics that will determine which companies capture margin, which regions scale fastest, and which product categories become commoditized.
Market Landscape and Core Challenges
The market’s current footprint reflects a maturing but still rapidly evolving category. Revenue growth has accelerated as consumer acceptance broadens and product sophistication improves, with the 2025 estimate of $215.0 million serving as a clear inflection point. The forecast period through 2032 projects continued expansion toward $344.8 million, but the pace and composition of that growth will be uneven across segments and geographies. The category is no longer defined solely by basic mechanical rollers and basic air pressure systems; it is increasingly shaped by intelligent tracking, adaptive pressure mapping, and wellness-program integration that blur the line between consumer electronics and therapeutic devices.
Despite the favorable growth outlook, the industry faces several structural challenges that will test competitive positioning in the coming years.
First, the market is navigating a technology inflection point where differentiation is becoming harder to sustain. Early robotic and AI-integrated features created meaningful premium pricing power, but as core sensing, motor control, and body-mapping technologies mature, the risk of feature parity increases. Companies that rely on incremental additions without underlying engineering depth will face margin compression as buyers increasingly compare specifications and total cost of ownership rather than brand narrative alone.
Second, the regulatory and safety environment is adding complexity to product design and market entry. In North America, massage chairs must comply with Consumer Product Safety Commission standards and Federal Trade Commission advertising guidelines for electrical products. These requirements are not static; they evolve as product functionalities become more interactive and health-adjacent. Compliance is not merely a legal checkbox but a design constraint that influences component selection, user interface architecture, and claims language. Companies with mature quality systems and proactive regulatory engagement will have an advantage in scaling across channels without facing costly redesigns or marketing restrictions.
Third, cost structures and trade dynamics are reshaping margin calculations. Import controls and tariff environments have introduced uncertainty around sourcing strategies, particularly for Chinese-origin units. Sector analysis indicates that tariffs in the 15 to 20 percent range on certain Chinese-origin massage chairs have resulted in limited consumer price increases, largely because manufacturers and distributors have adapted supply chains through sourcing shifts, regional assembly, and value engineering. This suggests that tariff exposure is manageable but requires active supply chain design rather than passive pass-through. At the same time, labor and engineering costs in premium manufacturing markets influence pricing architecture, with Japanese manufacturers sustaining premium positioning through advanced engineering and patent portfolios in high-margin wellness models.
For decision makers, these challenges point to a clear conclusion: the market rewards companies that treat compliance, supply chain flexibility, and engineering depth as strategic inputs rather than operational afterthoughts.
Key Drivers of Market Change
Several interconnected drivers are accelerating the market’s evolution and creating distinct opportunities for operators that can align product strategy with emerging demand patterns.
Technological innovation remains the most visible and impactful driver. The category is moving from fixed-program massage routines toward adaptive systems that interpret user posture, tension patterns, and preferred intensity in real time. Body-scan programs, AI health detection, and multi-dimensional roller mechanisms are becoming central to premium offerings. Recent product unveilings illustrate this shift in practice. At CES 2026, Body Friend Co., Ltd. introduced the 733 massage chair and the Pharaoh Q AI massage chair, emphasizing advanced AI health solutions and robotic massage technology. Around the same period, Human Touch showcased the Novo XT and Super Novo X, highlighting whole-body massage innovations and teardrop doors designed to improve accessibility and user experience. KoziSense also presented a latest 4D massage chair lineup at CES 2026, including ergonomic high-end models with intelligent massage technology. These launches reflect a broader industry direction: the value proposition is shifting from mechanical repetition to personalized, context-aware wellness intervention.
Policy and regulatory dynamics are shaping both market access and consumer trust. Safety and advertising compliance influence how products are positioned, especially when marketing language approaches health or therapeutic claims. In parallel, reimbursement-adjacent mechanisms are expanding the practical affordability of select models. Certain Human Touch and OSIM models are eligible under HSA/FSA frameworks, allowing tax-advantaged wellness purchases that can lower effective consumer cost and broaden the addressable market. This does not transform massage chairs into insured medical devices, but it does create a purchasing pathway that can accelerate adoption among health-conscious households and corporate wellness programs that already use flexible spending accounts.
Demand-side behavior is changing as consumers increasingly view wellness expenditure as preventive and habitual rather than occasional. Residential use remains a dominant application context, but commercial deployment is also gaining relevance in settings such as hotels, spas, clinics, and corporate relaxation spaces. The commercial segment benefits from recurring visibility and shared-use economics, but it also demands durability, hygiene considerations, and serviceability that differ from residential expectations. This divergence is encouraging manufacturers to think in terms of product families rather than single SKUs, with variations in robustness, interface complexity, and service support tailored to each use case. Osaki’s recent exhibition activity reinforces this commercial-residential balance: at the Las Vegas Furniture Market 2026, the company exhibited premium models including the Platinum Escape Duo 4D and OS-Pro 4D+3D, signaling continued attention to both high-end home formats and commercial-adjacent placement opportunities.
Supply chain and cost-structure changes are redistributing where value is created. As demand grows, manufacturers are under pressure to balance engineering ambition with manufacturability, component availability, and logistics resilience. The ability to localize certain assembly steps, diversify component sourcing, and manage warranty and service costs is becoming a competitive lever in its own right. Industry market data projects North American premium segment growth at 5 to 7 percent CAGR driven by AI-integrated wellness features, suggesting that premiumization is not merely a pricing strategy but a demand-led trend that rewards products capable of delivering perceptible differentiation in user experience and health-adjacent functionality.
Together, these drivers indicate that the market’s next phase will favor companies that integrate technology, compliance, distribution, and consumer financing into a coherent value proposition rather than optimizing each in isolation.
Competitive Landscape and Leading Strategies
The competitive field is concentrated but diverse, with leading players occupying distinct strategic positions based on engineering heritage, patent portfolios, regional origin, and targeted use cases. Market concentration data indicates that the top three firms account for roughly 48.5 percent of revenue, while the top five reach approximately 57.8 percent. This level of concentration suggests a market where scale, brand trust, and product portfolios matter, but where specialized differentiation can still support strong niche positioning.
Lift Chair Market
Human Touch, headquartered in Long Beach, California, competes with a focus on state-of-the-art robotic massage chairs, zero-gravity recliners, and wellness solutions built around patented technologies such as CirQlation and HT Flex. Its strategic positioning leans toward accessible premium wellness, with product design that emphasizes circulation-focused mechanisms and user-friendly recliner formats. The company’s HSA/FSA-eligible models also indicate an understanding of financing pathways as part of the purchase decision.
Osaki, based in Japan, positions itself around premium 4D and 5D full-body massage chairs with AI health detection, SL Flex track mechanisms, and automated body-scan programs. Its strength lies in combining advanced track geometry with intelligent sensing, appealing to buyers who want a more data-informed and adaptive massage experience. Osaki’s recent Las Vegas Furniture Market 2026 presence, including the Platinum Escape Duo 4D and OS-Pro 4D+3D, underscores its commitment to maintaining visibility in both premium home and commercial-adjacent channels.
OSIM, headquartered in Singapore, competes with full-body shiatsu and zero-gravity massage chairs supported by 250 or more patented technologies, including V-Hand™ and Tui-Na gliding, and endorsements such as recognition by the American Chiropractic Association. This profile suggests a strategy rooted in clinical-adjacent credibility and broad patent coverage, which can support both consumer trust and retailer confidence in product claims.
Body Friend Co., Ltd., based in South Korea, offers 4D full-body massage chairs with patented walking-leg technology, zero-gravity design, heat, airbags, and foot rollers. Its CES 2026 reveals, including the 733 and Pharaoh Q AI models, highlight a focus on combining mechanical innovation with AI health solutions, reinforcing a forward-looking product roadmap.
FAMILY INADA, located in Osaka, Japan, competes in high-performance shiatsu massage chairs and is recognized for originating the first automatic shiatsu chair along with specialized wellness therapy solutions. Its positioning reflects heritage and specialization in shiatsu-style mechanics, which can appeal to buyers seeking authentic technique differentiation rather than generalized relaxation features.
Ceragem, also based in South Korea, focuses on luxury zero-gravity massage chairs with SPINE-Tech™ spinal therapy, Pro Dual Engine, and custom automatic modes. Its strategy centers on spinal-focused therapy claims and premium build, targeting consumers who prioritize targeted spinal support and high-end comfort in a single platform.
Ogawa, headquartered in Switzerland, competes with luxury massage chairs and zero-gravity recliners that emphasize advanced wellness features for both home and professional use. Its Swiss positioning supports a premium perception and broad use-case framing, which can be advantageous in markets where design credibility and cross-context versatility matter.
PW Consulting
The strategic patterns emerging across these players are instructive. Some compete on patent depth and clinical-adjacent credibility; others on AI-driven adaptability and ergonomic innovation; still others on premium design and use-case flexibility. What separates the leaders is not a single feature but the ability to connect engineering, brand trust, channel strategy, and financing accessibility into a coherent offering. Recent trade show activity in early 2026 demonstrates that product messaging is increasingly tied to intelligent personalization, accessibility improvements, and multi-dimensional massage quality, rather than simple roller count or basic air compression.
Looking at the broader market evolution, three dynamics are likely to shape competitive outcomes. First, consolidation pressure may increase as larger players seek to broaden portfolios through acquisition or expanded distribution, particularly in regions where retail trust and service networks are decisive. Second, segmentation will likely deepen, with clearer separation between mass-premium comfort products and high-end AI-integrated wellness systems, each requiring distinct supply chain, marketing, and service models. Third, new entrants may find opportunity not by competing head-to-head in established premium segments, but by targeting underserved use cases, regional price points, or hybrid commercial-residential designs that better match specific buyer economics.
Forward Outlook: Trends and Opportunities
Based on current data and industry dynamics, three trends are likely to define the market over the next three to five years.
The first trend is the continued premiumization of AI-integrated wellness features. As body mapping, adaptive pressure control, and health-oriented user interfaces become more refined, premium products will increasingly serve as platforms for personalized wellness routines rather than static massage devices. This creates opportunity for manufacturers that can translate sensor and software capabilities into measurable user benefits, and for retailers that can communicate those benefits without overstating therapeutic claims. The risk is that feature complexity outpaces reliability or usability, leading to buyer fatigue if intelligent features are perceived as gimmicks rather than meaningful improvements.
The second trend is the expansion of commercial and semi-commercial deployment models. Hotels, wellness centers, corporate facilities, and medical-adjacent environments are likely to increase adoption where durability, serviceability, and shared-use ergonomics can be proven. This opens opportunities for products designed with higher cycle durability, easier maintenance, and hygiene-oriented materials, as well as for service partners who can support installation and ongoing maintenance at scale. The uncertainty lies in standardization: commercial buyers will demand consistent performance and clear total cost of ownership data, which may pressure manufacturers to provide more transparent service and warranty economics.
The third trend is supply chain and pricing adaptation in response to trade and cost pressures. As tariff environments and component costs continue to vary by origin and configuration, successful players will likely diversify sourcing, consider regional assembly or finishing options, and engineer product architectures that allow modular cost management without degrading perceived quality. This creates opportunity for companies that can maintain premium positioning while managing landed cost strategically. The risk is that aggressive cost reduction erodes the engineering and safety attributes that justify premium pricing in the first place.
Across all three trends, the commercial opportunity is clearest for organizations that can align product innovation with channel readiness, compliance discipline, and clear communication of user value. Markets that treat these as integrated choices are more likely to convert growth into durable margin than those that chase features or price points in isolation.
Luxury Massage Chair Market
Implications for Decision Makers
For manufacturers, the priority is to build differentiation that is difficult to replicate through specification matching alone. That means investing in track geometry, sensing accuracy, user interface clarity, and reliability data that support premium positioning, while ensuring compliance and claims language are aligned with actual product capabilities. Product roadmaps should also anticipate commercial and residential divergence, with distinct durability, service, and hygiene considerations where relevant. Speed to market matters, but not at the expense of safety and consistency; in a category where CPSC and FTC expectations shape both design and marketing, disciplined launch processes can be a competitive advantage.
For investors, the market offers growth but requires selective exposure. The most resilient opportunities are likely in companies with defensible engineering or patent assets, clear premium-segment traction, and flexible supply chain strategies that can absorb trade and cost variability. Interest in AI-integrated wellness features is real, but returns will depend on whether those features translate into repeat purchase, stronger brand trust, and improved channel economics rather than short-lived novelty. Monitoring product launches, trade show presence, and compliance-related messaging can provide early signals about which players are building durable positions versus those relying on promotional momentum.
For procurement and channel buyers, the focus should be on total value rather than sticker price alone. Evaluation criteria should include body-scan accuracy, adaptive pressure control, durability in intended use settings, serviceability, warranty structure, and financing eligibility where applicable. For commercial deployments, additional weight should be given to hygiene, maintenance access, and expected service cycles. Given the pace of product iteration and the variability in claims and specifications across the category, access to current, granular market intelligence can materially improve sourcing and assortment decisions.
The market is moving quickly enough that static assumptions about features, pricing, and regional opportunity can become outdated within a product cycle. Detailed segmentation data, track-level competitive benchmarking, and scenario-based cost and demand analysis can help decision makers separate durable trends from temporary noise. For those evaluating market entry, portfolio expansion, or sourcing strategy, deeper research provides the granularity needed to calibrate investment and reduce exposure to misaligned assumptions. A complete research report offers expanded segmentation detail, company-level profiling, and customizable scenario analysis for organizations that need to move from strategic direction to operational planning.
For detailed analysis of this topic, please visit the official page: Massage Chair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


