



Advanced CO2 Sensors Market: Why 7.1% CAGR and $1.1B Scale Change Everything

Advanced CO2 Sensors: Navigating Convergence, Compliance, and Commercial Opportunity
The advanced CO2 sensor market occupies a pivotal position where environmental regulation, building decarbonization, and precision measurement intersect. Market estimates point to a total revenue trajectory moving from approximately $690.0 million in 2025 toward $1,115.26 million by 2032, reflecting a compound annual growth rate of 7.1% across the forecast horizon. This expansion is not purely incremental; it is being reshaped by compliance mandates that elevate measurement accuracy from a desirable feature to a mandatory requirement, by product architectures that compress form factors while preserving performance, and by a supply environment where miniaturization and power efficiency dictate competitive differentiation. The sector’s structure remains moderately concentrated, with the top three players capturing roughly 55% of revenue and the top five accounting for about 68%, yet the composition of leadership continues to shift as incumbents navigate product roadmaps, regulatory alignment, and downstream integration with building management systems.
For decision-makers, the core question is no longer whether CO2 sensing will grow, but how the convergence of standards, product form factors, and application-specific performance requirements will reshape value capture across the value chain. The following analysis examines the current market backdrop, the forces propelling change, the competitive logic among leading suppliers, and the strategic implications for manufacturers, investors, and procurement organizations.
Market Snapshot and Structural Pressure Points
The market has matured through a period of steady expansion, driven by broader adoption of indoor air quality monitoring, demand-controlled ventilation in commercial buildings, and industrial process control. The current revenue base is anchored by established end-use demand, but the rhythm of growth is increasingly governed by regulatory cycles and product upgrades rather than by first-time deployments alone. The market’s growth curve suggests that incremental volume gains will be supplemented by higher-value deployments where accuracy, calibration stability, and integration readiness become the primary purchasing criteria.
Challenge 1: Compliance Becomes a Product Requirement, Not a Feature
A defining shift in the market is the elevation of measurement accuracy and repeatability to the center of procurement specifications. Standards such as ANSI/ASHRAE 62.1-2022 Addendum d place precise CO2 measurement at the heart of demand-controlled ventilation performance, aligning sensor capability directly with energy-efficiency objectives. In Europe, the Energy Performance of Buildings Directive sets zero-emission expectations for new buildings by 2030, reinforcing the link between ventilation control, air quality, and compliance documentation. As these requirements cascade into procurement specifications, sensor suppliers must demonstrate not only functionality but verifiable alignment with building standards, including IAQ frameworks such as RESET Grade B and WELL Building Standard v2 in relevant deployments.
The implication is structural: compliance becomes a gatekeeper for market access in higher-value segments. Sensors that cannot meet accuracy thresholds, calibration expectations, or documentation rigor face increasing friction in specification-driven purchasing processes. This elevates the importance of product validation, test data, and support materials that translate technical performance into compliance readiness.
PW Consulting Information & Electronics Research Center
Challenge 2: Miniaturization, Power, and Integration Are Redefining Winning Form Factors
The market is moving toward smaller, lower-power devices that can be embedded across HVAC controls, smart building nodes, and battery-operated IoT installations. This trend pressures suppliers to balance size reduction with accuracy and environmental robustness. Product roadmaps increasingly emphasize solderability, compact packaging, and low power draw, especially where continuous monitoring must fit within constrained energy budgets or tight mechanical envelopes. In parallel, integration with building management platforms and environmental sensing ecosystems is becoming a differentiator, because end users favor solutions that reduce installation complexity and streamline commissioning.
This miniaturization-and-integration trajectory creates a double-edged challenge. It opens room for higher unit volumes in distributed monitoring, yet it also compresses margins if products compete primarily on size alone. The winners are likely to be those that combine small footprints with validated performance and integration support, not just packaging efficiency.
Challenge 3: Concentrated Leadership Meets Application-Specific Competition
Market share concentration indicates that a limited group of suppliers holds substantial influence over product direction and customer relationships. At the same time, application requirements differ enough that leadership in one segment does not automatically translate into leadership across all segments. Accuracy-intensive building and healthcare deployments may favor different characteristics than industrial process monitoring or automotive-adjacent applications. As a result, competitive positioning is becoming more application-aware, with suppliers emphasizing specific feature sets, compliance alignment, and platform integration instead of competing broadly on sensor category alone.
This dynamic creates room for targeted differentiation, but it also raises the stakes for portfolio coherence. Suppliers must manage trade-offs between breadth and depth, ensuring that product lines are credible in the segments they choose to serve, with the documentation and support to match.
Core Drivers Reshaping Demand and Product Strategy
Technological Innovation: Smaller Sensors with Higher Accuracy and Lower Power
Product launches in recent periods illustrate how technology roadmaps are converging around accuracy, size, and energy efficiency. One example is the introduction of ultra-compact NDIR CO2 sensors designed for demand-controlled ventilation and surface-mount integration, with a substantially smaller footprint than previous generations and compliance positioning aligned with ASHRAE 62.1-2022 Addendum d. Mass production timing and sample distribution activity indicate that these designs are moving from demonstration to deployment readiness, with relevance for smart buildings, IAQ monitoring, and compact environmental sensing. Another example is a photoacoustic NDIR CO2 sensor positioned as a drop-in upgrade pathway for an existing platform, with best-in-class accuracy and building-standard alignment. Together, these developments reflect an industry trend in which accuracy improvements are being packaged into more compact, easier-to-integrate modules.
Air Quality Sensor Market
For manufacturers, this trend changes the equation between performance and form factor. Historically, users may have accepted trade-offs between size or power and measurement precision. The current direction suggests that multiple product tiers can deliver high accuracy within compact formats, which expands the addressable design space for OEMs and system integrators.
Policy and Regulatory Environment: Standards as Adoption Accelerators
Regulatory and standards-based pressure is one of the strongest demand accelerators in the market. The shift toward more rigorous ventilation control requirements is effectively converting CO2 measurement from an optional monitoring parameter into a compliance-critical input for energy-efficient building operation. In both North America and Europe, building codes and directives are reinforcing expectations for precise environmental sensing and low-emission building performance. This does not merely increase total demand; it changes the composition of demand toward applications where specification, validation, and documentation matter more than price alone.
This regulatory overlay has strategic consequences. Suppliers with products already positioned for relevant standards can benefit from shorter specification cycles and faster customer confidence. Conversely, suppliers without clear alignment may face more intensive evaluation, particularly in projects where building certification, energy performance, or IAQ documentation is part of the procurement scope.
Demand-Side Shifts: Building Operators, Healthcare, and Industrial Users Are Prioritizing Air Quality and Efficiency Together
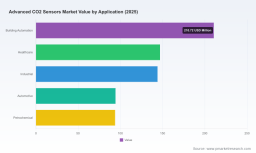
Demand is increasingly driven by an overlap of operational objectives rather than by a single use case. Building operators are linking indoor air quality with energy optimization, making demand-controlled ventilation and continuous monitoring more attractive where both occupant comfort and compliance are in play. Healthcare environments continue to place a premium on environmental monitoring, where measurement stability and reliability can influence operational confidence. Industrial users remain focused on process control and safety-adjacent sensing, but with growing interest in compact, low-power devices that can be integrated into broader monitoring architectures.
This demand evolution is notable because it tilts purchasing behavior toward total solution value. Buyers are less likely to evaluate sensors in isolation and more likely to consider how a device fits into commissioning, calibration, maintenance, and system-level reporting. The practical implication is that sensor products compete not only on measurement performance, but also on how easily they support operational workflows.
Supply-Side and Cost Structure Dynamics: Integration and Miniaturization Influence Margin Logic
The supply environment is being shaped by the same miniaturization and integration pressures that influence product design. Smaller sensors with SMD compatibility, low-power operation, and multi-function environmental sensing capabilities can enable broader deployment, but they also invite closer scrutiny of production efficiency, calibration processes, and support economics. Where volume grows through distributed installations, cost-to-serve and after-sales support become increasingly relevant to profitability.
At the same time, suppliers that can combine compact hardware with strong compliance documentation and integration support may be able to defend pricing better than those competing primarily on unit cost. In this sense, supply-side advantage is shifting from scale alone toward the ability to deliver validated, easily deployable solutions at scale.
Competitive Landscape and Where Leadership Is Being Built
The competitive field includes a mix of specialized sensor developers and broader industrial or building-technology players. Senseair, based in Sweden, is associated with ultra-compact NDIR CO2 sensors for demand-controlled ventilation and smart building integration, with recent activity emphasizing smaller form factors, SMD solderability, and compliance alignment for IAQ monitoring and DCV systems. Sensirion AG, based in Switzerland, is notable for photoacoustic NDIR CO2 sensors positioned around high accuracy and building-standard compliance, with a product trajectory that includes drop-in upgrade capability for an existing platform. Gas Sensing Solutions, based in the UK, has focused on solid-state NDIR CO2 sensors optimized for ultra-low-power IoT and battery-powered applications, with integrated environmental sensing functionality. Vaisala Oyj, based in Finland, is linked to advanced NDIR CO2 sensors using optical technology for precision applications in building management, industrial settings, and data-center-related monitoring.
Larger ecosystem players also play distinct roles. Amphenol Advanced Sensors, based in the USA, supplies compact, low-power CO2 sensors with emphasis on miniaturization and high accuracy across HVAC, IoT, and environmental monitoring. Siemens AG, based in Germany, integrates NDIR CO2 sensor modules into building management systems with portfolios directed at HVAC and air quality control. Honeywell International Inc., based in the USA, offers chemical and infrared CO2 sensors for safety, IAQ, and industrial applications, including low-power draw options.
Strategic Positioning and Differentiation
Differentiation in this market is increasingly multidimensional. Some suppliers compete primarily on accuracy and measurement physics, especially where standards compliance and repeatability are critical. Others emphasize form factor, power consumption, and ease of integration, particularly for IoT and battery-limited deployments. A third group focuses on system-level integration, where sensor modules are embedded within broader building management or environmental monitoring platforms. These paths are not mutually exclusive, but they shape how each supplier is likely to win in specific segments.
Worldwide Carbon Dioxide Detector Market
A notable pattern is the alignment between product releases and compliance targets. Where new sensors are introduced with explicit positioning against ventilation standards, IAQ frameworks, and building certification requirements, they are effectively reducing the evaluation burden for specification-driven buyers. This suggests that regulatory alignment is becoming a competitive asset, not just a technical specification.
Evolution of the Market Structure
The market structure appears to be moving along two parallel tracks. One is consolidation of leadership among established players that can combine technical credibility, standards alignment, and broad application reach. The other is continued differentiation in niche requirements, where low-power IoT sensing, compact SMD integration, or application-specific robustness create space for focused competition. New entrants and platform players are likely to test the market where installation simplicity, integration readiness, or compliance documentation provide a distinct advantage.
Over time, this points to a landscape in which broad market share remains important, but segment relevance and solution readiness become more decisive. Suppliers that can bridge the gap between a sensor component and a spec-ready, integration-friendly solution are better positioned to capture value as procurement processes become more standards-driven and application-specific.
Forward View: Three Trends Shaping the Next Three to Five Years
Trend 1: Compliance-Linked Specifications Will Drive More Discriminating Purchasing
As building codes, ventilation standards, and IAQ frameworks continue to tighten, procurement will likely place greater weight on verifiable performance and compliance alignment. This should shift demand toward sensors that can demonstrate accuracy, calibration stability, and documentation suitable for specification and certification requirements. The commercial opportunity lies in products and support packages that reduce the friction of evaluation, commissioning, and ongoing compliance evidence. The risk is that suppliers with products not clearly aligned to evolving standards may face slower adoption in higher-value deployments, even if unit costs are attractive.
Trend 2: Compact, Low-Power, Integrated Sensing Will Expand Deployment Surface Area
Continued miniaturization and lower power draw should enable wider dispersal of sensing into smart buildings, distributed HVAC controls, and battery-operated monitoring nodes. This trend expands the potential installation base and encourages integration with broader environmental sensing and building management platforms. The commercial opportunity is in designs that make continuous monitoring practical at scale, especially where installation constraints or energy budgets have historically limited coverage. A key uncertainty is whether competition on size and power will intensify to the point of compressing differentiation, unless suppliers can pair compact designs with strong accuracy and integration support.
Trend 3: Platform Integration and Ecosystem Positioning Will Matter as Much as Sensor Performance
As end users increasingly seek streamlined commissioning and system-level reporting, the value of a sensor will be shaped not only by its measurement capability but also by how well it fits into building management, HVAC control, or IoT platforms. Suppliers that offer modules, integration guidance, and compatibility with common system architectures can strengthen their position beyond the component level. The commercial opportunity lies in becoming easier to specify and easier to deploy. The risk is that fragmented compatibility or weak integration support can slow adoption even when sensor performance is competitive.
Strategic Implications for Decision-Makers
For Manufacturers and Product Leaders
Product roadmaps should be evaluated against the standards and deployment realities that are shaping purchasing decisions, not just against sensor category benchmarks. Where accuracy, compliance alignment, and compact integration are increasingly decisive, investment in validation, documentation, and integration support can be as important as hardware development. At the same time, product differentiation should be anchored in clearly defined application value, because broad claims compete less effectively than segment-specific strengths in a market where specification-driven purchasing is gaining ground.
For Investors and Strategic Allocators
The market’s growth trajectory is supported by regulation-led demand and product innovation, but returns will likely depend on which suppliers can combine credible accuracy with scalable deployment and standards alignment. Attention should be given to companies that are moving products from sample activity into mass production with clear compliance positioning, as well as to those with integration-rich portfolios that reduce customer friction. Concentration in the market also suggests that competitive advantage may be unevenly distributed across applications, so segment-level adoption and support economics deserve careful scrutiny.
For Procurement and Operations Leaders
Specifying CO2 sensing increasingly means specifying compliance readiness, integration fit, and operational support, not just a measurement device. Evaluation processes should account for accuracy claims, calibration stability, commissioning requirements, and compatibility with existing building or monitoring platforms. A sensor that is marginally cheaper upfront may carry higher total cost if it complicates documentation, installation, or ongoing verification. In practice, procurement decisions will be stronger when sensor selection is treated as part of a broader air quality and ventilation control strategy.
Closing Perspective
The advanced CO2 sensor market is entering a phase in which growth is increasingly shaped by the interaction of standards, product form factors, and solution readiness. The revenue path toward the 2032 horizon reflects more than incremental adoption; it reflects a shift in how sensing is specified, integrated, and valued across buildings, healthcare, industrial, and related applications. In that environment, the most consequential questions are not only about measurement capability, but about whether a sensor can be validated for compliance, deployed efficiently, and supported within the operational workflows that customers actually use.
For organizations seeking to move from market awareness to precise segment-level planning, the additional detail in the full research report can help narrow priorities around end-use demand, regional variation, product category splits, and competitive positioning. Detailed segmentation data and customized scenario analysis are available for teams that need to translate these trends into actionable procurement, product, or investment decisions.
For detailed analysis of this topic, please visit the official page: Advanced CO2 Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


