



Prefab Bathroom Pods Market: Why 9.4% CAGR and Commercial Demand Change Everything

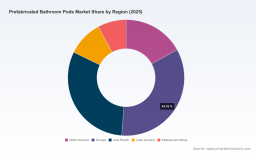
The Prefabricated Bathroom Pods Market: Strategic Shifts and Commercial Opportunities Through 2032
The prefabricated bathroom pods market has moved from a niche construction alternative to a mainstream operational lever for developers, contractors, and facility operators. Valued at approximately USD 6.7 billion in 2025 and projected to expand at a compound annual growth rate of 9.4% through 2032, reaching a revenue base near USD 12.59 billion by the end of the forecast period, the sector reflects a structural recalibration of how built-environment programs are delivered. The trajectory from 2020 through 2025 alone—moving from 4.32 billion to 6.7 billion—demonstrates that the shift is not cyclical but cumulative, driven by persistent labor constraints, schedule compression, and the maturation of offsite manufacturing capabilities.
For decision-makers, this market now sits at an inflection point where technology, regulation, and procurement behavior are reinforcing one another. The opportunity is no longer simply about buying a prefabricated unit; it is about integrating factory-built bathrooms into broader project delivery models, managing supply chain dependencies, and aligning product specifications with evolving compliance and sustainability expectations. The following analysis maps the current state of the market, the forces reshaping it, the competitive positioning of leading manufacturers, and the strategic implications for executives navigating the next three to five years.
Market Status and Core Challenges
The scale of the prefabricated bathroom pods market signals broad adoption, but scale alone does not guarantee smooth execution. The market's growth path from 2020 to 2025—expanding from 4.32 billion to 6.7 billion—has been supported by repeatable factory processes, standardized connection systems, and a growing pipeline of residential, commercial, and institutional projects that prioritize speed and predictability. The forecast band from 2026 through 2032, moving toward 12.59 billion, suggests continued deployment across multiple building types, with commercial and institutional programs likely to remain the primary volume drivers while residential applications gain share as production costs stabilize and design libraries mature.
Despite the positive revenue curve, three challenges define the current operating environment and will shape who captures value in the next phase of growth.
1. Quality Standardization Versus Design Flexibility
Factory production favors repetition, yet end-user expectations increasingly demand customized finishes, layouts, and accessibility configurations. The tension between manufacturing efficiency and project-specific variation is intensifying as pods move from standardized hotel rooms and student housing into healthcare environments, defense facilities, and higher-spec residential programs. Manufacturers that can modularize variation—through configurable framing, interchangeable finish panels, and digital specification workflows—gain a meaningful advantage, while those locked into rigid product lines face margin pressure or limited addressable demand.
2. Compliance Complexity Across Jurisdictions
Prefabricated bathroom pods must satisfy a layered set of requirements that vary by region and building type. International Building Code (IBC) and IRC provisions, local plumbing regulations, and fire-retardant packaging standards such as Loss Prevention Standards LPS 1207 create a compliance landscape that can slow deployment if not addressed upstream. The practical implication is that factory readiness does not automatically translate into site readiness; manufacturers and buyers need aligned inspection pathways, documentation protocols, and transport safeguards to avoid rework or delays during final on-site approval.
3. Supply Chain Concentration and Material Volatility
The market remains moderately concentrated, with leading manufacturers holding a meaningful share of capacity and project flow. Concentration can improve quality consistency and scale economies, but it also raises dependency risks when raw material availability, freight constraints, or production bottlenecks emerge. Steel, composite materials, and lightweight concrete inputs each carry distinct cost and performance profiles, and shifts in one material stream can ripple through lead times and pricing. Buyers and competitors alike are increasingly evaluating dual-sourcing strategies, regional production footprints, and buffer inventory approaches to reduce exposure.
Key Drivers Shaping Market Evolution
Market expansion is not accidental; it is being pulled by a convergence of technical, regulatory, demand-side, and cost-driven forces. The most consequential drivers are not isolated trends but interacting dynamics that change how projects are planned, priced, and delivered.
Technological Innovation and Manufacturing Maturation
Factory-built bathroom pods are benefiting from more disciplined production environments, digital design integration, and material optimization. Advanced composite and steel-frame production lines, BIM-aligned specification workflows, and lean manufacturing practices are reducing defect rates, improving dimensional accuracy, and shortening assembly sequences. Lightweight concrete and patented galvanized steel frame solutions have expanded the structural envelope available for multi-story and higher-load applications, while GRP-based pods are increasingly preferred for their corrosion resistance, reduced maintenance burden, and ease of handling. These material and process improvements are not merely incremental; they broaden the range of projects where pods can be deployed without compromising performance or schedule.
Recent product activity reinforces this trajectory. In February 2026, Offsite Solutions introduced a next-generation steel-framed bathroom pod line with modular design elements that allow customization of layouts and finishes while preserving manufacturing efficiency. That kind of development matters because it addresses a core market tension: buyers want flexibility, but manufacturers need repeatable throughput. Solutions that standardize the underlying frame and connection system while enabling finish and layout variation create a more scalable value proposition.
Policy and Regulatory Environment
Regulatory expectations are becoming both a constraint and a differentiator. Manufacturers are increasingly designing pods to align with local building codes, plumbing regulations, and inspection pathways so that units arrive at the site with a higher degree of factory readiness. At the same time, loss prevention and transport standards are shaping packaging, storage, and handling requirements, particularly for temporary coverings and protective materials used during movement and staging. Compliance is no longer a back-office concern; it is a commercial specification. Projects that integrate code alignment, documentation, and transport safeguards earlier in the procurement cycle reduce the likelihood of delayed approvals or on-site corrections.
This regulatory pull is most visible in programs where inspection risk is high or where multiple jurisdictions are involved. In those settings, manufacturers with established compliance frameworks and predictable quality control processes can shorten decision cycles and lower project risk. The broader effect is a market in which credibility around code conformance and inspection readiness becomes part of the product itself.
Demand-Side Behavior and Procurement Priorities
Buyers are increasingly treating bathrooms as a delivery bottleneck rather than a downstream trade. Onsite bathroom assembly can consume disproportionate labor, extend schedule risk, and create coordination challenges across plumbing, finishes, and inspections. Prefabricated pods accelerate project timelines by roughly 40-50% and reduce on-site workforce needs compared with traditional construction methods, which makes them attractive in labor-constrained markets and in programs where speed-to-occupancy is a financial priority.
Demand is also shifting in response to program type. Commercial and institutional projects—hotels, student accommodation, healthcare facilities, and social housing—continue to be strong adopters because they value repeatable units, predictable quality, and faster fit-out. At the same time, residential applications are gaining momentum as developers and contractors look for ways to compress schedules and control finish quality. The result is a broadening demand base that rewards manufacturers capable of serving multiple sectors without sacrificing production discipline.
Worldwide Bathroom Product Market
Cost Structure and Labor Dynamics
Labor availability and cost remain a structural driver. Where skilled trades are scarce or wage pressure is high, offsite production offers a practical route to reduce on-site labor intensity and improve schedule certainty. Factory settings also enable better material yield, more controlled quality checks, and fewer Weather-related delays, all of which contribute to a more predictable cost profile. This does not mean prefabrication eliminates cost risk; transportation, staging, crane logistics, and interface coordination with the primary structure still matter. But the cost conversation is moving from unit price alone toward total program efficiency, including time savings, rework reduction, and workforce allocation.
Project activity in 2026 illustrates how demand and delivery models are converging. In March 2026, BAUDET secured contracts for multiple hotel modernizations and student residence projects, including Kyriad Hotels Modernization for Louvre Hotels Group in Paris, along with student residence projects in Saint-Étienne and Caen. These wins point to a repeatable commercial pattern: modernization programs and high-volume residential/hospitality pipelines where consistent finishes, predictable lead times, and reduced on-site disruption are decisive. Later, in April 2026, Southwest Solutions Group participated in modular construction and restroom solutions events showcasing code-compliant prefabricated bathroom pods for fast deployment, reflecting a wider industry emphasis on compliance-ready, rapidly deployable units.
Competitive Landscape and Leading Strategies
The competitive environment is defined by manufacturers that have built reputation around production scale, material specialization, and sector focus. The market's concentration suggests that established players hold substantial influence over pricing, specification norms, and buyer confidence, but it also leaves room for regional specialists and new entrants that can differentiate through customization, compliance readiness, or logistics advantage.
Several strategic positions are emerging among leading companies. Walker Modular, based in Hull, United Kingdom, operates as a leading manufacturer of high-quality prefabricated bathroom pods with advanced composite and steel frame production lines, serving UK developers, hotels, healthcare facilities, and student accommodation projects. Its positioning reflects a broad-sector approach anchored in production quality and repeat supply relationships. Offsite Solutions, located in Highbridge, Somerset, specializes in GRP composite and steel-framed pods and utility units, delivering over 10,000 units annually for main contractors and developers. Its scale and material breadth suggest a focus on throughput, consistency, and contractor-facing reliability.
Bathsystem S.p.A., headquartered in Calcinato, Italy, produces lightweight concrete and patented SUPERLIGHT galvanized steel frame solutions in controlled facilities, with annual capacity exceeding 12,000 units. Its strategy leans on proprietary frame technology and controlled production to support both bathroom pods and kitchen units, appealing to buyers who value structural efficiency and repeatable manufacturing. Interpod, based in Berkeley Vale, New South Wales, Australia, focuses on bespoke modular pods for residential, hospitality, healthcare, and defence applications, operating a dedicated factory with custom design and quality finishes. Its differentiation lies in tailored specification and finish quality for programs that require a higher degree of project-specific adaptation.
Prefabricated Security Booth Market
In North America, SurePods, headquartered in Orlando, Florida, has established itself as a factory-built pod supplier for healthcare, hospitality, and residential projects, using BIM and lean manufacturing with expanding facilities and ISO-compliant quality control. Its orientation toward digital specification and quality systems aligns with buyers seeking predictable interfaces and inspection-ready units. B&T Manufacturing, in Rapid City, South Dakota, uses FRAMECAD light-gauge steel technology to produce steel modular pods for hotels, healthcare, and commercial projects, emphasizing plug-and-play units with customizable layouts. Its approach highlights the role of light-gauge steel systems in balancing structural strength with layout flexibility.
European and emerging-market players add further variety. BAUDET, based in Mouchamps, France, has manufactured ready-to-install bathroom pods with full interior finish since 1992, supplying turnkey units for hotels, student residences, and social housing. Hydrodiseño, in Spain, produces prefabricated modular bathroom and kitchen pods with patented designs, targeting efficient, high-quality units for large-scale construction projects. Durapods, in the United States, offers offsite production through PDM Constructors, focusing on simplified logistics and faster delivery across residential and commercial markets. Loom Crafts, in India, produces custom prefabricated bathroom pods for hospitality, healthcare, and housing clients, reflecting growing regional manufacturing capacity and customization demand.
Strategic Positioning and Differentiation
Across these players, several recurring differentiation themes appear. Material expertise is one: some manufacturers emphasize GRP composites for corrosion resistance and low maintenance, while others lean on steel framing for structural strength and multi-story suitability. Production discipline is another: companies that can combine high annual throughput with controlled quality environments tend to win repeat contractor and developer relationships. Sector specialization also matters; firms aligned to hospitality, healthcare, student accommodation, or defence can tailor finishes, accessibility features, and compliance documentation to the expectations of those programs. Finally, interface readiness—BIM-aligned specifications, code documentation, and transport protection—increasingly separates suppliers that merely deliver units from those that reduce project risk.
Market Evolution: Consolidation, Differentiation, and New Entry
The market is likely to evolve along three paths simultaneously. First, consolidation pressure may intensify among mid-tier producers as scale, compliance documentation, and logistics capability become harder to sustain independently. Second, differentiation will deepen around material systems, finish flexibility, and sector-specific compliance, making product category less homogeneous than it once appeared. Third, new entry remains possible in regions where construction demand is expanding and where local production can reduce transport cost and lead-time risk, especially if entrants can combine customization with repeatable framing and quality systems.
Competition will not be won on unit price alone. Buyers are increasingly weighing total program impact: installation speed, inspection readiness, transport resilience, finish consistency, and the ability to adapt layouts without disrupting production. Suppliers that can demonstrate those attributes in repeatable ways are better positioned to secure long-term specification relationships rather than one-off project wins.
Forward Outlook: Trends and Commercial Implications
Looking across the current market trajectory and the forces shaping production, procurement, and regulation, three trends are likely to define the next three to five years.
1. Modular Variation as a Standard Capability
The next phase of growth will favor manufacturers that can offer configurable layouts, interchangeable finish options, and accessibility adaptations without sacrificing throughput. As pods move further into healthcare, defence, and higher-spec residential programs, the ability to vary the visible and functional elements of a unit—while keeping the underlying frame, connection logic, and quality process stable—will become a core selling point. The commercial implication is clear: product lines that enable specification flexibility within a controlled manufacturing regime will capture more diverse demand and reduce the risk of being undercut by lower-cost standardized alternatives.
2. Compliance and Inspection Readiness as a Procurement Criterion
Regulatory alignment will become increasingly embedded in buying decisions. Pods that are designed for code conformance, backed by clear documentation, and protected during transport and storage will face fewer site-level obstacles. Standards related to fire-retardant packaging and temporary protective materials, along with building and plumbing code expectations, will not only influence manufacturing practices but also shape supplier selection. Buyers will look for manufacturers that can reduce inspection friction and demonstrate repeatable compliance, especially in multi-jurisdiction or high-risk programs.
3. Program-Level Integration Over Component Purchasing
The market will increasingly reward suppliers and buyers who think in terms of total program delivery rather than isolated bathroom units. That means closer coordination on sequencing, interface points with the primary structure, crane and staging logistics, and finish schedules. It also means that partnerships between manufacturers, main contractors, and developers may become more structured, with earlier involvement in design and procurement to lock in compatibility and reduce change orders. The commercial opportunity lies in moving from transactional supply to specification-level influence, where the pod becomes part of a broader schedule and cost strategy.
PW Consulting
These trends carry risks. Material cost volatility and supply concentration can affect pricing and availability. Customization can erode the efficiency gains that make prefabrication attractive if variation is poorly managed. Compliance expectations can differ across regions and project types, creating hidden integration costs. And rapid growth can tempt less disciplined entrants to overpromise on lead times or finish quality, creating reputational and execution risk for buyers who do not vet suppliers carefully. The net effect is that the market rewards operational maturity as much as product capability.
Strategic Actions for Decision-Makers
For executives evaluating the prefabricated bathroom pods market, the priority is to convert market momentum into defensible operating choices. The following actions are most relevant depending on role and exposure.
For Manufacturers and Producers
- Invest in configurable product architectures that separate stable structural systems from variable finishes and layouts, preserving throughput while expanding addressable demand.
- Strengthen compliance documentation and inspection readiness as part of the core offering, including transport and storage protection aligned with relevant loss prevention and code expectations.
- Align production capacity and geographic footprint to the programs you want to win, weighing the trade-off between scale concentration and regional responsiveness.
For Investors and Capital Allocators
- Assess suppliers on total program value rather than unit pricing alone, focusing on throughput stability, quality control systems, sector alignment, and the ability to reduce schedule risk.
- Monitor material and logistics exposure, especially where steel, composite, or lightweight concrete inputs are central to a company's value proposition.
- Look for signs of repeatable specification relationships and multi-project pipelines, which tend to indicate stronger commercial moats than one-off wins.
For Procurement, Development, and Construction Leaders
- Engage manufacturers earlier in the design and procurement cycle to align specifications, code documentation, and interface requirements, reducing the likelihood of late-stage rework.
- Evaluate pods against total program metrics—schedule compression, on-site labor reduction, inspection friction, and logistics complexity—rather than isolating initial purchase cost.
- Build qualification criteria that include compliance readiness, finish consistency, transport protection, and the supplier's ability to support variation without disrupting production.
The pace of change in this market makes detailed, current intelligence valuable. Segment-level dynamics, regional demand patterns, material shifts, and competitive moves can alter both opportunity and risk quickly, especially for programs that depend on predictable lead times and compliant delivery. A fuller examination of these dimensions—supported by granular segmentation data, company-level activity, and scenario-based demand views—can help decision-makers pressure-test assumptions before committing to specifications, capacity decisions, or investment theses. Readers seeking deeper segmentation detail and tailored strategic guidance can access the complete PW Consulting research report for a more comprehensive view of the market landscape and its commercial implications.
For detailed analysis of this topic, please visit the official page: Prefabricated Bathroom Pods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


