



BAW Filters Market: Why 7.32% CAGR and Stratification Redefine 2032 Revenue to $5.5B

Beyond the Noise: Strategic Trends and Commercial Opportunities in the BAW Filters Market
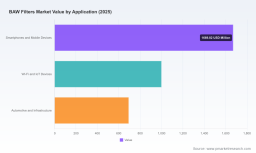
The BAW (Bulk Acoustic Wave) filters market has entered a phase of sustained, structurally driven expansion that rewards firms able to translate technological advancement into reliable supply and differentiated performance. Over the 2020-2025 historical window, the market grew from approximately 2,286.78 million to 3,361.14 million, reflecting a compound trajectory that accelerated through the mid-2020s as mobile device complexity and connectivity infrastructure converged. Looking ahead to the 2026-2032 forecast period, the market is projected to expand at a CAGR of 7.32%, reaching an estimated 5,512.51 million by 2032. This is not merely incremental growth; it reflects a fundamental recalibration of RF front-end design priorities as spectrum utilization, device form factors, and performance requirements continue to tighten.
For executives and investors, the headline figures convey scale, but the strategic signal lies in the dynamics beneath the surface. The market has moved past the early adoption curve for 5G and is now navigating a more nuanced environment shaped by competing filter technologies, intensifying spectrum congestion, and a concentration of capability among a small group of established players. At the same time, the demand base is broadening beyond smartphones into automotive connectivity, industrial IoT, and wireless infrastructure. Understanding where value is created—and where margins and market share are at risk—requires a clear read on the forces shaping this landscape.
Paint Filters Market
Market Landscape and Core Challenges
The current market size sits around 3,361.14 million as of the base year, and the forward projection of 5,512.51 million by 2032 reflects sustained demand across mobile, connectivity, and industrial applications. This trajectory is underpinned by rising RF content per device, the proliferation of multi-band and wideband designs, and the rollout of next-generation Wi-Fi and cellular standards that place greater stress on filtering performance. In this environment, BAW filters continue to command attention because of their ability to deliver high rejection, temperature stability, and compact integration in frequency ranges where SAW-based alternatives are increasingly strained.
Beneath these favorable dynamics, three challenges stand out as strategic inflection points.
1. Technology Choice and Coexistence Pressure
The filtering landscape is not a single-technology story. Film Bulk Acoustic Resonator (FBAR) and Solidly Mounted Resonator (SMR) approaches each present distinct trade-offs in performance, packaging, and manufacturing complexity. FBAR solutions have historically been associated with superior rejection curves and broad applicability in mobile and infrastructure settings, while SMR variants offer a different cost and integration profile. As device architectures demand more bands, more bandwidth, and tighter rejection, design teams must decide where to deploy each technology across bands and platforms. This decision is increasingly tied to total cost of ownership, not just unit performance, and the wrong allocation can create efficiency losses in both bill of materials and system-level gain.
2. Spectrum Reallocation and Filter Performance Requirements
The opening of substantial spectrum in the 6 GHz band for unlicensed use has accelerated the development of Wi-Fi 6E and Wi-Fi 7 products, which depend heavily on high-frequency, high-selectivity filters. This shift expands the addressable opportunity but also raises the performance bar. Higher frequency operation, wider channel plans, and greater spectral density mean that filters must maintain selectivity and stability under more demanding conditions. The result is a moving target for manufacturers: designs must be optimized not just for today’s network architecture but for the broader spectrum ecosystem that regulators and standards bodies continue to reshape.
3. Supply Security, Concentration, and Scale Economics
The market exhibits meaningful concentration, with a relatively small group of participants accounting for a large share of revenue. This concentration reflects the realities of technology maturity, packaging expertise, and the capital intensity of scaling high-performance RF components. For downstream customers, this creates a tension between sourcing reliability and competitive pressure. Qualifying new suppliers or alternative technologies involves engineering validation, production ramp risk, and long-term supply commitments. In such an environment, supply resilience becomes as important as unit cost, and multi-source strategies are gaining relevance for programs where downtime or component shortages carry significant system-level consequences.
Key Drivers Shaping the Market
Growth in the BAW filters market is not accidental. It is being propelled by a convergence of technology, regulation, demand behavior, and cost structure shifts that reinforce one another. The most consequential drivers are the following.
Technological Innovation and Performance Migration
The strongest driver is the ongoing migration of performance expectations across frequency ranges and use cases. High-performance platforms for mobile and connectivity devices are increasingly integrating BAW solutions to support wider bandwidths, more bands, and higher signal integrity requirements. Parallel innovation in packaging and integration—such as wafer-level packaging where applicable—supports miniaturization while preserving electrical performance. The push toward ultra-compact designs with improved efficiency and reduced footprint is especially relevant for next-generation smartphones and wireless devices, where board space and thermal constraints are unforgiving. In parallel, new high-frequency filter technologies are emerging that target lower insertion loss and improved signal efficiency for 5G, Wi-Fi 7, and early 6G scenarios, intensifying competition at the high end of the performance curve.
PW Consulting
Policy and Spectrum Regulation as Demand Catalysts
Regulatory and spectrum policy decisions are shaping demand with unusual clarity. The FCC’s decision to make 1200 MHz of spectrum in the 6 GHz band available for unlicensed use created a direct catalyst for products that require high-selectivity filtering at higher frequencies. In Europe, the steady rollout of 5G across major economies, combined with a strong industrial base and automotive sector, provides a stable demand backdrop that supports both consumer device growth and infrastructure-related RF content. At the same time, increasing emphasis on energy efficiency, electromagnetic compatibility, and compliance with stringent ETSI standards is reinforcing the value of high-quality filtering in both consumer and professional equipment. Regulatory pressure does more than create compliance obligations; it raises the baseline expectation for RF performance and reduces the tolerance for inferior solutions.
Demand-Side Shifts Across Devices and Verticals
On the demand side, the most notable change is the broadening of RF complexity beyond flagship smartphones. Devices are carrying more bands and more connectivity options, and the absolute RF content per device is rising across mobile, IoT, automotive, and infrastructure categories. Automotive and infrastructure applications, in particular, are expanding as connected vehicle features, telematics, and roadside infrastructure add new filtering requirements. The C-V2X domain illustrates this trend clearly, with new filter solutions being developed for 5.9 GHz operation and band 47 to support advanced automotive and infrastructure use cases. In the same way, Wi-Fi and IoT device growth is pushing demand toward filters that can handle higher frequencies while maintaining selectivity and reliability in dense deployment environments.
Cost Structure and Manufacturing Strategy
Cost dynamics are shifting as manufacturers pursue tighter integration, higher yield, and more efficient packaging. For high-volume mobile and connectivity applications, the ability to deliver strong RF performance within a smaller footprint is becoming a competitive differentiator, not simply a technical achievement. This favors participants who can combine product performance with disciplined manufacturing scale and consistent quality. At the same time, demand across industrial, aerospace, defense, and communications applications introduces additional complexity: customized solutions and reliable wafer-level packaging for specific frequency ranges can command premium positioning, but they also require specialized process control and customer-specific qualification. The net effect is that cost leadership and value leadership are increasingly defined by the ability to match technology choices to application requirements without sacrificing reliability or ramp capability.
Competitive Landscape and Leading Strategies
The competitive field in the BAW filters market is defined by a handful of companies with deep RF expertise, differentiated product portfolios, and strategies that emphasize either breadth, specialization, or manufacturing control. Rather than competing on price alone, leaders are building advantage through frequency range coverage, packaging capability, performance stability, and integration with next-generation standards.
Strategic Positioning Among Leading Participants
Several incumbents are shaping the market through distinct positioning. One established leader continues to emphasize BAW filtering solutions for mobile products, radar, and communications systems, with a focus on ultra-stable temperature performance and wafer-level packaging across frequencies in the 1.5-9 GHz range. This profile reflects a mobile- and radar-oriented strategy built on performance consistency and broad band coverage. Another participant has pursued a broader high-frequency and ultra-wideband angle, developing RF filters aimed at high-power and wideband scenarios across 5G/6G, Wi-Fi, automotive, defense, IoT, and Satcom markets. This approach signals an intent to capture demand where performance extremes matter and where filter requirements diverge from mainstream mobile designs.
A third participant has positioned itself around custom BAW RF filters with wafer-level packaging for specific frequency ranges in industrial, aerospace, defense, and communications applications. This specialization points toward a strategy that values tailored solutions and application-specific qualification over mass-market volume alone. A fourth company offers BAW filters integrated into high-performance platforms for mobile and connectivity devices, leveraging internal manufacturing for next-generation 5G and Wi-Fi standards. Integration of design and manufacturing can improve responsiveness and quality control, and may be especially valuable as standards evolve quickly and customers seek sustained supply alignment. A fifth player has emphasized FBAR-based BAW filters with strong rejection characteristics for 5G, Wi-Fi, and wireless infrastructure, reflecting a technology-specific focus that plays to the strengths of film-based acoustic resonance in demanding RF environments.
Recent product activity reinforces how competitive differentiation is evolving. In early 2026, one participant began sampling a C-V2X filter solution designed for 5.9 GHz operation, including band 47, targeting advanced automotive and infrastructure applications. This move illustrates how filter suppliers are expanding into connectivity domains where timing, reliability, and standards alignment are critical. Shortly afterward, another participant introduced ultra-compact BAW filter technology aimed at 5G and Wi-Fi 7 devices, emphasizing improved RF performance, higher efficiency, and reduced footprint for next-generation smartphone and wireless applications. These announcements are not isolated product updates; they are indicators of where competitive energy is being directed: higher frequency, smaller form factor, tighter integration, and new verticals.
Market Structure Evolution
The market is not simply consolidating around a single formula. Instead, it is showing signs of both concentration and selective divergence. Concentration remains meaningful, reflecting the advantages of scale, process maturity, and long-term customer qualification. At the same time, differentiation is increasing as suppliers target distinct frequency ranges, application verticals, and packaging philosophies. New entrants and technology alternatives can still find room where they address unmet needs in high-power, ultra-wideband, or specialized industrial and defense scenarios, but the bar to meaningful share gains is high. For incumbents, the strategic priority is to maintain performance leadership while expanding into adjacent demand areas such as automotive connectivity and infrastructure. For customers, the practical implication is that supplier selection is increasingly a multi-dimensional decision involving performance, supply resilience, standards alignment, and long-term roadmap compatibility.
Future Trends and Commercial Implications
Based on the current trajectory and the forces already in motion, two to three trends are likely to shape the next three to five years.
Higher-Frequency, Multi-Standard Filter Architectures Will Become the Norm
As 5G matures, Wi-Fi 6E and Wi-Fi 7 expand, and early 6G exploration advances, RF front ends will need to support wider frequency coverage and more simultaneous standards. Filters will be expected to perform not just in a single band but across broader, more complex spectral environments. This creates commercial opportunities for suppliers that can deliver high-selectivity solutions with stable temperature behavior, low insertion loss, and packaging that supports denser integration. It also raises the importance of design flexibility, because device manufacturers will want platforms that can adapt to evolving band plans and channel allocations without sacrificing performance.
Bypass Filter Market
Automotive, Infrastructure, and Industrial Demand Will Grow in Strategic Importance
Automotive and infrastructure applications are becoming more prominent in the demand mix, driven by connected vehicle features, C-V2X expansion, and the broader rollout of wireless infrastructure. These segments often emphasize reliability, temperature resilience, and long program lifecycles, which can reward suppliers with disciplined qualification processes and consistent continuity. For companies able to align product roadmaps with automotive and infrastructure timing, the opportunity is not just additional volume but a more diversified revenue base that can partially offset cyclicality in consumer device cycles.
Supply Strategy and Multi-Source Qualification Will Matter as Much as Performance
As concentration remains high and standards evolve quickly, downstream customers will place greater weight on supply resilience, ramp support, and the ability to qualify alternative sources where appropriate. This does not mean uniformity; different applications may continue to require different solutions. But it does mean that companies with flexible sourcing strategies, robust validation capabilities, and transparent roadmap communication will have an advantage in critical programs. The commercial implication is that value will increasingly accrue to participants who can reduce total risk for their customers, not only deliver a strong unit specification.
Risks and Uncertainties
These trends carry meaningful uncertainty. Technology competition between FBAR, SMR, and emerging alternatives could shift cost-performance trade-offs faster than expected, particularly if new high-frequency filter approaches improve efficiency or reduce insertion loss in commercially meaningful ways. Regulatory and spectrum decisions may accelerate demand in some bands while constraining others, creating uneven growth across applications. Standard cycles and device adoption timing can also affect the pace of content increases, especially if device roadmaps shift or if integration strategies change. Finally, the capital intensity and process sensitivity of high-performance filter manufacturing mean that execution risk remains a real factor; ramp delays, yield issues, or qualification challenges can have outsized consequences in a concentrated market.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product roadmaps with the direction of spectrum use, device complexity, and vertical expansion. That means investing in higher-frequency and wideband capabilities, continuing to sharpen packaging and integration for compact high-performance platforms, and preparing for demand growth in automotive and infrastructure as well as mobile and connectivity. Equally important is disciplined qualification and supply continuity, since customer trust in RF components is built on consistency as much as on specification performance.
For investors, the strategic question is not whether the BAW filters market will continue to expand, but where durable advantages are being created. The most attractive positions are likely to be those that combine technology leadership with the ability to scale reliably, support next-generation standards, and address a diversified set of applications. Attention should be paid to participants that are extending into automotive, infrastructure, and specialist high-frequency domains, as well as those with integrated design-and-manufacturing strategies that can respond quickly to changing requirements. At the same time, it is worth monitoring technology alternatives and supply-side execution, since shifts in either can alter competitive positioning.
For procurement and sourcing leaders, the most prudent approach is to treat filtering as a system-critical decision rather than a commodity purchase. That includes evaluating not just unit cost and baseline performance, but also temperature stability, rejection characteristics, packaging fit, standards alignment, and the supplier’s ability to support long program lifecycles or rapid platform evolution. Where feasible, developing qualified alternatives for critical bands can reduce exposure to concentration risk, especially in applications where downtime or performance shortfalls carry significant consequences.
The strategic picture is clear enough to act on, but the details matter. Fine-grained segmentation, frequency-specific demand profiles, technology-specific cost structures, and company-level roadmap mapping can materially change sourcing and investment judgments. For readers seeking a more detailed breakdown of market size by segment, competitive positioning across frequency ranges and applications, and customized implications for a specific product portfolio or sourcing strategy, a comprehensive research report can provide the level of detail needed to support more precise decision-making.
For detailed analysis of this topic, please visit the official page: BAW Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


