



PAPR Market Set for 8.3% CAGR Growth: Unpacking the Forces Behind 2032’s $5.38 Billion Outlook

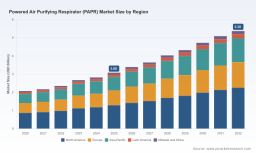
Powered Air Purifying Respirator Market: Strategic Trends and Commercial Opportunities, 2025–2032
The Powered Air Purifying Respirator market has transitioned from a specialized niche into a strategic infrastructure investment across healthcare, industrial manufacturing, energy, and construction. Since 2020, annual revenue has expanded from approximately 2.07 billion to 3.08 billion, reflecting a compound annual growth rate of 8.3 percent through 2032. By the end of the forecast window, total market value is projected to reach 5.38 billion. This trajectory is not merely a function of incremental demand; it signals a structural shift in how organizations approach respiratory protection, occupational safety compliance, and workplace readiness.
Regional leadership remains firmly anchored in North America, followed by Europe and Asia Pacific, while Latin America and the Middle East and Africa collectively represent emerging demand corridors. The product landscape is dominated by half mask configurations, which account for the largest share of total revenue, with full face mask and hood variants serving specialized use cases where field of view, comfort, or contamination control requirements differ. In application terms, healthcare and manufacturing represent the two largest demand pools, with oil and gas, construction, and ancillary sectors providing complementary growth vectors.
Despite the favorable growth outlook, the market operates under a moderate concentration profile. The three largest players control roughly 54.5 percent of total revenue, and the top five firms account for approximately 65.0 percent. This concentration shapes pricing discipline, channel access, and the pace at which innovation diffuses across the industry. At the same time, it leaves meaningful room for differentiated entrants, particularly in product formats, regional distribution, and application-specific engineering.
Executives evaluating exposure to this market should view it as a convergence point between regulatory evolution, engineering upgrades, and changing workplace risk profiles. The growth numbers provide directionality, but the strategic value lies in understanding where demand is becoming more repeatable, where compliance friction is easing, and where battery, filtration, and ergonomics are redefining product competitiveness.
Key Challenges and Inflection Points
The market's expansion is real, but it is not frictionless. Three challenges currently define the strategic inflection point for suppliers, buyers, and investors.
The first is the tension between regulatory streamlining and quality assurance. Recent draft guidance from the U.S. Food and Drug Administration and proposed updates from the Occupational Safety and Health Administration signal a clear intent to reduce premarket and medical clearance burdens for certain respiratory protection categories, including NIOSH-approved powered air-purifying respirators used in healthcare and public health settings. While these adjustments can accelerate procurement and broaden adoption, they also introduce a different type of risk: organizations must maintain rigorous internal validation and post-market surveillance when external clearance requirements loosen. The same guidance cycle has also referenced a Class 2 device recall involving 528 units tied to potential mis-assembly of elastic headband rivets to the face shield. That incident underscores a broader point—regulatory flexibility does not eliminate the need for robust design control, assembly consistency, and field reliability.
The second challenge centers on total cost of ownership rather than unit price. Battery systems, particularly lithium-ion and nickel-metal hydride chemistries, represent a primary material expense in powered respirator architectures. Equally important are the labor and administrative costs tied to fit-testing, maintenance protocols, filter replacement, and hospital or plant-level respiratory protection programs. For buyers, the economic question is shifting from “What is the purchase price?” to “What does a dependable protection program cost across its lifecycle?” For manufacturers, this reorients innovation toward battery endurance, serviceability, consumable logistics, and ease of inspection.
The third challenge relates to reimbursement and procurement categorization in healthcare. Current coding and reimbursement structures do not reflect a dedicated, updated framework for powered air-purifying respirator consumables and program costs. Hospitals and health systems continue to classify these items under existing procedures, which can create budgetary friction when scaling protection programs. The absence of specific reimbursement revisions means that adoption in healthcare is being driven less by incremental reimbursement incentives and more by institutional risk management, infection control priorities, and internal compliance mandates. That dynamic favors suppliers who can demonstrate program-level value rather than product-level savings alone.
Together, these challenges point to a market that is maturing but still uneven. Growth will increasingly favor organizations that can align product design, service model, and regulatory navigation with how buyers actually budget and operate.
Core Demand Drivers
Technology Innovation and Product Architecture
Engineering progress is reshaping the value proposition of powered respirators. Recent product activity illustrates how manufacturers are competing on usability, runtime, and filtration performance rather than basic protection alone. In early 2025, Bullard introduced a third-generation system with an improved battery architecture, higher filter efficiency, and streamlined maintenance protocols. These changes matter because they reduce the operational burden on end users and simplify inventory and service planning for safety teams.
At the same time, form factor diversification continues to expand the addressable use cases. Half mask systems remain the volume leader because they offer a pragmatic balance of protection, compatibility, and cost. Full face mask designs serve environments where face and eye protection integration is critical. Hood configurations address scenarios where loose-fitting comfort, extended wear time, and minimization of fit-testing dependency are priorities. The practical implication is that product strategy is less about a single winning configuration and more about matching architecture to workflow, environment, and compliance profile.
Particulate Respirators Market
Battery performance remains a central technical battleground. Runtime, charging logistics, thermal stability, and replacement cycles directly influence field adoption, particularly in healthcare settings where continuity of care and shift-based usage are critical, and in industrial environments where maintenance windows are tightly constrained. Innovations that improve effective runtime or reduce downtime can create meaningful competitive advantage, especially when paired with better diagnostic indicators and predictable consumable schedules.
Regulatory and Compliance Environment
The regulatory trajectory is a powerful demand catalyst, but its effects are nuanced. The April 2026 draft guidance from the U.S. Food and Drug Administration proposes an enforcement discretion compliance policy for NIOSH-approved powered air-purifying respirators and other non-surgical respirators, aimed at reducing premarket requirements for healthcare and public health usage. This type of guidance tends to shorten procurement cycles and lower administrative barriers, which can stimulate demand in health systems and public-sector buyers.
In parallel, the July 2025 proposed amendments from the U.S. Occupational Safety and Health Administration target medical evaluation requirements, removing clearance mandates for users of filtering facepiece respirators and loose-fitting powered air-purifying respirators. The rationale cited in the proposed rule rests on insufficient evidence that such clearance materially reduces impairment in the covered populations. If finalized, this shift would lower a persistent administrative obstacle, particularly for organizations that deploy loose-fitting systems at scale and have struggled with medical evaluation throughput.
Worldwide Medical Powered Air Purifying Respirators Market
These developments should not be interpreted as a blanket deregulation of respiratory safety. Instead, they reflect a targeted recalibration: the regulatory burden is being adjusted where evidence suggests limited marginal benefit, while foundational protection standards remain in force. For the market, the result is likely to be faster adoption in specific channels, greater emphasis on post-market quality, and a growing premium on manufacturers who can provide clear documentation, validated performance, and traceable quality systems.
Demand-Side Behavior and Workplace Risk Perception
Demand is being shaped by a durable change in how organizations think about airborne exposure. In healthcare, respiratory protection programs have moved from episodic compliance to a more continuous readiness mindset. The use of powered air-purifying respirators in clinical and decontamination contexts is increasingly influenced by the need to protect staff during airborne pathogen exposure risk, aerosol-generating procedures, and environmental cleaning operations. Even where reimbursement codes remain unchanged, institutional decision-making is driven by staff safety, operational continuity, and the desire to reduce fit-test dependency for certain loose-fitting deployments.
In industrial environments, demand is tied to both compliance and productivity. Manufacturing and oil and gas operations use powered respirators where particulate exposure, chemical environments, or extended task duration make passive protection less practical. Construction and related trades use them in scenarios where dust, abrasive materials, or mixed-exposure conditions create recurring protection needs. A notable channel development is the expansion of welding-focused solutions through distribution partnerships, which broadens access to specialized air-purifying configurations in fabrication and metalworking settings.
A subtle but important demand shift is the growing preference for solutions that reduce operational friction. Buyers are increasingly attentive to battery swap convenience, filter life clarity, cleaning procedures, and the time burden imposed on safety coordinators. This does not make price irrelevant, but it does mean that competitive differentiation is increasingly derived from program convenience and reliability as much as from protection specifications alone.
Supply Chain, Cost Structure, and Procurement Dynamics
Cost structures in this market are influenced by more than raw material prices. Battery chemistry costs, filter media, housing components, and assembly labor all feed into final pricing, while fit-testing, maintenance labor, and consumable replacement shape the recurring cost profile for end users. In hospital and industrial settings, these operational costs can dominate the economics of a protection program, particularly when deployment scales across multiple sites or shifts.
Supply chain stability matters because respiratory protection is both safety-critical and usage-sensitive. Intermittent availability of filters, batteries, or replacement components can undermine program confidence even when the base equipment is sound. As a result, suppliers that can offer predictable consumable availability, clear service intervals, and localized support often gain an advantage that is not fully captured by headline product specifications.
For procurement teams, this environment rewards a more programmatic purchasing approach. Rather than evaluating individual units in isolation, buyers are increasingly assessing how equipment, consumables, training, and maintenance fit together across a season of use. That shift creates opportunities for suppliers to bundle service elements, provide usage forecasting, and reduce the administrative load on safety teams.
Competitive Landscape and Leadership Strategies
The competitive environment is defined by a small group of well-positioned manufacturers with distinct engineering legacies, channel strengths, and application focus areas. The market’s moderate concentration gives established players meaningful scale advantages, while still leaving space for differentiated positioning.
Dräger occupies a strong position in industrial and decontamination-oriented powered respirator systems, with helmet and facepiece architectures designed for demanding environments. Its strategic value lies in integration, durability, and the credibility of a safety-focused brand in heavy-duty applications. For buyers in industrial and specialized decontamination settings, Dräger’s appeal often centers on perceived reliability and alignment with stringent operational requirements.
3M maintains a broad industrial footprint with powered air-purifying respirator systems built for heavy industrial and hazardous location use. Its advantage is scale, distribution reach, and the ability to position respiratory protection within a wider ecosystem of safety and industrial products. In markets where procurement relies on consolidated vendor relationships and multi-product support, that breadth can be a decisive factor.
MSA Safety combines its own powered respirator portfolio with targeted distribution partnerships, including the introduction of welding and industrial-focused air-purifying systems through an exclusive North American partnership. This hybrid approach is strategically significant. It allows MSA to expand its application coverage without building every solution internally, while leveraging existing channel relationships to reach welding, fabrication, and general industrial users more efficiently.
Bullard’s recent product refresh highlights a different competitive angle: iterative improvement in battery system design, filter efficiency, and maintenance simplicity. In a market where operational friction often determines adoption, Bullard’s focus on usability and upkeep can resonate with buyers seeking to reduce training burden and service complexity. The company’s positioning is especially relevant where industrial protective equipment programs value straightforward maintenance and predictable consumable management.
AirBoss Defense Group brings a compact, lightweight design philosophy to the market, with configurations that emphasize portability and particulate protection, including NIOSH-approved options. Its relevance lies in use cases where weight, mobility, and streamlined form factors matter, particularly for teams that need protection without the burden of bulkier systems.
Taken together, the competitive landscape is evolving along three paths. One is consolidation of capability, where larger players use portfolio breadth and distribution to capture cross-application demand. Another is application specialization, where firms deepen their relevance in healthcare, welding, decontamination, or heavy industry through product tuning and channel focus. The third is selective partnership and distribution, which accelerates market access for specialized systems without requiring full vertical build-out. New entrants and smaller firms are most likely to succeed where they solve a specific operational pain point, serve an underserved geography, or offer a form factor that better matches a particular workflow.
Forward Outlook: Three Trends to Watch
Trend One: Faster Adoption in Healthcare and Public Health Settings Through Regulatory and Workflow Alignment
The combination of draft FDA guidance and proposed OSHA amendments is likely to lower administrative barriers for selected powered respirator deployments. If these developments move toward final implementation, healthcare and public health buyers may accelerate evaluation and procurement, especially where programs are designed around loose-fitting options and reduced medical clearance friction. The strategic opportunity here is not simply more units sold; it is the emergence of more standardized procurement pathways, more repeat demand, and greater interest in systems that integrate cleanly into infection control and staff protection workflows.
The associated risk is uneven adoption. Institutions will still differ in how they interpret guidance, manage internal validation, and budget for consumables. Suppliers that over-index on regulatory optimism without supporting program-level usability and service may find adoption slower than the headline environment suggests.
Trend Two: Continued Competition Around Battery, Filtration, and Maintenance Experience
Over the next several years, competitive advantage will increasingly hinge on runtime, charging convenience, filter life clarity, and maintenance simplicity. Buyers are likely to favor systems that reduce downtime, make consumable management predictable, and minimize the training burden for frontline users and safety coordinators. Manufacturers that can pair solid protection performance with a better operational experience should be able to command preference even in a market where multiple products meet baseline requirements.
The risk on this front is that battery and filtration innovation can be copied incrementally, and price competition can intensify once a category matures. Durable advantage will depend on execution quality, support infrastructure, and the ability to demonstrate measurable reductions in program friction, not just specification upgrades.
Trend Three: Program-Level Purchasing and Service Differentiation
As total cost of ownership becomes more central, procurement is likely to shift further toward program-oriented evaluation. That means greater weight on filter supply reliability, battery replacement logistics, maintenance protocols, fit-testing strategy where applicable, and vendor support responsiveness. Suppliers that help buyers plan and manage these elements—rather than only deliver hardware—will be better positioned in competitive bids and multi-year deployments.
The uncertainty here lies in how consistently different buyer segments will adopt program-level thinking. Industrial procurement may move faster in environments with strict compliance cycles and high usage, while other segments may continue to prioritize unit economics and approval simplicity. Companies that can tailor their commercial model to the buying habits of each segment will be more resilient.
Action Considerations for Decision Makers
For manufacturers and product leaders, the priority is to align engineering roadmaps with where buyers feel friction most acutely. Battery lifecycle, filter service clarity, cleaning and maintenance simplicity, and form factor fit for specific applications should be treated as core value drivers, not secondary features. Equally important is the quality system behind the product. Recent regulatory and recall signals indicate that documentation, assembly consistency, and post-market reliability will remain central to market access and customer trust. Firms should also consider where partnerships or targeted distribution agreements can expand application coverage more efficiently than internal expansion alone.
For investors, the market offers a constructive demand backdrop, but selection matters. The most resilient opportunities are likely in companies with defensible application positioning, credible quality and compliance processes, and commercial models that address recurring consumables and support rather than one-time hardware sales alone. Monitoring the trajectory of FDA and OSHA actions will be important, but the more durable signals will come from product adoption patterns, channel execution, and the ability to reduce operational burden for end users. Investors should also watch for consolidation activity, especially where larger players seek to fill application gaps or strengthen regional distribution.
For procurement and safety leaders, the practical move is to evaluate powered air-purifying respirators as part of a protection program rather than as stand-alone purchases. That evaluation should include battery and filter logistics, maintenance workload, training requirements, and support responsiveness alongside protection performance. Where loose-fitting systems are appropriate, the evolving regulatory environment may reduce certain administrative steps, but internal validation and quality verification remain essential. Buyers should also clarify how consumables will be sourced over time, because program confidence depends heavily on predictable availability and clear replacement intervals.
For organizations seeking a sharper view of segment-level demand, regional variation, product configuration economics, and competitive positioning across specific application niches, a more detailed research deep dive can help translate these market-wide trends into segment-specific decisions. The broad trajectory of the powered air purifying respirator market is clear; the strategic advantage comes from understanding where within that trajectory the most actionable opportunities and risks sit for your particular operating context.
PW Consulting
For detailed analysis of this topic, please visit the official page: Powered Air Purifying Respirator (PAPR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


