



Roadmarking Paints Market 5.8% CAGR: Strategic Shifts Behind the $10.6B 2032 Trajectory

Strategic Trends and Commercial Opportunities in the Roadmarking Paints Market
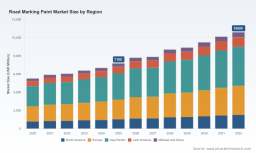
The global roadmarking paints market has entered a phase of mature expansion, characterized by steady demand recovery across infrastructure sectors and a gradual shift in material preferences. With a market valuation of 7.18 billion USD in 2025, the sector has demonstrated consistent revenue growth from 5.52 billion USD in 2020, reflecting a compound annual growth rate of 5.8 percent through the forecast period extending to 2032. This trajectory suggests that the industry is moving beyond post-pandemic normalization into a structure defined by regulatory evolution, material innovation, and geographic demand divergence. At first glance, the numbers indicate a reliable growth engine for coatings and infrastructure suppliers. A closer look reveals a market navigating cost volatility, tightening environmental specifications, and intensifying competition among established players and emerging regional suppliers.
The current landscape is shaped by three interconnected dynamics that decision-makers cannot afford to overlook. First, the transition toward low-emission and waterborne coating systems is accelerating, but the pace of adoption remains uneven across regions and project types. Second, raw material price fluctuations, particularly in thermoplastic compounds, specialty resins, and optical glass components, are compressing margins and forcing procurement strategies to become more flexible. Third, infrastructure spending is increasingly being directed toward high-visibility, safety-critical applications, which elevates the standard for durability and reflectivity but also raises the bar for supplier qualification. These forces create a market that is expanding in aggregate yet becoming more selective in how value is captured.
Navigating the Current Inflection Points
The market’s growth narrative is not uniform. While overall demand continues to climb, several structural pressures are reshaping how manufacturers, contractors, and public agencies evaluate roadmarking solutions. The expansion of urban and interurban road networks, combined with periodic resurfacing programs, sustains baseline demand. However, the composition of that demand is shifting. Projects are increasingly scrutinized for lifecycle cost, environmental footprint, and compliance with updated technical specifications. This means that suppliers offering conventional solvent-based products without clear pathways to compliant alternatives face growing friction in specification lists and bidding processes.
At the same time, the industry is witnessing a quiet recalibration of cost expectations. Budget-constrained infrastructure programs are more sensitive to upfront material pricing, which can slow the uptake of premium thermoplastic and specialized cold plastic systems. The tension between performance requirements and cost containment is not simply a procurement inconvenience; it is a strategic variable that determines which product categories gain traction in different project environments. Suppliers that can balance performance, compliance, and total cost of ownership are positioned to secure more consistent wins, while those locked into single-format portfolios may encounter narrowing windows of opportunity.
A third inflection point lies in the standardization and enforcement of roadmarking specifications. Updated technical benchmarks for ready-mixed paints and related marking materials are raising the minimum threshold for adhesion, durability, and reflectivity. These updates are not merely administrative; they influence which formulations are acceptable for public works, how frequently markings must be renewed, and what documentation suppliers must provide. For companies operating across multiple markets, alignment with evolving specifications is becoming a competitive differentiator rather than a baseline requirement.
Key Drivers Reshaping Market Dynamics
Technological Innovation and Material Evolution
Material science is quietly redefining what roadmarking paints can do. Waterborne formulations have advanced significantly in terms of drying time, abrasion resistance, and wet-edge performance, making them increasingly viable for high-traffic corridors where downtime is costly. At the same time, thermoplastic and cold plastic systems continue to be valued for their durability and reflective performance in demanding applications, but their deployment is increasingly tied to project economics and supply availability. The practical outcome is a market where performance claims must be substantiated by application-specific evidence, not just laboratory benchmarks.
Innovation is also extending beyond the paint itself. Improvements in optical glass quality, bead shape consistency, and bond strength are influencing the longevity of marked lines, which in turn affects maintenance cycles and total project cost. Suppliers that integrate material formulation with application technology, including spray equipment compatibility and line-width precision, are delivering more predictable outcomes for contractors and road authorities. This convergence of formulation and application engineering is reducing variability in the field, which is increasingly important as agencies compare bids on the basis of lifecycle performance rather than unit price alone.
Policy and Regulatory Pressures
Regulatory expectations are becoming a central force in product selection. Concerns over volatile organic compound emissions and broader environmental impact are prompting many procurement entities to favor lower-emission alternatives. This does not automatically eliminate solvent-based systems from the market, but it does raise the importance of documentation, emission profiles, and regional compliance pathways. In practice, regulation is acting as both a constraint and a catalyst: it limits the unconstrained use of older chemistries while creating demand for suppliers who can demonstrate credible low-emission performance without sacrificing durability.
Technical specifications are also evolving. Updated standards for ready-mixed road marking paints and related systems are tightening expectations around consistency, application conditions, and performance verification. For manufacturers, this means that product development cycles must account for specification alignment in key markets. For distributors and contractors, it means that stocking decisions and bidding strategies need to reflect the likely direction of regulatory enforcement. The companies that treat specification updates as early signals rather than late obstacles are better positioned to maintain preferred status on project shortlists.
Demand-Side Shifts in Infrastructure and User Behavior
Demand is being influenced by more than road construction volume. Public safety priorities, traffic growth, and the operational needs of airports and commercial parking facilities are all contributing to more frequent marking cycles and higher visibility requirements. Roads and highways remain the dominant application context, but the strategic importance of parking areas and airport tarmacs should not be underestimated. These environments often require specialized markings that can withstand different stress factors, from heavy vehicle turning loads to aircraft pavement conditions, and they tend to be less price-sensitive when reliability is at stake.
There is also a behavioral shift on the part of procurement teams. Buyers are increasingly comparing solutions on a total-cost basis that includes application efficiency, drying time, weather tolerance, and expected service life. This is changing the conversation from “which paint is cheapest per liter” to “which system delivers the best outcome over the project cycle.” Suppliers that can articulate these trade-offs clearly, and back them with field-relevant performance data, are gaining influence in specification decisions.
Supply Chain and Cost Structure Realignment
Cost structures in the roadmarking paints market are under pressure from multiple directions. Volatility in raw material pricing, especially for thermoplastic compounds and specialty glass components, creates uncertainty for both manufacturers and buyers. The challenge is compounded by differences in sourcing availability across resin suppliers and regional supply networks, which can affect lead times and price consistency. For companies relying on fixed-price contracts or tight bidding windows, this volatility can quickly translate into margin compression or project risk.
In response, supply chain resilience is becoming a strategic priority. Some suppliers are diversifying input sources, renegotiating terms with material partners, or adjusting product portfolios to reduce exposure to the most volatile components. Others are investing in formulation efficiency to stretch high-cost inputs while maintaining performance. The broader implication is that cost advantage in this market is increasingly determined by procurement agility and formulation discipline, not simply by scale. Firms that can manage input variability while preserving product consistency will be better equipped to offer stable pricing and reliable fulfillment, which are increasingly valued in competitive procurement environments.
Competitive Landscape and Strategic Positioning
The market is characterized by a concentrated core of established coatings and infrastructure material providers alongside a broader base of regional and specialized players. This structure creates a competitive environment where scale, product breadth, and technical service capability matter, but so does local specification knowledge and adaptability to regional procurement practices. The presence of major global names reflects the importance of cross-market reach, integrated product portfolios, and the ability to support large infrastructure programs with consistent supply and technical documentation.
Several leading companies illustrate the different ways to compete. PPG Industries has built recognition around waterborne and solvent-based traffic paint systems, emphasizing formulation families designed for road marking applications. Its positioning reflects a broader strategy of offering choices that align with varying regulatory and performance requirements while maintaining a consistent technical backbone. Swarco, with operations spanning multiple regions, provides a mix of solvent-based, waterborne, and two-component systems, which allows it to match products to project-specific conditions and specification environments. This breadth supports flexibility in bidding and application scenarios.
Meon Ltd has carved out a role focused on line marking paints and cold plastic systems for roads, parking lots, and airports, highlighting the value of serving multiple application contexts with a coherent product set. Axalta Coating Systems contributes a portfolio that includes spirit-soluble and modified alkyd formulations, showing continued relevance for markets where established chemistries still fit within accepted specifications. Cloverdale Paint Inc underscores another competitive angle: regional specification alignment. Its waterborne traffic paint formulations approved for Canadian infrastructure specifications illustrate how regulatory fit and local qualification can be decisive in securing market access.
Differentiation Beyond Product Catalog Breadth
In a market where many players offer overlapping product categories, differentiation is increasingly determined by how well a supplier can reduce risk and uncertainty for the buyer. Technical support, specification readiness, application guidance, and consistent quality control are becoming part of the core value proposition. Companies that can help contractors and public agencies navigate formulation choices, meet updated standards, and manage application conditions are building a defensible position that is harder to replicate than price alone.
This also means that the competitive battleground is shifting from pure product features to service-integrated solutions. Suppliers that combine reliable product performance with practical field support, clear compliance documentation, and predictable supply are better positioned to win repeat business and preferred supplier status. In contrast, competitors that rely primarily on catalog breadth without strong technical and service integration may find themselves vulnerable when buyers compare total project risk and lifecycle outcomes.
Portfolio Evolution and Market Structure Trends
The competitive landscape is likely to continue evolving through a combination of consolidation, portfolio specialization, and selective entry by regional players. Larger firms may pursue broader coverage through acquisitions or geographic expansion, aiming to strengthen supply continuity and specification reach. Smaller and mid-sized suppliers may compete by focusing on niche applications, regional specifications, or specialized material systems that larger players deprioritize. At the same time, new entrants with differentiated formulations or application-focused technologies could gain traction in segments where durability, drying speed, or environmental compliance are especially valued.
One important trend is the growing importance of portfolio coherence. Buyers are less interested in isolated product lines and more interested in suppliers that can address a range of marking needs across roads, parking areas, and airports with consistent quality and clear technical guidance. This favors companies that can offer a structured portfolio rather than fragmented offerings, while still retaining the flexibility to serve project-specific requirements. Another trend is the increasing relevance of regional compliance knowledge. As specifications become more localized and more stringent, suppliers with strong familiarity with local standards and procurement practices are gaining an edge in winning formal qualifications and specification inclusions.
Forward Outlook: Trends Shaping the Next 3 to 5 Years
Over the next several years, the roadmarking paints market is likely to be shaped by three reinforcing trends. The first is the continued migration toward lower-emission and more durable marking systems, driven by regulatory expectations, safety priorities, and total-cost considerations. This will not result in a single dominant chemistry across all contexts. Instead, it will produce a more segmented market in which waterborne, thermoplastic, and cold plastic solutions coexist, each anchored to specific application profiles and specification regimes.
Traffic Marking Paints Market
The second trend is the growing emphasis on supply chain stability and cost predictability. As raw material volatility and specification updates continue to influence procurement decisions, suppliers that can manage input risk, maintain consistent quality, and offer transparent pricing logic will be rewarded with stronger customer relationships and more resilient order flow. This trend favors organizations that treat supply chain management as a strategic capability rather than an operational back-office function.
The third trend is the increasing role of performance verification and lifecycle thinking in specification and bidding processes. Buyers are likely to place greater weight on demonstrated durability, reflectivity retention, application efficiency, and compliance readiness. This creates opportunities for suppliers that can provide credible evidence of field performance and support buyers in evaluating total project outcomes. It also introduces risk for companies that depend on price-based competition without a clear performance narrative or specification alignment.
These trends open commercial opportunities in several areas. Suppliers with strong waterborne or low-emission portfolios can benefit from specification shifts in markets where emission constraints are tightening. Companies with robust thermoplastic and cold plastic capabilities can focus on high-durability applications where performance justifies premium positioning, especially if they can manage cost exposure effectively. There is also room for service-led differentiation, where technical support, application guidance, and specification expertise become the basis for preference rather than product features alone. At the same time, uncertainty remains. Raw material cost swings, uneven regulatory enforcement, and project budget constraints can all slow adoption or shift demand between product categories. Firms that monitor these variables closely and adjust portfolios and procurement strategies accordingly will be better prepared to capture upside while limiting downside.
Strategic Implications for Decision-Makers
For Manufacturers and Material Formulators
Portfolio strategy should be guided by the need to balance compliance, durability, and cost control. Rather than treating product lines as static offerings, manufacturers can benefit from aligning formulations with the specification trajectories of key markets and identifying where performance claims can be credibly extended. Investment in application-relevant testing, clear documentation, and supply chain flexibility can strengthen competitive positioning more reliably than incremental catalog expansion alone. Companies should also consider where they can reduce exposure to volatile inputs without compromising field performance, since cost stability is increasingly part of the value proposition.
PW Consulting
For Investors and Strategic Buyers
The market offers exposure to steady infrastructure-linked demand, but value creation will likely come from companies that can manage regulatory transitions, supply variability, and application performance in an integrated way. Due diligence should pay attention to specification alignment, regional qualification strength, and the ability to serve multiple application environments with coherent product and service offerings. Businesses that rely heavily on single-format dependency or on price competition in volatile input conditions may face narrower margins for error. Strategic acquisitions or partnerships that expand compliance coverage, regional reach, or service capability can create advantages in a market where buyer preferences are shifting toward reliability and lifecycle value.
For Procurement Teams and Infrastructure Buyers
Evaluating roadmarking solutions with a total-cost perspective can reduce project risk and improve long-term outcomes. This means accounting for application speed, drying behavior, weather tolerance, expected service life, and compliance readiness alongside unit pricing. Early engagement with suppliers on specification alignment and performance expectations can help avoid mismatches during bidding and execution. Procurement teams can also benefit from tracking specification updates and material availability trends, since these often signal which product categories will become easier or harder to source at competitive terms in upcoming project cycles.
Paint Market
For all of these audiences, the value of detailed market intelligence lies in its ability to connect broad trends to specific decisions. Segment-level demand patterns, regional specification trajectories, raw material exposure by product category, and competitive positioning by application context all influence how the market will evolve beyond the headline growth narrative. A more granular view helps manufacturers prioritize formulation and portfolio choices, helps investors identify where durable advantage is being built, and helps procurement teams structure sourcing strategies that are resilient to both regulatory and cost-side uncertainty.
The roadmarking paints market is not simply expanding; it is restructuring around performance expectations, environmental mandates, and supply chain realities. Companies that interpret these signals early and align their strategies accordingly are more likely to convert market growth into sustained commercial advantage. For decision-makers seeking a deeper, segment-level view of demand splits, regional specification trends, raw material exposure, and competitive positioning across product types and application contexts, the full PW Consulting market report provides the additional granularity needed to support planning, procurement, and investment decisions with greater confidence.
For detailed analysis of this topic, please visit the official page: Roadmarking Paints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


