



Cat Litter Market 2026: Why 5.5% CAGR and Clay Dominance Signal a Strategic Shift

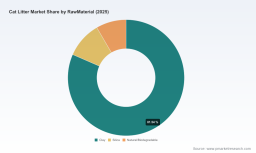
Strategic Shifts Defining the Global Cat Litter Market (2025–2032)
The global cat litter market has evolved from a low-differentiation commodity category into a strategically contested space shaped by material science, consumer expectations, and tightening operational standards. With the market reaching an estimated USD 11.81 billion in 2025 and expanding at a compound annual growth rate of approximately 5.5 percent through 2032, the category’s trajectory reflects broader shifts in pet care, sustainability, and retail consolidation. Growth is not uniform, and the value creation path is increasingly segmented by formulation performance, supply chain resilience, and brand trust. For executives and investors, the opportunity lies less in chasing volume and more in aligning product portfolios, manufacturing capabilities, and distribution strategies with structural demand changes.
Several factors sharpen the strategic stakes. Household penetration of cats continues to rise in mature markets, while emerging markets are building foundational pet care consumption patterns. At the same time, raw material dynamics, formulation innovation, and regulatory scrutiny of manufacturing hygiene are reshaping competitive benchmarks. The sector’s concentration, with a small group of players holding the majority of industry revenue, suggests that scale, distribution relationships, and brand equity remain powerful moats. Yet the appearance of rapid product experimentation, especially around biodegradable and silica-based formats, indicates that incumbents cannot rely solely on legacy formulations or traditional retail placements.
Three friction points define the current transition. First, raw material price volatility and supply geography create margin exposure for both traditional clay-based and silica-based lines, forcing manufacturers to balance cost control with performance consistency. Second, consumer preference is bifurcating: one segment prioritizes low-cost, high-clumping mineral products, while another increasingly demands natural, low-dust, or flush-friendly alternatives. Third, operational integrity is becoming a strategic differentiator after a high-profile contamination incident involving a widely distributed litter brand, which triggered regulatory review and heightened retailer vigilance. These dynamics do not merely create risk; they establish the criteria by which leading players will be judged over the next several years.
Key Demand and Supply Drivers Reshaping the Category
Technological and formulation innovation is shifting from incremental improvements toward targeted performance solutions. The most notable advances cluster around rapid clumping, odor neutralization, low-dust engineering, and compatibility with automated cleaning systems. Recent product introductions have emphasized fast absorption, instant clumping behavior, and suitability for self-cleaning litter boxes, signaling that convenience is becoming a performance specification rather than a marketing phrase. Alongside this, odor-control strategies are incorporating activated carbon and mineral blends that address the household cleanliness expectations of urban consumers and multi-pet households. The practical implication is that product leadership increasingly depends on formulation precision and repeatability rather than on broad distribution alone.
Worldwide Prescription Cat Food Market
Regulatory and quality standards are also exerting a more direct influence on market behavior. Following a voluntary recall tied to rodent and avian contamination and insanitary storage conditions affecting Tidy Cats products distributed by Gold Star Distribution, Inc., the FDA elevated the recall classification for certain pet products to Class II after reviewing contamination hazards. This sequence matters beyond the immediate compliance event. It demonstrates that hygiene, traceability, and storage controls are becoming procurement concerns for retailers and distributors, especially in markets where consumer trust can shift quickly after a publicized safety issue. For manufacturers, the strategic response is not simply to meet baseline requirements but to embed operational hygiene into product handling, packaging integrity, and distribution protocols as a visible competitive attribute.
Demand-side behavior is changing through a combination of premiumization and value sensitivity. Cat owners are not a monolithic group: some remain highly price-conscious and gravitate toward familiar mineral-based options, while others willingly pay for natural, plant-based, or starch-derived formulations that align with environmental expectations and low-dust preferences. This split is reinforced by the growth of subscription and direct-to-consumer models in certain regions, which reward consistency, packaging convenience, and reliable replenishment. The result is a market where brand trust and usage experience can justify premium positioning even as mainstream segments continue to compete on cost-per-use and retail availability.
Worldwide Natural Cat Litter Products Market
Supply chain and cost structure dynamics add another layer of complexity. Clay remains the dominant raw material base, which means pricing exposure is tied to extraction, processing, freight, and energy costs. Silica-based options face different economics, including synthesis and material intensity considerations. At the same time, natural and biodegradable inputs depend on agricultural and processing supply chains that can vary in consistency, seasonality, and regional availability. Companies that can manage formulation flexibility, lock in dependable sourcing, and minimize waste in conversion processes are better positioned to protect margins through cycles of input inflation. For buyers and distributors, this reinforces the importance of supplier diversification and specification clarity when evaluating long-term contracts.
Competitive Positioning and the Emerging Landscape
The competitive field is anchored by a concentrated group of manufacturers with strong mineral-based capabilities and well-known retail brands, alongside a widening set of regional and formulation-focused producers. TOLSA SA and Laviosa Chimica Mineraria SpA represent established bentonite and mineral-based production profiles with international reach. Oil DRI Corporation of America specializes in absorbent material formulations, while InterSand operates as a North American bentonite and cat litter producer and exporter. On the branded side, The Clorox Company and its Fresh Step portfolio maintain broad retail distribution, and Dr. Elsey's competes in the premium clumping and natural segments. These players benefit from scale, shelf relationships, and formulation familiarity, but their strategic challenge is to sustain relevance as product experimentation and retail assortment complexity increase.
A parallel competitive track is emerging around natural, biodegradable, and plant-based options. Brands such as Naturally Fresh, World's Best Cat Litter, and Kent Corporation illustrate the positioning of pine and plant-based formulations, while manufacturers like Shandong Aiyu Pet Products, Changzhou Sanmei Pet Products, and Anhui Hengjie Group reflect a broader Asian production base spanning cassava, tofu, zeolite, and mixed formats. Several of these companies have expanded visibility through trade activity and product catalog updates. For example, recent exhibition presentations highlighted pure tofu cat litter with natural soybean residue, strong clumping, odor locking with activated carbon, and low dust, while other launches emphasized rapid absorption, instant clumping, and suitability for automatic litter boxes. This activity signals that Asia-based producers are not only competing on cost but increasingly on specification performance and OEM customization capability.
The strategic differentiation among leaders is becoming less about category ownership and more about segmentation mastery. Incumbents with strong mineral-based positions can defend share through consistent performance, packaging innovation, and retail execution. Premium natural brands can build loyalty through perceived safety, environmental alignment, and user experience. Meanwhile, OEM-oriented manufacturers with flexible formulation capabilities can serve private-label programs, regional distributors, and product-development partners seeking to move quickly into biodegradable or mixed-material formats. This creates a landscape where M&A, joint supply arrangements, and brand acquisitions are plausible tools for players seeking to fill portfolio gaps or enter new geographic channels.
Market structure is likely to evolve through both consolidation and fragmentation. Consolidation may occur as larger consumer goods and distribution players acquire regional brands or integrate upstream sourcing to secure input stability. Fragmentation may continue as new entrants target specialized needs, including low-dust formulations, flush-compatible options, and automatic litter box compatibility. The Company is also likely to see increased importance of brand trust and retail compliance, especially after recent contamination-related scrutiny. In practice, this means that competitive advantage will be determined by a combination of formulation consistency, operational discipline, distribution access, and the ability to communicate product benefits in ways that resonate with increasingly discerning buyers.
PW Consulting
Forward-Looking Trends and Commercial Implications
One of the most important forward-looking trends is the growing role of performance-specific formulations in product selection. Not all litter is evaluated primarily on price anymore; automatic cleaning devices, odor sensitivity, dust exposure, and tracking behavior increasingly influence purchase decisions. Over the next three to five years, this should drive further refinement in clumping speed, absorption capacity, and low-dust manufacturing controls. The commercial implication is that product specifications will become more consequential in procurement decisions, and successful players will need to validate performance claims with repeatable production quality rather than relying on broad category messaging.
A second trend is the continued expansion of natural and biodegradable alternatives as a meaningful, though still minority, share of activity. As plant-based, starch-based, and tofu-derived options gain visibility, the strategic question is not whether they will replace conventional mineral products, but where they will hold strongest appeal and how they can be produced consistently at scale. Distribution will matter as much as formulation, because eco-oriented products often require clearer consumer education, distinct shelf positioning, and reliable replenishment cycles. Companies that can stabilize input supply, maintain clumping and odor-control performance, and communicate environmental benefits without sacrificing usability are likely to capture the most durable demand within this segment.
A third trend concerns supply chain integrity and regulatory responsiveness becoming more visible in brand credibility. The recent recall and subsequent FDA classification update have reinforced that hygiene, storage, and distribution conditions are not back-office concerns; they are customer-facing trust signals. Over the coming years, this is likely to translate into tighter audit expectations, stronger quality assurance requirements from retailers, and greater emphasis on traceability in sourcing and logistics. The upside is that disciplined operators can use compliance and safety assurances as differentiators, especially in markets where consumers and retailers are especially sensitive to product cleanliness and brand reliability.
These trends carry both opportunity and uncertainty. On the opportunity side, there is room for manufacturers to capture value through formulation leadership, private-label partnerships, premiumization, and regional expansion into channels that reward consistency and freshness of product design. There is also scope for investors to identify companies with defensible sourcing, scalable OEM capabilities, or brands positioned in high-trust segments. On the risk side, raw material volatility, consumer skepticism after safety incidents, and fragmentation of retail channels could pressure margins and slow share shifts. Demand may also evolve unevenly across regions, meaning that growth assumptions need to be tested against local pet ownership patterns, retail structure, and price sensitivity.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align formulation roadmaps with the ways consumers now evaluate performance. This means investing in clumping reliability, odor control, dust reduction, and compatibility with automated litter systems, while also building supply flexibility across mineral, silica, and natural inputs. Equally important is operational hygiene and traceability, which should be treated as brand assets rather than minimum compliance steps. Companies that can combine specification leadership with dependable production quality will be better positioned to defend premium pricing and secure retailer confidence.
For investors, the most useful discipline is to evaluate competitive positions through the lens of margin resilience and channel access rather than headline category growth alone. Opportunities are likely strongest where companies demonstrate scalable sourcing, formulation versatility, or brand strength in premium or eco-oriented segments. At the same time, diligence should account for input exposure, regulatory sensitivity, and the risk that safety incidents can quickly alter retail placement and consumer trust. Portfolio selection should favor operators that can sustain product consistency and adapt to shifting material economics.
For procurement and distribution leaders, the strategic focus should be on supplier qualification, specification clarity, and contingency planning. Diversifying across mineral and natural-based sources can reduce exposure to single-material volatility, while explicit performance requirements can reduce the risk of assortment inconsistencies. Given the elevated attention to storage and contamination risks, procurement teams should also strengthen audit expectations and handling standards across the distribution chain. In practice, this means treating litter procurement as a quality and reliability decision as much as a cost decision.
For decision-makers seeking to move from directional insight to actionable planning, the market’s segmentation details, regional demand patterns, formulation economics, and competitive moves warrant closer examination. Many of the richest strategic choices—whether in product development, channel expansion, supplier selection, or capital allocation—depend on granular data that cannot be fully captured in a high-level review. Access to a more detailed market study can help translate these trends into specific scenarios, segment-level demand estimates, and tailored recommendations aligned with each organization’s position.
For detailed analysis of this topic, please visit the official page: Cat Litter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


