



Educational Toys Market: Why 8.47% CAGR and STEM Demand Redefine Growth Strategy

Navigating the Educational Toys Market: Strategic Trends and Opportunities Through 2032
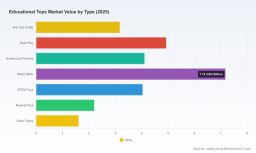
The educational toys market has transitioned from a niche segment within the broader play industry to a strategic battleground where learning outcomes, developmental science, and consumer purchasing behavior intersect. Market sizing data places the sector at approximately 24.85 billion USD in 2024, reaching an estimated 27.24 billion USD in 2025, with a projected trajectory toward 48.23 billion USD by 2032. The compound annual growth rate across the 2026–2032 forecast window sits at 8.47 percent, signaling a steady but accelerating expansion that outpaces many traditional toy categories. This growth is not merely a function of population expansion; it reflects a structural shift in how parents, educators, and institutions define the value of play. Toys are increasingly evaluated through the lens of skill development, cognitive engagement, and alignment with early learning frameworks rather than pure entertainment appeal. For commercial players, this reframing creates both opportunity and complexity, as the market rewards differentiation and penalizes commoditization.
Several structural inflection points are reshaping how the educational toys sector evolves. First, the convergence of digital interactivity and tactile play has blurred category boundaries. Products that once fell neatly into arts, games, or motor skills categories now routinely blend physical manipulation with screen-informed feedback or app-supported scaffolding. This hybridization challenges traditional product segmentation and forces companies to reconsider how they position, bundle, and distribute offerings. Second, regulatory tightening around safety and traceability is introducing new compliance costs and design constraints. Rules targeting material hazards, electronic component certifications, and digital product documentation are reshaping development timelines and increasing the cost of non-compliance. Third, the market is maturing in a way that makes pure price competition less viable for long-term value creation. Retail channels and procurement teams are paying closer attention to learning efficacy, developmental appropriateness, and brand reputation, which elevates the importance of credible educational positioning over generic toy attributes.
Key Drivers Shaping Market Direction
Technology Innovation and the Hybrid Play Opportunity
Technology remains one of the most decisive forces shaping the educational toys landscape. Advances in low-cost sensors, durable electronic components, and interactive software have enabled manufacturers to embed guided learning mechanics into physical products without sacrificing the hands-on engagement that defines high-quality play. The result is a growing class of products that combine construction, movement, music, or puzzle-solving with feedback loops that adapt to a child's pace or learning goals. Recent product activity illustrates this direction. In January 2026, LEGO Education launched new STEM sets for children aged seven and above designed to encourage curiosity, experimentation, and scientific discovery. Earlier, in October 2025, STEMPlay Labs introduced Wonder Briks and PictoMath, patent-pending construction bricks and math tools aimed at embedding STEM learning into tactile play. May 2025 saw LeapFrog showcase updated educational concepts at Toy Fair, including the Strum & Count Wooden Guitar, signaling renewed interest in combining music and early numeracy through physical interaction. More recently, in May 2026, Smart Kids Planet expanded its age-specific STEM and educational lines for children ages 1 through 13, reflecting a broader industry push to align product complexity with developmental stages. These moves point toward a market where interactivity and educational scaffolding are increasingly expected, not optional.
Regulatory and Compliance Shifts as Strategic Factors
Regulatory change is no longer a back-office concern for educational toy companies; it is a strategic variable affecting product roadmaps, sourcing decisions, and market entry timing. In December 2025, the U.S. Consumer Product Safety Commission published its final rule on the Safety Standard for Toys, with specific requirements for water beads, effective March 12, 2026. The rule codifies requirements directly into 16 CFR Part 1250 rather than amending ASTM F963, creating a more prescriptive compliance pathway. Around the same time, the European Union published Toy Safety Regulation 2025/2509 on December 12, 2025, entering into force on January 1, 2026 and applying fully on August 1, 2030. Notably, the new EU framework introduces a digital product passport requirement for all toys, enhancing traceability and compliance documentation across the product lifecycle. These developments matter commercially because they raise the bar for product documentation, material disclosure, and hazard testing, especially for electronics, small components, and age-differentiated lines. Companies that treat compliance as a design input rather than a late-stage checkpoint are better positioned to reduce rework, protect brand reputation, and avoid recalls or enforcement actions.
Demand-Side Shifts in Parent and Educator Expectations
Consumer behavior is evolving in ways that increase the value of products perceived as developmentally useful. Parents and caregivers are more aware of early cognitive, motor, and social-emotional milestones, and they often evaluate toys as tools that support those outcomes. At the same time, educators and institutional buyers continue to look for resources that complement classroom objectives, especially in science, mathematics, and problem-solving. This dual pull has expanded the relevance of products that bridge home play and structured learning. It also raises expectations for age differentiation, clear instructional support, and durable design. Demand is less about novelty alone and more about sustained engagement that can justify repeated use and recommendation within parent networks, schools, and care settings. For manufacturers, this means that educational credibility, not just packaging claims, increasingly influences purchase decisions and repurchase behavior.
Supply Chain and Cost Structure Pressures
Cost dynamics continue to shape commercial strategy, particularly for products that combine electronics, plastics, wood, and packaging. Material price variability, component sourcing, and logistics overhead affect margin resilience, especially for companies managing broad SKU portfolios or launching multiple age-specific variants. At the same time, regulatory requirements can increase testing, documentation, and quality assurance expenses. The net effect is that cost efficiency must be pursued without eroding the tactile and learning qualities that distinguish educational toys from generic alternatives. Companies that standardize platforms, modularize features, or streamline compliance documentation can protect margins while still offering differentiated products. This is especially relevant for category leaders with global footprints, where scale advantages must be paired with disciplined product architecture to avoid complexity-driven cost creep.
PW Consulting Automotive & Machinery Research Center
Competitive Landscape and Differentiating Playbooks
The competitive field in educational toys is broad and varied, including large multinational toy companies, electronics specialists, construction-focused brands, and niche learning tool providers. Several established players define much of the category's direction through scale, brand recognition, and educational positioning. Mattel continues to offer a wide range of educational toys including construction sets, STEM learning products, and interactive play items, leveraging broad brand reach and distribution. LEGO System A/S and The LEGO Group remain closely associated with construction-based educational toys and STEM sets designed for scientific discovery and creativity, with products spanning early builders and older age groups. Hasbro contributes educational games, role-playing sets, and STEM-oriented toys for skill development, often bridging play patterns with learning outcomes. VTech manufactures electronic learning toys, interactive tablets, and educational software for early childhood development, while LeapFrog focuses on interactive electronic learning toys and books that combine technology with early education. Ravensburger offers wooden puzzles, board games, and STEM building sets for cognitive development, and Melissa & Doug specializes in wooden educational toys, puzzles, and open-ended play sets for preschoolers. Tomy develops educational construction toys, robotics, and STEM learning products, while Spin Master provides STEM and interactive educational toys, including licensed educational lines. MindWare emphasizes hands-on learning tools and manipulatives for science, math, and critical thinking. JAKKS Pacific manufactures educational electronic toys and interactive STEM products, and Osmo offers interactive tablet-based educational games and learning kits for ages 3 through 11.
These companies are not competing on the same dimension. Some win through brand equity, platform scale, and retail presence. Others differentiate through age-specific developmental framing, hybrid digital-physical experiences, or specialized learning content. The strategic advantage increasingly belongs to players that can connect product design to clear developmental outcomes while maintaining manufacturing discipline and compliance readiness. Recent activity shows how this differentiation is emerging in practice. The January 2026 STEM sets from LEGO Education target scientific curiosity for older children, while the 2026 expansion by Smart Kids Planet shows a deliberate push to cover ages 1 through 13 with age-appropriate STEM and educational lines. Meanwhile, the March 2026 recall by ZMC Group involving multiple light-up toys due to battery ingestion hazards serves as a reminder that safety failures can quickly undermine brand trust and commercial momentum. In a market where confidence in educational claims and product safety both matter, reputation management is inseparable from product strategy.
Educational Furniture Market
The structure of the competitive field appears to be moving along two simultaneous paths. On one hand, consolidation pressure exists where scale players can absorb compliance costs, extend distribution, and cross-sell across categories. On the other hand, fragmentation remains viable for specialists offering targeted age ranges, pedagogical framing, or unique material and play experiences. New entrants and smaller innovators are actively exploring patent-protected mechanisms, tablet-integrated kits, and construction-based math and science tools, suggesting that innovation is not confined to the largest players. For commercial leaders, the key strategic question is whether to compete through breadth and distribution, through deep category specialization, or through hybrid design that combines tactile play with guided learning features. Each path carries different margin profiles, compliance burdens, and go-to-market requirements.
Forward-Looking Trends and Commercial Implications
Looking across current market dynamics and recent product and regulatory activity, a few trends are likely to define the next three to five years. First, hybrid learning play will continue to expand as a mainstream expectation. Products that integrate construction, puzzle-solving, motor skill development, or musical interaction with structured learning feedback will be better positioned to capture demand from both home and school-adjacent buyers. The commercial opportunity lies in designing modular learning experiences that can scale across age groups without becoming overly complex or costly to manufacture and document.
Second, age-tiered product architecture will become more important as parents and educators seek developmentally appropriate options. The move toward lines that span early childhood through pre-teen years, as reflected in recent expansions, indicates that buyers value progression paths rather than one-off products. Companies that can map product complexity, safety requirements, and learning objectives to clear age brackets are likely to gain shelf and channel relevance. The risk is portfolio bloat: too many overlapping SKUs can dilute focus, increase compliance burden, and complicate inventory management.
Third, compliance and traceability will increasingly shape competitive readiness. The digital product passport direction in the EU and the tighter U.S. rules on specific hazards demonstrate that documentation and material control are becoming part of product competitiveness. Firms that invest early in traceability systems, standardized testing protocols, and clear hazard controls will have stronger launch velocity and lower exposure to enforcement or recall risk. The uncertainty here lies in how quickly full compliance timelines are enforced across regions and how retailers and procurement teams integrate these requirements into vendor evaluation.
Strategic Recommendations for Decision Makers
For manufacturers, the priority is to treat educational value and compliance as integrated design constraints rather than separate workstreams. Build product platforms that can support multiple learning objectives and age ranges without inflating SKU complexity. Where electronics or small components are involved, design hazard controls and documentation into the development process from the outset. Consider whether the brand should compete through breadth, specialized age segments, or hybrid interactive play, and ensure that product architecture, sourcing, and distribution are aligned with that choice.
For investors, the market's 8.47 percent CAGR and projected scale expansion toward the end of the decade suggest durable growth, but value capture will depend on execution quality. The strongest opportunities are likely in companies that can demonstrate clear developmental positioning, disciplined compliance readiness, and efficient product platforms. Due diligence should evaluate not only revenue momentum but also portfolio complexity, regulation exposure, safety track record, and the credibility of educational claims. Companies with repeated safety or compliance issues may face disproportionate reputational and commercial costs in a market where trust is a differentiating asset.
Education Software Market
For procurement teams and retail buyers, the emphasis should be on differentiating educational toys through learning support, age appropriateness, and safety documentation rather than price alone. Products that offer clear developmental progression and dependable compliance records are better suited to long-term shelf performance and parent trust. Evaluate supplier capabilities for traceability, testing, and post-launch support, since these factors increasingly influence channel and consumer confidence. Align category decisions with the expectation that educational toys are judged on sustained engagement and credible learning benefits, not short-lived novelty.
For leaders seeking to move faster with more granular visibility, detailed segmentation data, regional performance, and company-specific benchmarking can materially improve planning confidence. The broader trends are clear, but the execution advantages often come from subsegment insight: which age ranges are expanding most rapidly, where hybrid-versus-tactile trade-offs are shifting, and how compliance costs vary by product design and region. A complete research report can provide that depth, including detailed market splits, competitive positioning maps, and scenario-ready forecasts to support product, investment, and purchasing decisions.
For detailed analysis of this topic, please visit the official page: Educational Toys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


