



IC Substrate Market: Why 6.63% CAGR and Asia Pacific Dominance Reshape 2026 Strategy

Navigating the IC-Substrate Market: Strategic Trends and Commercial Opportunities Through 2032
The integrated circuit (IC) substrate market has entered a decisive growth phase, driven by structural shifts in semiconductor packaging, escalating compute demands, and regional industrial policies. With the market valued at approximately USD 10 billion in 2025 and projected to expand at a 6.63 percent compound annual growth rate (CAGR) through 2032, the sector is no longer merely a supporting component in the electronics value chain. It has become a strategic bottleneck and a competitive differentiator for high-performance computing, automotive electrification, and next-generation mobile architectures. The trajectory from 2020 through 2032 reveals a market that has more than doubled in scale, but growth alone does not guarantee profitability or supply stability. Decision-makers must understand where value is concentrating, which constraints are structural versus cyclical, and how leading players are repositioning their capabilities to capture premium segments.
Market Landscape and Core Challenges
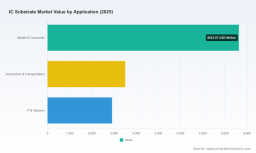
The IC-substrate industry is characterized by a concentrated competitive structure and a clear shift toward advanced packaging formats. The top three players control a majority of revenue, and the top five collectively account for a significant share, indicating high barriers to entry and capital-intensive scaling requirements. This concentration reflects the technical complexity of advanced substrates, the long qualification cycles with semiconductor manufacturers, and the need for sustained investment in specialized production lines. While regional demand patterns show Asia Pacific as the dominant volume center, other regions are actively building localized capacity to reduce supply chain dependencies and align with policy incentives. The type mix increasingly favors flip-chip ball grid array (FC-BGA) and flip-chip chip scale package (FC-CSP) configurations, reflecting the industry's migration toward higher interconnect density, shorter signal paths, and thermal efficiency. Application demand is equally diversified, with mobile and consumer electronics sustaining baseline volume, while automotive and IT/telecom segments accelerate their pull for higher-performing substrate solutions.
Despite strong top-line growth, the market faces several structural challenges that will shape competitive outcomes over the next five years.
1. Raw material constraints are reshaping cost structures and supply reliability. Fiberglass and base resin shortages have persisted into 2026, creating upward pressure on ABF substrate film pricing and tightening availability for AI-related production. Ajinomoto Fine-Techno raised ABF substrate film prices by approximately 30 percent due to critical base resin supply constraints, signaling that input cost pressures are not transient. For substrate manufacturers, this translates into margin compression risk, pricing renegotiation complexity, and the need to secure long-term material agreements. For downstream customers, it means qualification lead times and supply continuity must be managed with greater urgency.
2. Capacity expansion is racing against demand elasticity and qualification timelines. Multiple leading manufacturers are executing large-scale capital programs to expand advanced substrate capacity, yet ramp-up schedules, yield stabilization, and customer qualification processes can delay the realization of revenue. The market is effectively in a phase where supply additions are necessary but not instantly absorbable at premium economics. Companies that expand without aligned demand visibility or without differentiated technology risk underutilization, while those that can secure early design wins and long-term supply agreements are positioned to monetize new capacity more effectively.
3. Technology transitions are creating segmentation between commodity and premium tiers. The industry is moving toward glass-core substrates, multifunctional core technologies, and low-loss organic laminates for high-frequency and advanced thermal requirements. This transition is not uniform across all product categories. Some segments will continue to compete on cost and volume, while others will increasingly be defined by performance, reliability, and integration complexity. Manufacturers that cannot navigate this bifurcation may find themselves trapped in price-sensitive segments with limited differentiation, while those that advance into higher-value technology tiers can capture stronger pricing power and tighter customer relationships.
Key Demand Drivers and Structural Shifts
The IC-substrate market is being reshaped by interconnected technology, policy, demand-side, and supply chain forces. Understanding how these drivers interact is essential for anticipating where growth will be most durable and where vulnerabilities may emerge.
Technology innovation is elevating substrates from passive interposers to performance-defining components. Advanced packaging requirements for AI servers and high-performance computing are pushing substrate design toward higher layer counts, finer pitch routing, and improved electrical and thermal performance. Glass-core substrates and advanced ABF variants are moving from research and development into industrial deployment, enabling better signal integrity and thermal management for next-generation chips. This shift increases the strategic importance of substrate engineering capabilities, as material selection, dielectric properties, and mechanical stability now directly influence system-level performance. Companies investing in proprietary core technologies, low-loss laminates, and integrated multifunctional designs are building moats that are difficult for followers to replicate quickly.
Policy and regulatory environments are accelerating regional capacity build-out. Industrial policy is no longer a background factor; it is actively shaping where capacity is added and who can access funding. Support mechanisms have enabled major substrate projects in multiple regions, including flip-chip substrate fabs in the United States and significant expansions in Europe. These initiatives are intended to strengthen supply chain resilience and reduce concentration risk, but they also create a more fragmented geographic footprint. For manufacturers, policy-aligned investments can lower capital barriers and improve long-term demand visibility. For buyers, this may increase sourcing options over time, but near-term supply will still depend heavily on the pace of fab commissioning and qualification.
Demand-side behavior is shifting from volume-driven consumption to performance- and reliability-driven selection. End-market adoption patterns are reinforcing the need for higher-performing substrates. AI server deployments are creating demand that is outstripping existing production limits in certain high-end categories, while automotive and transportation applications require substrates that can meet stringent reliability, thermal, and longevity requirements. Mobile and consumer segments remain important volume drivers, but they increasingly demand compact form factors and efficient thermal solutions rather than simple cost optimization. The broader implication is that demand is becoming more segmented: some volumes remain price-sensitive, while strategic applications are willing to pay for performance assurance, supply stability, and long-term partnership alignment.
Supply chain and cost structure dynamics are reinforcing the premiumization trend. Persistent raw material constraints, combined with the capital intensity of advanced substrate production, are altering the economics of the market. Fiberglass shortages and base resin supply limitations are tightening ABF substrate availability, prompting price adjustments for premium products. At the same time, capacity expansions are concentrated among players with the financial and operational capacity to commit to multi-year investment programs. This dynamic favors companies that can secure material supply, manage yield during ramp-up, and align production with qualified high-value programs. It also increases the importance of vertical coordination, supplier diversification, and strategic inventory planning across the value chain.
Competitive Landscape and Leading Strategies
The competitive environment in the IC-substrate market is defined by a small group of established players pursuing differentiated technology strategies, regional expansion, and selective pricing actions to protect margins in premium segments. Rather than competing purely on volume, leading firms are positioning around performance categories, customer qualification depth, and capacity alignment with high-growth applications.
Several companies illustrate the strategic directions now shaping the market. Japanese and Korean producers are expanding high-performance IC package substrate capacity to serve AI server and automotive demand, often with multi-year capital programs and site-specific ramp plans. Taiwan-based manufacturers are advancing advanced flip-chip substrates, including ABF and glass-core variants, while adjusting pricing in premium categories to reflect material costs and constrained supply. European players are pushing glass-core and multifunctional core technologies into industrial deployment for AI, high-performance computing, and photonics applications, supported by regional expansion plans. Across these profiles, a common theme is the pursuit of technology leadership in advanced substrate formats combined with capacity investments that target confirmed or highly probable demand pipelines.
The strategic positioning of leading players can be understood through several differentiating dimensions:
- Technology specificity. Some leaders focus on high-end server and AI packaging substrates, including ABF variants and glass-core designs, while others emphasize low-loss organic laminates for high-frequency and automotive applications. This specialization allows firms to align their process capabilities with the most demanding requirements and to reduce direct head-to-head competition in commodity segments.
- Capacity timing and scale. Large capital commitments are being deployed to expand production for FC-BGA and advanced flip-chip substrates. The differentiator is not simply building capacity, but aligning it with confirmed demand, managing ramp-up risk, and securing the material inputs needed to sustain output.
- Customer integration and qualification depth. Advanced substrates require close collaboration with semiconductor and system manufacturers. Companies that can manage long qualification cycles, support design-in decisions early, and maintain reliability across volume production are more likely to secure multi-year supply relationships.
- Margin defense in constrained markets. In environments where raw material availability is tight, some leaders are adjusting pricing for premium substrates to offset cost pressure and capacity limitations. This reflects a shift toward value-based pricing in segments where performance and supply continuity carry strategic importance.
Recent developments highlight how these strategies are being executed in practice. One major Japanese substrate producer approved a substantial multi-year capital investment to expand high-performance IC package substrates at plants in Gifu Prefecture, with mass production ramping from fiscal 2027 to meet AI server demand. In the United States, support from CHIPS Act funding enabled a flip-chip substrate fab targeting significant monthly panel output by late 2027, illustrating how policy alignment can accelerate regional capacity deployment. A European manufacturer advanced glass-core substrate technology from research to industrial deployment for AI, high-performance computing, and photonics, while also expanding capacity in China and Europe to serve high-end IC substrate demand. Another leading Asian producer approved capital expenditure exceeding KRW 1 trillion for high-end FC-BGA manufacturing after AI server substrate demand exceeded production limits by more than 50 percent, underscoring the intensity of demand pull in advanced categories. Meanwhile, a Taiwan-based supplier raised prices for premium ABF substrates to offset raw material costs and capacity constraints amid fiberglass shortages, reflecting the market's shift toward pricing discipline in high-value segments.
Ceramic Substrate Market
The competitive landscape is evolving along several trajectories. Consolidation is likely to continue among players that can finance advanced capacity and sustain technology development, while smaller or less differentiated entrants may struggle to secure qualified positions in premium segments. At the same time, regional capacity additions are creating a more diversified geographic supply base, which may reduce single-point dependencies over time. New entry remains difficult because of the combination of capital requirements, qualification lead times, and material supply complexity, but targeted partnerships, technology licensing, and policy-supported projects could enable selective expansion by well-positioned participants. The broader trend is not simply toward concentration or fragmentation, but toward a layered market in which premium technology tiers are tightly held by a few capable suppliers, while lower-tier segments remain more competitive and cost-driven.
PW Consulting Information & Electronics Research Center
Future Outlook: Key Trends and Commercial Implications
Looking ahead to the 2026-2032 period, several trends are likely to define the IC-substrate market's evolution and shape commercial opportunities for stakeholders across the value chain.
Advanced substrate technologies will become mainstream requirements rather than niche differentiators. Glass-core substrates, multifunctional core designs, and low-loss laminates are expected to move from early deployment into broader production as AI, high-performance computing, and high-frequency applications scale. This transition will increase the importance of material science expertise, process control, and thermal-electrical co-optimization. For manufacturers, the opportunity lies in capturing design-ins early and building repeatable processes that can support volume production without compromising performance. For downstream innovators, advanced substrates will enable tighter integration, higher compute density, and improved reliability, but only if supply can be secured with sufficient lead time and consistent quality.
Capacity expansion will remain a defining strategic variable, but utilization and demand alignment will separate winners from casualties. The next several years will see continued investment in high-end substrate lines, particularly for FC-BGA and advanced flip-chip formats. However, the commercial outcome will depend on whether new capacity is matched to qualified demand, stabilized quickly, and supported by reliable material inputs. Overbuilding in segments with uncertain demand could lead to pricing pressure and underutilization, while tightly coordinated expansion tied to long-term supply agreements can reinforce pricing power and customer lock-in. This dynamic favors stakeholders that treat capacity planning as a demand-signal discipline rather than a standalone capital decision.
Regionalization and policy-driven supply chains will reshape sourcing strategies. Industrial policy support is encouraging substrate production in multiple regions, which may improve resilience and create new sourcing options over time. Yet near-term supply will still be constrained by ramp-up schedules and qualification requirements. Buyers will need to balance the benefits of regional diversification against the realities of limited immediate capacity and the technical constraints of qualifying alternative suppliers. For manufacturers, policy-aligned programs can provide capital support and demand visibility, but they also require disciplined execution to convert funding and announcements into commercially viable production.
These trends carry embedded risks and uncertainties. Material shortages may persist or ease depending on upstream capacity and resin supply dynamics, making cost planning and supply continuity highly sensitive to external conditions. Demand for advanced substrates could evolve faster than expected in some application areas, while other segments may moderate if end-market cycles shift. Technology transitions may also create temporary supply gaps as manufacturers retool or qualify new processes. Stakeholders should therefore plan for both upside demand scenarios and disruption scenarios, rather than assuming linear growth.
IC Substrate Market
Strategic Implications for Decision-Makers
The IC-substrate market offers clear opportunities, but capturing them requires precise positioning, disciplined supply planning, and early engagement with technology roadmaps. The following recommendations are designed to help different stakeholder groups translate market dynamics into actionable strategy.
For Substrate Manufacturers and Capacity Planners
Prioritize technology differentiation in premium segments where performance, reliability, and supply continuity justify stronger pricing. Expand capacity with explicit demand alignment, securing material supply agreements and qualification pathways before scaling output. Where raw material constraints are structural, diversify input sources, lock in long-term contracts, and build buffer strategies for critical materials. Avoid undifferentiated capacity additions in price-sensitive tiers unless supported by clear cost advantages or regional policy benefits. The most resilient strategies will combine technology leadership with disciplined execution and close customer collaboration.
For Investors and Strategic Capital Allocators
Focus on players with credible pathways to high-value segments, demonstrated ability to manage material and capacity constraints, and visible demand anchors in AI, automotive, or high-performance computing. Evaluate not only announced capacity but also ramp readiness, qualification momentum, and material supply resilience. The market's concentration and technology intensity mean that financial strength alone is insufficient; operational execution and customer integration are equally important. Investors should also monitor regional policy-supported projects for execution risk, since funding announcements do not automatically translate into timely, profitable production.
For Procurement Leaders and End-Market Buyers
Treat advanced substrates as strategic procurement categories rather than commoditized inputs. Early design-in engagement, multi-source qualification where feasible, and long-term supply coordination can reduce exposure to material shortages and capacity bottlenecks. Where performance requirements are high, consider the trade-offs between cost optimization and supply assurance, especially in AI server, automotive, and high-frequency applications. Building transparency into supplier roadmaps, material availability, and ramp timelines will help align internal product planning with realistic supply expectations.
The IC-substrate market is entering a phase where technology, policy, material constraints, and demand dynamics intersect in ways that reward foresight and disciplined execution. Stakeholders that understand where value is concentrating, how premium segments are being redefined, and which supply risks are structural will be better positioned to act before competitive positioning solidifies.
This analysis is intended as a strategic overview of market direction and commercial logic. For decision-makers who need deeper segmentation detail, scenario-based demand modeling, company-level benchmarking, and tailored recommendations aligned to specific product categories or regional sourcing strategies, a more comprehensive research package can provide the granularity required for execution planning. Access to full segmentation data, capacity ramp timelines, and competitive tracking can help translate these market-level insights into precise operational and investment decisions.
For detailed analysis of this topic, please visit the official page: IC-Substrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


