



Isophthalonitrile Market 2026: 5.5% CAGR and the Real Drivers Shaping Demand to 2032

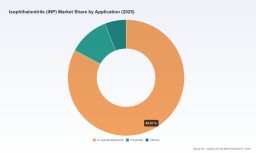
Isophthalonitrile (INP) Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The Isophthalonitrile (INP) market has demonstrated steady expansion over the past half-decade, evolving from a specialized chemical intermediate into a strategically significant segment tied to advanced materials and agrochemical supply chains. Valued at approximately $163.15 million in 2020, the market grew to $215.0 million by 2025, reflecting a compound annual growth rate of 5.5 percent. Projections through 2032 indicate the market will surpass $311 million, driven by accelerating demand in high-performance polymers, pharmaceutical intermediates, and specialty crop protection formulations. While the trajectory appears consistent, the underlying dynamics reveal a market at an inflection point, where growth is no longer guaranteed by volume alone but increasingly dependent on technological adaptation, regulatory navigation, and supply chain resilience.
Several structural challenges are shaping how market participants operate today. First, the concentration of supply among a handful of established producers creates both stability and vulnerability. With the top three and top five players collectively controlling the majority of global output, pricing power and capacity allocation are heavily influenced by strategic decisions from a small group of manufacturers. This concentration limits the ability of downstream buyers to negotiate favorable terms during periods of tight supply, while simultaneously raising the barrier for new entrants seeking to achieve meaningful scale.
Second, raw material price volatility continues to disrupt cost forecasting and margin stability. The production of INP relies on specialized precursor chemistry, and fluctuations in petrochemical feedstocks, energy costs, and catalytic materials introduce unpredictable swings in manufacturing expenses. These swings are particularly acute for producers operating in regions with less diversified supply networks or weaker hedging capabilities, forcing them to balance competitive pricing against the risk of margin compression.
Third, the regulatory environment is becoming increasingly complex, especially for producers and exporters navigating cross-border material controls. Recent export restrictions on critical semiconductor-related materials in major Asian markets have introduced uncertainty into broader chemical supply chains, prompting buyers and manufacturers alike to reassess sourcing strategies, inventory buffers, and alternative formulation pathways. These overlapping pressures mean that simply tracking market size is insufficient; understanding how capacity, regulation, and input costs interact is essential for making informed commercial decisions.
Worldwide 4-Brombenzonitrile Market
Key Drivers Shaping Market Trajectories
Technological Innovation and Process Optimization
Advancements in synthetic chemistry and manufacturing efficiency are reshaping the value proposition of INP across multiple end-use sectors. Improved catalytic processes and purification techniques have enabled producers to achieve higher consistency at elevated purity levels, which matters significantly for applications in synthetic resins and electronic-grade materials where impurity tolerances are extremely tight. As downstream manufacturers demand more reliable specifications, suppliers that invest in process control, analytical quality assurance, and continuous improvement are positioned to capture premium segments rather than competing solely on price.
Beyond purification, innovation is also expanding the practical utility of INP in higher-margin applications. Research into advanced polymer architectures and specialty intermediates has reinforced the role of INP as a foundational building block for m-xylylenediamine and related derivatives, which in turn support high-performance engineering plastics and coatings. The convergence of material science requirements and chemical manufacturing capability is creating a positive feedback loop: as end-use applications become more demanding, the incentive to invest in better production methods grows, and those investments in turn unlock new commercial pathways.
Policy and Regulatory Evolution
The regulatory landscape is no longer a background condition; it is a direct determinant of market access, sourcing flexibility, and long-term planning. Export controls and material security policies in several key production regions have already begun influencing how chemical manufacturers structure their supply networks. While these measures are often framed around critical minerals and compound semiconductors, their ripple effects extend into adjacent chemical markets where reliability of supply, traceability, and compliance documentation are increasingly scrutinized.
For INP market participants, this means that regulatory readiness is becoming a competitive attribute. Companies that proactively align with evolving export compliance requirements, maintain transparent documentation practices, and diversify their customer base across jurisdictions are better positioned to avoid disruption. At the same time, regulatory divergence between regions can create uneven playing fields, where producers in one jurisdiction face different cost structures or approval timelines than those in another. Strategic leaders are treating regulatory forecasting as part of their core operational planning rather than a reactive compliance exercise.
Shifting Demand-Side Behavior
Demand for INP is being shaped less by a single end market and more by a combination of performance requirements across diverse applications. In the agrochemical sector, the push for more targeted and efficient crop protection solutions continues to support steady consumption of specialty intermediates. At the same time, pharmaceutical and fine chemical manufacturers are increasingly looking for reliable, high-specification inputs that can support complex synthesis routes without introducing variability. These demand-side shifts favor suppliers that can offer consistent quality, technical support, and flexible order structures.
There is also a growing preference among downstream buyers for supply partners that can provide visibility into capacity, lead times, and contingency plans. This is not simply a cost consideration; it is a risk-management decision. As global supply chains have become more sensitive to geopolitical tension, logistics disruption, and energy volatility, procurement teams are placing greater weight on reliability and strategic alignment. Suppliers that can demonstrate operational resilience and transparent communication are gaining preferential access to long-term contracts and repeat business.
Supply Chain Restructuring and Cost Dynamics
The cost structure of INP production is being reshaped by broader changes in global manufacturing geography and logistics. Some producers are consolidating operations to achieve economies of scale, while others are expanding or relocating capacity to balance proximity to key customers with access to raw materials and energy. These decisions are not purely about production cost; they are about reducing exposure to transport bottlenecks, aligning with regional regulatory frameworks, and strengthening relationships with end markets.
Simultaneously, the market is witnessing a gradual recalibration of inventory strategies. Buyers that once prioritized minimal inventory and just-in-time procurement are increasingly maintaining strategic buffers for critical intermediates. This shift changes the rhythm of demand signals reaching producers and encourages capacity planning that accounts for both baseline consumption and surge scenarios. The companies that can interpret these signals accurately and adjust production schedules accordingly are gaining an advantage in both service levels and cost efficiency.
Competitive Landscape and Leading Strategies
The competitive environment for INP is defined by a small group of active producers, each pursuing distinct strategic positions based on geography, application focus, and operational strengths. Mitsubishi Gas Chemical Company, Inc. has maintained a notable presence through its focus on synthetic resins and electronics-related applications, leveraging an integrated chemicals business model that emphasizes reliability, quality consistency, and long-term customer relationships. Its positioning reflects an emphasis on high-value applications where specification stability and technical support matter more than bare volume.
In China, Jiangsu Weunite Fine Chemical Co., Ltd. has built its relevance around fine chemical intermediates supporting agrochemicals and electronics, aligning with regional demand patterns and production scale advantages. Its strategy underscores the importance of matching manufacturing capabilities to the application priorities of nearby downstream industries, which can shorten lead times and improve responsiveness. Similarly, Suli Co., Ltd. focuses on pharmaceutical and fine chemical intermediates, positioning itself in segments where purity, documentation, and process control are particularly critical. This application-specific focus illustrates how producers are differentiating not just by price, but by the fit between their technical capabilities and the requirements of their chosen markets.
The market structure is evolving along several axes. On one hand, the concentration of output among leading producers creates a relatively stable but potentially inflexible environment, where incremental capacity additions and quality improvements can have outsized influence on pricing and availability. On the other hand, the growing importance of compliance, specialty applications, and supply reliability is opening space for differentiation that goes beyond conventional scale economies. New entrants or expanding producers that can combine cost discipline with strong technical execution and regulatory readiness have the potential to capture meaningful share in specific segments, particularly where existing supply is constrained or where customers are prioritizing resilience over lowest unit cost.
Strategic leadership in this environment is increasingly defined by the ability to balance multiple priorities simultaneously: maintaining cost competitiveness, investing in process and quality capabilities, managing regulatory exposure, and building trusted relationships with downstream customers. Companies that treat these as interconnected rather than isolated priorities are better equipped to sustain margins and protect market position as the landscape matures.
Forward-Looking Trends and Commercial Opportunities
Over the next three to five years, several trends are likely to shape how value is created and captured in the INP market. One prominent trend is the continuing premiumization of demand in high-specification applications. As electronics-related materials and advanced synthetic resins become more performance-sensitive, the share of demand tied to higher purity and tighter quality assurance is expected to grow. This creates opportunities for producers that can consistently meet elevated specifications and for downstream manufacturers that can secure reliable access to these grades without compromising supply continuity.
A second trend is the deepening role of regulatory and supply chain resilience as commercial differentiators. Buyers are increasingly evaluating suppliers not only on price and volume, but on their ability to provide stable delivery under shifting trade conditions, maintain compliant documentation, and support contingency planning. Suppliers that invest in visibility, flexibility, and compliance infrastructure can translate these capabilities into stronger customer retention and more favorable contract terms. This trend also opens the door for regional supply strategies that reduce exposure to cross-border friction while maintaining access to key demand centers.
PW Consulting
A third trend is the gradual re-balancing of capacity and sourcing strategies as raw material dynamics and energy costs continue to fluctuate. Market participants that diversify input sourcing, strengthen hedging approaches, or align production with regions offering more predictable cost structures will be better positioned to protect margins. At the same time, there is opportunity for producers to capture value by offering application-specific solutions that reduce the total cost of ownership for buyers, rather than competing purely on the headline price of the intermediate itself.
These trends are not without risk. Concentration in supply means that unexpected capacity constraints or strategic decisions by a small number of producers can quickly affect availability and pricing. Raw material volatility remains a persistent threat to cost predictability, particularly if energy prices or precursor availability shift abruptly. Regulatory divergence could also introduce uneven compliance burdens, affecting competitiveness across regions. Companies that prepare for these uncertainties by building flexibility into sourcing, capacity planning, and customer engagement will be better positioned to navigate them.
Strategic Implications for Decision-Makers
For manufacturers and producers, the priority is to strengthen the link between process capability and commercial positioning. Investing in purification consistency, analytical control, and production flexibility can unlock access to higher-value applications where specification reliability is a gating factor. At the same time, building a clear regulatory and sourcing strategy helps reduce exposure to input volatility and trade-related disruption. Producers that can articulate a dependable supply narrative and back it with operational discipline are more likely to secure long-term relationships in applications where downtime or variability carries significant downstream cost.
For investors, the most relevant question is not simply whether the market is growing, but where value is concentrating and why. Growth is increasingly tied to segments with higher specification demands and to suppliers that can combine scale with reliability and compliance readiness. Evaluating potential opportunities therefore requires looking beyond headline volume and examining the quality of customer relationships, the durability of cost structures, and the ability to adapt to regulatory and supply chain shifts. Companies with diversified application exposure and clear technical differentiation are more likely to sustain competitive advantage than those dependent on a single cost-sensitive channel.
For procurement and sourcing leaders, the strategic imperative is to balance cost efficiency with resilience in a market where concentration and volatility raise the stakes of supply disruption. Diversifying supplier relationships, understanding the regulatory posture of each source, and securing visibility into capacity and contingency plans can reduce risk without abandoning cost discipline. In practice, this means treating supplier selection as a multi-dimensional decision that includes technical fit, delivery reliability, compliance transparency, and the ability to support changing demand patterns over time.
As the market continues to evolve, the availability of detailed, segment-level intelligence becomes a critical input to decision-making. Granular visibility into application dynamics, regional demand shifts, purity-grade movement, and supplier-specific strategies can clarify where competitive advantage is being created and where exposure is accumulating. For teams responsible for planning, sourcing, or investment allocation, access to comprehensive and regularly updated analysis can reduce uncertainty and improve the quality of strategic choices. PW Consulting's full research report on the Isophthalonitrile market provides a more detailed breakdown of these dynamics, including deeper segmentation, competitive profiling, and scenario-based guidance for navigating the next phase of market development.
Polyacrylonitrile (PAN) Market
For detailed analysis of this topic, please visit the official page: Isophthalonitrile (INP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


