



Gel Batteries Market: Why 7.2% CAGR Growth Redefines Next Decade

The Gel Batteries Market: Strategic Trends and Commercial Opportunities Through 2032
The global gel batteries market has transitioned from a niche energy storage solution to a foundational component of modern infrastructure. With a base-year valuation of $2.49 billion in 2025 and a projected expansion to $4.04 billion by 2032, the sector is consolidating its position at a compound annual growth rate of 7.2 percent. This trajectory reflects a market that has moved beyond early-adopter status and is now embedding itself into telecommunications networks, renewable energy installations, and motive power applications. The growth profile signals maturity, but maturity does not equate to stagnation. Instead, it indicates a phase where strategic positioning, technological differentiation, and supply chain resilience will separate winners from followers.
Behind the headline numbers lies a complex operating environment. Gel batteries, particularly valve-regulated lead-acid variants, offer distinct advantages in safety, maintenance reduction, and thermal stability compared to traditional flooded designs. These attributes have made them attractive for stationary deployments where reliability outweighs the pursuit of maximum energy density. Yet the market is not operating in a vacuum. Technological competition, shifting regulatory frameworks, and evolving end-user expectations are reshaping how value is created and captured. Organizations that understand the structural forces driving demand will be better equipped to allocate capital, design product roadmaps, and mitigate exposure to cyclical or regulatory disruptions.
Tubular GEL Battery Market
The following analysis examines the market's current reality, the forces accelerating change, the competitive dynamics defining the landscape, and the strategic implications for decision-makers navigating the next five to seven years.
Market Snapshot: Scale, Growth, and Structural Reality
The gel batteries market has demonstrated consistent expansion over the past half-decade, growing from approximately $1.0 billion in 2020 to $2.49 billion in 2025. The forecast horizon through 2032 points to a market crossing the $4 billion threshold, with annual growth stabilizing at a mid-single-digit rate. This progression suggests a market that has escaped the volatility of early-stage adoption and entered a phase where incremental demand from infrastructure projects, energy transition initiatives, and mobility applications compounds year over year.
PW Consulting
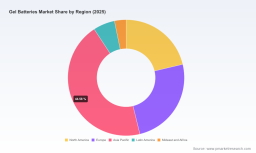
Regional distribution reveals a balanced but uneven landscape. Asia Pacific commands the largest share of total market value, reflecting rapid deployment of renewable energy systems, expanding telecommunications networks, and growing industrial activity across multiple economies. Europe and North America follow as significant contributors, each anchored by mature industrial bases and policy-driven energy storage mandates. Latin America and the Middle East and Africa represent smaller but strategically important niches, often characterized by off-grid and remote power requirements where gel batteries' durability and low maintenance profiles align with local operating conditions.
In terms of application segmentation, stationary use cases represent the dominant share of market activity, encompassing telecom backup power, renewable integration, and utility-scale storage deployments. Motive applications, including material handling, marine operations, and commercial fleet electrification, form a substantial secondary segment that is gaining momentum as operators seek safer, longer-life alternatives to conventional battery chemistries. Across both categories, the underlying pattern is consistent: gel batteries are being specified not as the cheapest option, but as the most reliable fit for environments where downtime, safety, and lifecycle costs carry significant operational and financial weight.
Polymer Gel Market
The Key Challenges Shaping the Market's Next Phase
Three structural challenges define the current inflection point for gel batteries. The first is the intensifying competition from alternative energy storage chemistries. Lithium-based systems, sodium-ion developments, and emerging solid-state prototypes continue to capture attention in applications where energy density, rapid charge cycles, or space constraints dominate decision-making. While gel batteries hold strong advantages in safety, cost predictability, and proven reliability, they are not immune to substitution pressure. The challenge for incumbents is not to outperform every alternative in every metric, but to sharpen the value proposition in applications where gel technology's specific attributes deliver unambiguous total-cost-of-ownership benefits.
The second challenge lies in navigating evolving regulatory and compliance expectations. Industry-wide adoption of valve-regulated lead-acid gel technology is increasingly tied to carbon tax policies, emission reduction goals, and energy storage standards that vary across jurisdictions. At the same time, quality and environmental management frameworks such as ISO 9001 and ISO 14001 have become baseline requirements for production facilities, raising the operational bar for manufacturers seeking to enter or expand within regulated markets. These standards create a higher threshold for market participation, which can protect established players from low-quality entrants but also adds cost and complexity for organizations scaling production or entering new regions.
The third challenge involves supply chain continuity and critical mineral dynamics. Lead remains the core material underpinning gel battery construction, and its availability, pricing, and recycling infrastructure directly influence manufacturing economics and margin stability. While ongoing mining and recycling efforts by major producers support supply chain stability, the market remains sensitive to geopolitical disruptions, environmental permitting timelines, and shifts in raw material trade flows. Companies that treat lead sourcing and recycling as strategic capabilities rather than back-office procurement tasks will be better positioned to manage cost volatility and maintain production continuity.
Drivers Accelerating Market Evolution
Technology innovation continues to be a primary catalyst. Advances in gel electrolyte formulation, plate design, and valve-regulated architecture have improved deep-cycle performance, extended service life, and enhanced thermal resilience. These improvements are particularly relevant for renewable energy storage and telecom backup, where batteries must withstand frequent charge-discharge cycles and operate reliably in challenging environmental conditions. Recent product introductions illustrate how manufacturers are translating technical progress into commercially relevant outcomes. For example, new high-capacity gel battery designs targeted at grid storage and renewable integration projects have expanded the usable performance envelope for stationary deployments, while modular gel systems for commercial electric vehicle fleets have emphasized safety and lifecycle durability in motive applications.
Policy and regulatory frameworks are reinforcing demand in specific sectors. Targeted renewable energy subsidies, grid code updates, and utility-scale storage mandates continue to support deployment of gel battery systems where long-duration reliability and safety certifications matter. Carbon-related policies and emission reduction goals in multiple regions also favor valve-regulated lead-acid gel technology as part of broader decarbonization strategies. These policy signals do not guarantee uniform growth, but they do create predictable pockets of demand that manufacturers and investors can plan around, provided they align product specifications and compliance documentation with local requirements.
Demand-side behavior is shifting as end-users increasingly prioritize lifecycle economics over upfront price. Telecommunications operators, renewable energy developers, and industrial facilities are evaluating storage solutions through the lens of maintenance burden, failure risk, replacement frequency, and safety compliance. Gel batteries' sealed design, reduced gassing, and lower maintenance requirements resonate with operators managing distributed assets across wide geographies or constrained access conditions. In motive applications, fleet operators exploring commercial electrification are weighing gel-based options for their safety profile and deep-cycle capability, particularly in environments where thermal runaways or hazardous incidents carry unacceptable operational or reputational costs.
Supply chain and cost structure dynamics are also reshaping competitive positions. Manufacturing capacity expansions, investments in process optimization, and the formalization of recycling loops are influencing both cost efficiency and supply resilience. Recent capacity-related investments signal that leading manufacturers are positioning for sustained demand rather than treating current orders as temporary spikes. At the same time, the emphasis on certified production environments and documented quality systems adds a layer of operational discipline that favors organizations with established management systems and supply chain transparency.
Competitive Landscape: Positioning, Strategy, and Evolution
The gel batteries market is characterized by a concentrated but diversified competitive field. A handful of large, internationally active manufacturers account for a substantial share of total market value, while a broader set of regional and application-focused players compete on specialization, service, and local market knowledge. This concentration creates a landscape where scale, technical credibility, and application expertise all matter, and where the distance between leaders and followers is defined less by raw production volume than by the ability to match technology to end-user requirements.
Several companies illustrate the strategic diversity within the market. Exide Technologies has emphasized patented gel valve-regulated lead-acid technology for deep-cycle applications spanning marine, equipment, renewable energy storage, and industrial uses, and has signaled capacity expansion to serve renewable energy and telecommunications demand. Trojan Battery Company has built a reputation around deep-cycle gel batteries for solar, marine, and off-grid renewable energy systems, positioning its products for environments where cycle life and field reliability are paramount. East Penn Manufacturing's Deka Ready Power gel line targets motive power and renewable applications, reflecting a strategy that bridges industrial mobility and stationary storage. GS Yuasa Corporation focuses on gel lead-acid batteries for industrial, renewable, and telecom energy storage, leveraging its broader industrial battery heritage. Amara Raja Batteries has concentrated on gel solutions for industrial and renewable energy storage, aligning with regional demand patterns in its home market and adjacent export opportunities. Sonnenschein Batteries, operating within the Exide Group framework, has highlighted high-capacity gel batteries for grid storage and renewable integration, reinforcing the stationary storage emphasis. Enersys addresses both motive and stationary energy storage through gel technology, while Banner Batteries serves industrial and renewable energy use cases with a focus on application-specific performance.
The strategic positioning of these players reveals several common themes. First, application specialization is a recurring differentiator. Rather than competing solely on volume, many leading manufacturers build credibility by optimizing gel formulations, terminal designs, and housing configurations for specific duty cycles and environmental conditions. Second, product architecture is evolving toward modularity and integration-friendly designs, especially in stationary and fleet applications where scalability, serviceability, and system-level compatibility reduce deployment friction. Third, investment in manufacturing capacity and research infrastructure indicates a forward-looking posture. Recent developments, such as dedicated R&D centers focused on next-generation gel chemistry and manufacturing processes, alongside capacity expansions and new product launches for grid storage and commercial fleet use, suggest that incumbents are preparing for sustained demand rather than short-lived cycles.
The market structure appears likely to evolve along two parallel paths. Consolidation may continue as larger manufacturers acquire complementary technologies, regional distribution capabilities, or application-specific product lines to strengthen their positions in high-growth segments. At the same time, differentiation and fragmentation may persist in niche application areas where specialized formulations, local service networks, or compliance expertise create defensible positions. New entrants face a challenging environment because quality certification, supply chain credibility, and application testing create meaningful barriers, but targeted innovation in electrolyte chemistry, manufacturing efficiency, or system integration can still open focused opportunities.
Looking Ahead: Three Trends to Watch and the Opportunities They Create
The first trend is the deepening integration of gel batteries into renewable energy and grid-support infrastructure. As utilities, independent power producers, and commercial energy consumers expand storage portfolios, gel batteries are well positioned for applications that value safety, predictable performance, and lower maintenance overhead. The opportunity here lies not in claiming superiority over every alternative chemistry, but in designing system-level solutions that combine gel storage with appropriate inverters, monitoring, and thermal management to deliver reliable, compliant installations. Organizations that can package storage capability as a complete, configurable solution rather than a standalone component will capture more value and reduce deployment risk for end-users.
The second trend is the growing relevance of gel batteries in motive and commercial fleet applications. Modular gel systems designed for commercial electric vehicle fleets reflect an emerging recognition that safety, cycle life, and operational robustness can outweigh pure energy density considerations in certain duty cycles. This creates opportunities for manufacturers and integrators to develop application-specific packs, charging protocols, and service models that address fleet operators' practical concerns. The commercial prize is likely to accrue to players who can demonstrate verified lifecycle performance, predictable replacement intervals, and integration with fleet management systems, rather than those who compete only on specification sheets.
The third trend is the strengthening of standards, certification, and sustainability expectations as market norms. As quality and environmental management requirements become embedded in procurement decisions, and as energy storage standards continue to mature, compliance capability will increasingly function as a competitive asset. This favors organizations that can document manufacturing consistency, environmental responsibility, and product traceability with credibility. It also creates a subtle but important opportunity: in markets where procurement teams face reputational, regulatory, or safety scrutiny, the ability to provide clear certification and lifecycle documentation can influence specifications as much as price or performance.
These trends carry inherent uncertainties. Substitution from emerging chemistries could accelerate in applications where weight, footprint, or charging speed dominate. Regulatory frameworks may shift in ways that alter subsidy structures, grid interconnection rules, or compliance burdens, changing the economics of deployment in specific regions. Raw material dynamics, including lead availability and recycling efficiency, will continue to influence cost stability and margin resilience. The commercial implication is not to assume linear growth, but to build flexibility into product planning, supply chain design, and geographic prioritization so that strategy can adapt as conditions evolve.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to sharpen application-specific value propositions while strengthening the operational foundations that support scale. This means investing in product architectures that align with the duty cycles and environmental conditions of target segments, expanding capacity and process efficiency where demand signals are durable, and treating quality certification and supply chain transparency as strategic capabilities rather than administrative tasks. Companies should also evaluate where modular, integration-friendly designs can reduce customer deployment friction and create more defensible positions in stationary and motive applications. Where feasible, partnerships with system integrators, renewable energy developers, or fleet operators can translate product strength into installed-base advantage.
For investors, the market presents a profile that rewards disciplined segmentation and operational due diligence. The broad growth trajectory is attractive, but value creation will likely concentrate in companies that combine credible technology, certified production, and application-focused go-to-market strategies. Due diligence should examine not only top-line momentum but also the specificity of product offerings, the strength of manufacturing and recycling capabilities, the clarity of compliance documentation, and the durability of demand in targeted end markets. Portfolios that distinguish between generalized battery producers and organizations with clear gel-specific differentiation are more likely to capture the market's structural upside while limiting exposure to broader chemistry competition.
For procurement and operational decision-makers, gel batteries should be evaluated through a total-cost-of-ownership lens that accounts for maintenance burden, safety requirements, lifecycle expectancy, and compliance risk. In environments where downtime, hazardous incident risk, or maintenance access constraints carry significant cost, gel-based solutions may justify their selection even when alternative chemistries appear competitive on initial price or energy density. Procurement teams should request application-relevant performance data, certification documentation, and lifecycle service expectations, and should align specifications with the operational realities of deployment rather than generic benchmark comparisons. Where projects involve grid integration, telecom backup, or fleet usage, working with suppliers who can provide configurable, documented, and service-ready solutions will reduce downstream risk.
The strategic value of detailed intelligence in this market is substantial. Market growth, competitive moves, policy shifts, and technology developments are unfolding at a pace that makes broad generalizations insufficient for planning. Organizations that need granular segmentation data, company-level benchmarking, regional demand filters, or scenario-based forecasting will benefit from structured research that connects macro trends to specific operational decisions. For those evaluating market entry, capacity planning, partnership opportunities, or procurement specifications, a comprehensive report can provide the detail necessary to move from directional confidence to precise execution.
For detailed analysis of this topic, please visit the official page: Gel Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


