



Microbial Identification Market: Why 9.07% CAGR Reshapes Diagnostics

Navigating the Microbial Identification Market: Strategic Trends and Commercial Opportunities Through 2032
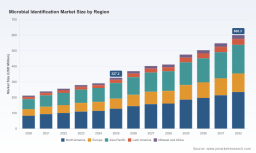
The microbial identification market has entered a decisive growth phase, transitioning from a specialized laboratory tool to an essential operational capability across healthcare, pharmaceutical quality control, food safety, and environmental monitoring. Valued at USD 212.0 million in 2020, the market expanded steadily to USD 327.2 million by 2025, reflecting a compound annual growth rate of 9.07 percent projected through 2032. At that trajectory, revenue is expected to surpass the USD 600 million threshold by the end of the forecast window. This expansion is not merely a function of incremental laboratory adoption; it signals a structural shift in how organizations detect, classify, and respond to microbial threats and quality deviations.
The momentum is sustained by converging pressures. Rising antimicrobial resistance, tightening regulatory expectations for contamination control, and the growing economic cost of delayed or inaccurate identification have elevated microbial identification from a discretionary upgrade to a core compliance and risk-mitigation function. At the same time, the market remains relatively fragmented. The top three players account for approximately 24.6 percent of total revenue, while the top five hold 26.2 percent, indicating that scale advantages exist but have not yet produced a consolidated oligopoly. This concentration profile leaves meaningful room for differentiated positioning, regional expansion, and technology-led disruption.
Key Challenges and Inflection Points
Despite the clear growth trajectory, several structural challenges are reshaping how participants compete and how end users evaluate solutions. The first challenge lies in the widening performance gap between centralized reference laboratories and decentralized point-of-need settings. Traditional identification workflows still struggle with turnaround time, sample preparation complexity, and database limitations when confronting rare, fastidious, or rapidly evolving pathogens. Organizations that require same-day decisions in clinical, manufacturing, or field environments are increasingly unwilling to accept multi-day turnaround cycles, forcing vendors to balance analytical depth with operational simplicity.
A second inflection point centers on regulatory and reimbursement alignment. Regulatory clearance, quality management certification, and coding mechanisms for test reimbursement are no longer peripheral compliance issues; they directly shape market access, purchasing confidence, and the economic viability of new systems. As diagnostic and quality-control workflows become more automated and integrated, ambiguous reimbursement pathways or inconsistent certification expectations can slow adoption, even when the underlying technology is mature. Participants that treat regulatory strategy as an afterthought risk losing momentum to competitors who design clearance, documentation, and billing alignment into their product roadmaps from the outset.
A third challenge emerges from data usability and workflow integration. Identification is only valuable when it feeds timely decisions. Laboratories and production environments increasingly expect systems that not only classify organisms but also connect results to downstream actions, such as antibiotic stewardship decisions, batch release judgments, or environmental corrective measures. Vendors that deliver isolated identification outputs without interoperable software, standardized reporting, or scalable database updates are seeing their solutions marginalized in consolidated laboratory ecosystems. The market is therefore moving from a hardware-centric evaluation toward a total-workflow assessment.
Key Drivers of Market Change
Technological Innovation and Analytical Performance
Technology advancement remains the most visible driver of adoption. Modern identification platforms are increasingly judged on speed, accuracy across difficult organism classes, and the ability to scale database coverage without sacrificing reproducibility. In clinical and industrial settings, this means systems must handle gram-positive and gram-negative bacteria, anaerobes, yeasts, mycobacteria, molds, and resistant pathogens with consistent confidence. The competitive edge is shifting toward solutions that combine reliable spectral or molecular discrimination with streamlined sample handling and high-throughput software workflows.
Recent product developments illustrate this direction. In March 2025, bioMérieux received FDA 510(k) clearance for its VITEK COMPACT PRO ID/AST system, designed to support rapid microorganism identification and antibiotic susceptibility testing in clinical and industrial laboratories. The launch reflects a broader push toward integrated identification and susceptibility workflows that compress turnaround time while preserving interpretive value for treatment and quality decisions. Later in the year, Bruker expanded its FDA-cleared portfolio by securing clearance for additional claims on the MALDI Biotyper CA System, extending the cleared reference library to 549 species and introducing workflow-oriented software and shuttle capabilities intended to improve laboratory throughput. These developments matter because they show two distinct but converging strategies: one emphasizing integrated ID/AST utility for routine lab operations, the other expanding organism coverage and workflow efficiency for high-volume identification environments.
Pathogen Detection Market
Regulatory and Policy Environment
The regulatory landscape is becoming a defining commercial variable. In the United States, FDA 510(k) clearance for microbial identification tests has growing practical significance because it can enable reimbursement pathways through CPT codes, directly affecting the economics of test adoption in clinical settings. This linkage between clearance and reimbursement is changing how laboratories evaluate new systems. A technically capable platform that lacks clear regulatory status or documented quality-system certification may face longer procurement cycles, more conservative pilot decisions, or limited budget allocation.
Beyond clearance, quality management expectations continue to shape procurement in medical-grade applications. ISO 13485 certification has become a baseline expectation for systems intended for medical use, influencing buyer confidence in consistency, risk management, and post-market support. At the same time, regulatory momentum around antimicrobial stewardship is reinforcing demand for faster and more reliable identification in clinical environments, where earlier organism characterization can support more targeted therapy and reduce unnecessary broad-spectrum use. For manufacturers, this means regulatory strategy is no longer a documentation exercise; it is a market-access lever that affects sales cycles, customer confidence, and the speed at which new features can be commercialized.
Demand-Side Shifts Across End-Use Segments
Demand is expanding beyond traditional diagnostic laboratories. Pharmaceutical manufacturing quality control continues to drive consistent adoption, as contamination events carry steep consequences in terms of batch loss, investigation cost, and regulatory exposure. In this environment, identification is not simply a scientific exercise; it is part of a containment and root-cause workflow that must be fast, traceable, and repeatable. Food safety and environmental monitoring represent additional demand centers, where organizations increasingly need to detect and identify contaminants before they escalate into recalls, site closures, or compliance breaches.
Behaviorally, purchasers are shifting from isolated instrument evaluation toward workflow-level purchasing. Laboratories and quality teams want systems that fit existing staffing models, reduce manual touchpoints, and produce results that integrate with laboratory information systems or quality management processes. This is especially relevant in settings where skilled microbiologists are in short supply or where throughput demands exceed the practical capacity of legacy methods. As a result, adoption decisions increasingly weigh database breadth, software usability, and the ability to standardize identification across multiple sites or shifts.
Supply Chain and Cost Structure Dynamics
Cost structures are being reconsidered across the value chain. The operational burden of microbial identification is no longer limited to instrument acquisition; it includes consumables, database access, calibration and maintenance, training, and the hidden cost of delayed results. In many organizations, the true cost comparison between methods depends on total turnaround time, error rates, and the downstream impact of misidentification or inconclusive results. This has increased interest in platforms that reduce hands-on time and minimize repeat testing, even when upfront instrument economics appear less advantageous.
Supply chain resilience is also influencing procurement strategy. Organizations operating across multiple geographies or managing critical production processes are more cautious about dependence on single-source consumables or proprietary workflows that are difficult to scale during disruptions. That caution is encouraging interest in systems with robust support networks, predictable consumables availability, and software architectures that can be updated without repeated hardware replacement. For vendors, this environment rewards transparent total-cost narratives and dependable service models as much as it rewards analytical performance.
Competitive Landscape and Leading Strategies
The competitive landscape reflects a market where performance, regulatory readiness, and workflow design are being used to carve out defensible positions rather than compete solely on price. Bruker Corporation, based in Billerica, Massachusetts, has emphasized the MALDI Biotyper CA System as a focused offering for microbial identification, with FDA-cleared MALDI-TOF mass spectrometry intended to support rapid identification of gram-positive and gram-negative bacteria, anaerobes, and yeasts from cultured isolates. Its associated MBT Compass HT CA software is positioned to improve workflow efficiency, an increasingly important consideration for laboratories handling high sample volumes or seeking to reduce manual bottlenecks. Bruker’s recent expansion of cleared claims and reference library coverage suggests a strategy centered on broadening organism coverage and strengthening the practical usability of the system in cleared-use settings.
bioMérieux, headquartered in Marcy-l’Étoile, France, has taken a different but complementary approach, emphasizing integrated identification and susceptibility testing through its VITEK MS PRIME and VITEK COMPACT PRO systems. Its FDA 510(k)-cleared MALDI-TOF and automated ID/AST offerings are designed for both clinical and industrial microbial identification, with expanded databases that address mycobacteria, molds, and resistant pathogens. The company’s emphasis on combined ID/AST functionality reflects a strategy aimed at environments where identification is only one step in a broader decision chain, particularly where antibiotic stewardship, infection control, or quality release decisions depend on timely susceptibility information alongside organism identification.
Microbial Air Samplers Market
The strategic differentiation between these leaders is instructive. One approach prioritizes broad organism coverage and workflow efficiency for identification-intensive operations. The other emphasizes integrated clinical and industrial utility, linking identification more tightly to downstream interpretation and action. Both strategies address real buyer priorities, but they appeal to different purchasing rationales. In practice, this means competition is increasingly segment-specific: laboratory types, throughput profiles, organism mix, and regulatory requirements all influence which value proposition is more compelling.
PW Consulting
Market Structure and Evolution
Market concentration remains moderate, leaving the industry in a phase where scale matters but does not yet dictate outcomes. That structure favors companies that can combine credible technology, clear regulatory positioning, and strong application-specific messaging. It also leaves space for regional players and niche entrants that can serve localized demand, specialized organism panels, or specific compliance environments more flexibly than larger platforms. Over time, the market is likely to move toward selective consolidation, but not uniformly. Consolidation will probably be driven by workflow integration, database stewardship, and service-network economics rather than by instrument pricing alone.
New entrants and technology shifts will continue to test incumbents, especially where identification can be embedded into broader diagnostic, quality, or environmental monitoring ecosystems. However, entry barriers remain meaningful because practical adoption depends on more than analytical promise. Buyers look for cleared or certified status where applicable, established database maintenance, predictable consumables supply, and integration with existing laboratory or manufacturing workflows. As a result, the most durable competitive advantage will belong to organizations that treat identification as an end-to-end capability rather than a standalone instrument sale.
Forward Outlook: Trends Shaping the Next Three to Five Years
One of the most consequential trends is the continued compression of identification workflows into faster, more decision-ready formats. Laboratories and quality teams are unlikely to accept longer turnaround times simply because a method is familiar. The demand for same-day or near-real-time identification will keep pushing platforms toward higher throughput, simpler sample handling, and software that reduces interpretation burden. Commercially, this trend favors vendors that can demonstrate measurable workflow gains, not just incremental accuracy improvements.
A second trend is the growing importance of database depth and updateability as a competitive asset. As pathogen populations evolve and industrial contamination profiles become more diverse, static identification libraries will become less valuable than actively maintained, expandable databases. Organizations will increasingly evaluate whether a vendor can sustain coverage for emerging or less common organisms, support regional variation in microbial profiles, and deliver updates without disrupting operations. This shifts competitive advantage toward companies with strong bioinformatics, curation processes, and customer-support infrastructure.
A third trend is the alignment of identification solutions with stewardship and risk-management objectives. In clinical settings, faster identification supports antimicrobial stewardship by enabling more informed therapy decisions earlier in the care pathway. In pharmaceutical, food, and environmental contexts, identification increasingly supports contamination response, root-cause analysis, and compliance documentation. Solutions that connect identification results to actionable downstream workflows are likely to gain preferential consideration because they reduce the operational gap between result generation and decision implementation.
These trends create tangible commercial opportunities. Vendors can capture share by packaging identification with workflow software, database services, and support models that reduce total operating burden. Procurement teams can lower risk by prioritizing systems that align with their organism mix, throughput needs, and regulatory context rather than choosing on instrument specifications alone. Investors and strategic partners should pay attention to companies that demonstrate not only technical credibility but also the ability to navigate clearance, certification, reimbursement alignment, and multi-site deployment. At the same time, uncertainty remains. Reimbursement pathways can shift, regulatory expectations can tighten, and adoption can slow if workflow integration proves more difficult than anticipated. Database maintenance costs, training demands, and consumables availability may also influence the realized pace of growth, especially in cost-sensitive or resource-constrained environments.
Strategic Implications for Decision Makers
For Manufacturers and Solution Providers
Product strategy should be built around total workflow value rather than identification performance in isolation. That means prioritizing database curation, software usability, service reliability, and regulatory readiness as core commercial assets. Where applicable, clearance and certification should be treated as enablers of market access and purchasing confidence, not as optional compliance milestones. Companies should also define their positioning by application context, since clinical, pharmaceutical, food safety, and environmental buyers evaluate risk, turnaround, and integration needs differently.
Go-to-market execution should emphasize predictable operating economics and demonstrable time-to-result benefits. In fragmented markets, regionalized support, site-level deployment expertise, and clear documentation can be as influential as product features. Manufacturers that can show how identification reduces repeat testing, shortens investigation cycles, or supports stewardship and quality decisions will have stronger leverage in competitive evaluations.
For Investors and Strategic Partners
Investment theses in this space should account for more than top-line growth rates. Sustainable value creation depends on regulatory positioning, database and software stewardship, service economics, and the ability to serve multiple end-use segments without diluting focus. Because market concentration is moderate, there is room for both scaled incumbents and specialized players, but long-term winners are likely to be those that can convert technological capability into repeatable deployment and customer retention.
Partners should also monitor where identification is becoming embedded into broader workflows. Opportunities may arise not only in instrumentation but also in middleware, data interpretation, quality documentation, and support services that make identification results more actionable. Conversely, exposure to segments with unclear reimbursement, weak service infrastructure, or limited regulatory alignment may carry higher execution risk.
For Procurement, Laboratory, and Quality Leaders
Purchasing decisions should begin with the operational problem rather than the instrument category. Define the required organism coverage, acceptable turnaround time, staffing constraints, and integration needs before evaluating vendors. In many cases, the more relevant comparison is not instrument price but total workflow impact, including hands-on time, repeat testing, database relevance, and the reliability of ongoing support.
Where regulatory compliance and reimbursement affect adoption, confirm clearance status, certification expectations, and coding implications early in the evaluation process. Also assess whether the solution can be deployed consistently across multiple sites or shifts, since standardization often determines whether identification capabilities deliver enterprise value or remain confined to a single high-performing unit.
Conclusion
The microbial identification market is expanding under the influence of clearer regulatory expectations, stronger demand for faster and more actionable results, and a competitive field that is increasingly rewarding workflow-integrated solutions. Growth to the USD 600 million range by 2032 is plausible, but the commercial winners will be determined by how effectively organizations translate analytical capability into reliable, compliant, and decision-ready operations. For executives, investors, and procurement leaders, the strategic priority is to look beyond specifications and evaluate how identification solutions fit into the broader economics of risk reduction, throughput, and stewardship. For those seeking a more detailed view of segment-level demand, regional dynamics, and vendor-specific positioning, the full market research report provides the deeper breakdown needed to shape execution plans with greater confidence.
For detailed analysis of this topic, please visit the official page: Microbial Identification Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


