



Reprocessed Medical Device Market: Why 16.98% CAGR Changes Everything

Navigating the Reprocessed Medical Device Market: Strategic Trends and Commercial Opportunities
The reprocessed medical device market has transitioned from a niche cost-saving measure to a strategic component of healthcare sustainability and supply chain resilience. As of 2025, the sector is valued at approximately 1.55 billion USD, reflecting steady growth from a 2020 baseline of around 0.99 billion USD. The trajectory points toward a compelling expansion phase, with the market projected to exceed 4.6 billion USD by 2032, driven by a compound annual growth rate of nearly 17 percent. This growth is not merely a function of inflationary adjustments or volume expansion; it reflects a fundamental shift in how healthcare systems approach device utilization, waste reduction, and operational efficiency. For executives and investors tracking MedTech dynamics, the reprocessed device space represents a convergence of regulatory maturity, clinical acceptance, and financial pragmatism that is reshaping procurement strategies across hospital networks and ambulatory surgery centers.
However, the market’s momentum is accompanied by structural challenges that demand strategic attention. First, regulatory fragmentation across jurisdictions creates uneven adoption pathways. While certain regions have standardized reprocessing frameworks, others are still formalizing legal and quality-system requirements, leading to inconsistent commercialvelocity. Second, the industry operates with a relatively fragmented competitive landscape, characterized by a low concentration ratio where the top three players collectively account for only around twenty-six percent of market revenue and the top five entities hold less than thirty percent. This dispersion suggests ample room for consolidation, partnership formation, and competitive differentiation, but it also means that no single organization currently dominates the value proposition across all device categories or geographies. Third, the operational economics of reprocessing—spanning cleaning, disinfection, inspection, and functional testing—require disciplined cost control and validation rigor to maintain clinician confidence and procurement ROI. Facilities processing instruments in trays or peel packs face per-unit cost dynamics that must be managed alongside throughput capacity and sterility assurance standards.
Worldwide Medical Device Reprocessing Market
Key Drivers Shaping the Reprocessed Device Ecosystem
Several interlocking forces are accelerating the market’s evolution, each carrying distinct implications for commercial strategy and operational planning.
Used And Refurbished Medical Devices Market
Technological Innovation and Validation Advancements
Progress in reprocessing technology has expanded the scope of devices that can be safely and reliably reprocessed. Modern closed-loop systems, advanced sterilization protocols, and rigorous functional testing frameworks have enabled reprocessors to validate single-use devices for multiple clinical cycles without compromising performance. The ability to secure device-specific regulatory clearances—for example, gaining approval to reprocess steerable introducers and mapping catheters for additional uses—demonstrates how targeted technical validation can unlock new product categories and reinforce a reprocessor’s market position. These innovations reduce the historical skepticism around reprocessed device reliability and create a foundation for broader clinical acceptance across cardiology, laparoscopic, orthopedic, and gastroenterology applications.
Regulatory and Reimbursement Alignment
Policy developments are increasingly supporting the commercial viability of reprocessing. Regulatory frameworks now require that FDA-regulated reprocessing activities be conducted by commercial reprocessors or hospital systems operating under manufacturer-like quality system regulations, with appropriate clearances and compliance documentation. Importantly, reprocessed devices that meet regulatory standards are eligible for reimbursement under standard healthcare payment structures on comparable terms to non-reprocessed devices. This reimbursement parity reduces the financial burden on healthcare providers and aligns reprocessed procurement with existing budgeting cycles. Coupled with recent regulatory initiatives in Europe that have formalized the legalization of medical device reprocessing to advance sustainable healthcare practices, the policy environment is shifting from cautious oversight to active enablement.
Demand-Side Shifts in Healthcare Delivery
Healthcare providers are under sustained pressure to balance clinical quality, cost containment, and environmental stewardship. The expansion of ambulatory surgery centers and outpatient procedural volumes has intensified the need for cost-effective device sourcing without sacrificing operational reliability. Reprocessed devices offer a tangible pathway to reduce per-procedure expenditures while supporting institutional sustainability goals. Clinician and procurement teams are increasingly evaluating reprocessed options not solely as a cost alternative, but as a supply chain diversification strategy that mitigates exposure to single-use device shortages and price volatility. This demand-side evolution is particularly evident in high-utilization specialties where device turnover is frequent and reprocessing can yield measurable cost and waste reductions.
Supply Chain and Cost Structure Dynamics
The economics of reprocessing have matured to the point where per-instrument processing costs are now well-characterized and increasingly predictable. Processing expenses for devices in trays or peel packs have established ranges that allow facilities to model procurement savings with greater precision. At the same time, supply chain efficiency initiatives—such as closed-loop reprocessing workflows and paid donor programs—have streamlined the movement of devices between clinical sites and reprocessing facilities. These operational improvements lower friction in the reverse logistics chain and make reprocessed sourcing more scalable for mid-sized surgical centers and hospital networks seeking to optimize device utilization without compromising sterility or turnaround time.
Competitive Landscape and Leading Strategies
The reprocessed medical device market is shaped by a diverse set of participants ranging from specialized reprocessors to large medtech and healthcare supply enterprises. Despite the low overall market concentration, distinct strategic patterns are emerging among organizations that have built or expanded their reprocessing capabilities.
PW Consulting
Strategic Positioning and Differentiation
Leading players are differentiating themselves along several dimensions. Some specialize in device-specific reprocessing with extensive regulatory clearances, building authority in high-value categories such as electrophysiology and cardiology devices. This clearance-driven approach creates barriers to entry for less validated competitors and reinforces trust with clinical teams that require documented performance consistency. Others have focused on specialty segments such as ENT and orthopedic devices, leveraging closed-loop reprocessing and donor programs to serve ambulatory surgery centers with an emphasis on cost reduction and supply chain efficiency. Large medtech and distribution organizations, meanwhile, have integrated reprocessed offerings into broader sustainability portfolios, pairing reprocessed devices with remanufactured solutions and institutional sustainability programs. Their scale and existing hospital relationships allow them to bundle reprocessing into wider procurement engagements, often positioning it as part of a comprehensive cost and waste reduction strategy.
Recent Dynamics and Market Evolution
Recent industry developments highlight how the competitive landscape is being reshaped by regulatory milestones, partnership activity, and regional policy shifts. One notable advancement is the achievement of multiple FDA clearances by a specialized reprocessor for a steerable introducer, reinforcing its position as the only reprocessor cleared for that device and illustrating how clearance accumulation can create defensible commercial positioning. Alongside this, strategic partnerships between reprocessing organizations and established surgical equipment providers are enhancing workflow integration within sterile processing departments, improving the operational fit of reprocessed devices into existing hospital systems. In parallel, regulatory developments in Europe have formalized reprocessing legality, expanding the addressable market for European-focused reprocessors and signaling a broader institutional commitment to sustainable healthcare practices.
Consolidation, Fragmentation, and New Entrants
The market’s low concentration suggests multiple pathways for evolution. Consolidation through acquisitions or partnerships could accelerate as larger organizations seek to expand reprocessing portfolios or acquire clearance portfolios and operational expertise. At the same time, fragmentation may persist in specialty niches where device-specific validation requirements and regional regulatory differences create natural segmentation. New entrants are likely to emerge where there is clear regulatory clarity, demonstrated reimbursement parity, and measurable cost advantages for high-utilization device categories. Organizations that can combine rigorous quality systems, device-specific validation, and integrated supply chain solutions will be best positioned to capture share as the market scales.
Future Trends and Commercial Implications
Looking ahead across the next three to five years, several trends are likely to define the reprocessed medical device market and create distinct commercial opportunities.
Expansion of Reprocessable Device Categories
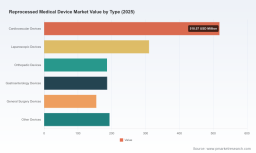
As validation protocols become more sophisticated and regulatory pathways more familiar, the range of reprocessed devices is expected to broaden beyond current high-volume categories. Cardiovascular and laparoscopic devices have already demonstrated strong adoption, but additional device types in orthopedic, gastroenterology, and general surgery applications are poised for increased reprocessing activity as clinical confidence grows and procurement teams seek wider cost and sustainability benefits. Organizations that invest early in device-specific validation and build clearance portfolios can secure first-mover advantages in emerging categories.
Integration with Sustainable Healthcare and Procurement Strategies
Reprocessing is increasingly embedded within broader institutional sustainability programs and procurement transformation initiatives. Healthcare systems are aligning device sourcing decisions with environmental targets, waste reduction commitments, and total-cost-of-care objectives. This integration creates opportunities for reprocessors and suppliers to position their offerings as part of coordinated sustainability and cost-management programs rather than isolated procurement alternatives. The commercial implication is clear: value propositions that combine clinical reliability, cost savings, and verifiable sustainability outcomes are more likely to gain traction with executive-level procurement decisions.
Regional Policy Harmonization and Market Expansion
As more jurisdictions formalize reprocessing regulations and reimbursement alignment, geographic expansion will become a more predictable growth lever. Recent regulatory developments in Europe and ongoing regulatory clarity in other markets indicate a trend toward greater harmonization, which can reduce entry barriers and support scaled commercial operations. However, regional differences in validation requirements, procurement practices, and clinical workflows will still demand localized strategy design. Organizations that navigate these differences with flexible operational models and region-specific compliance expertise will be better equipped to capture cross-market growth.
Potential Risks and Uncertainties
Despite the positive trajectory, several risks warrant attention. Regulatory changes or divergent standards across regions could introduce compliance complexity and slow adoption in certain markets. Reimbursement policies, while currently supportive, could evolve in ways that affect the financial attractiveness of reprocessed procurement. Additionally, any perception of quality or performance inconsistency—whether driven by isolated operational failures or insufficient validation transparency—could undermine clinician confidence and procurement momentum. Competitive dynamics may also intensify as larger players expand their reprocessing portfolios or pursue partnerships that compress margins for smaller specialists. Managing these risks requires disciplined quality systems, transparent validation practices, and proactive engagement with procurement and clinical stakeholders.
Strategic Action Points for Decision-Makers
For executives, strategists, and investors evaluating the reprocessed medical device market, the following considerations can help translate market dynamics into actionable priorities.
For Manufacturers and MedTech Enterprises
Integrate reprocessing considerations into product lifecycle and sustainability planning. Evaluate which device portfolios are most amenable to reprocessing and assess opportunities to partner with or support qualified reprocessors. Building compatibility with reprocessing workflows—through design-for-reprocessing principles, documentation support, and engagement with regulatory validation processes—can strengthen market positioning and align product strategies with evolving procurement norms.
For Investors and Strategic Allocators
Assess the reprocessed device space through the lens of regulatory clearance accumulation, device-specific validation depth, and supply chain integration capability. Organizations that have secured multiple clearances for high-value device categories and demonstrated operational scalability are positioned to benefit from expanding demand and consolidation trends. Monitor partnership activity and regional policy developments as leading indicators of market acceleration and competitive realignment.
For Procurement Leaders and Healthcare Providers
Evaluate reprocessed device programs as part of a broader cost and sustainability strategy rather than a standalone procurement tactic. Establish internal validation criteria that balance clinical performance requirements, sterility assurance, and financial impact. Engage with reprocessors that provide clear documentation, consistent turnaround, and integration support for sterile processing workflows. Where applicable, design procurement frameworks that capture total-cost benefits, including waste reduction and supply chain resilience, alongside per-unit savings.
The reprocessed medical device market is advancing along a clear growth trajectory, supported by regulatory maturity, reimbursement alignment, and increasing demand for sustainable and cost-effective healthcare delivery. Yet the market’s full potential will be realized by organizations that move beyond broad market awareness to precise segmentation, device-specific validation strategies, and region-tailored commercial execution. Detailed segment-level data, competitive benchmarking, and customized strategic guidance can materially improve decision quality in this evolving landscape. Accessing a comprehensive research report provides the granularity needed to map growth pockets, assess competitive positioning, and build actionable plans aligned with specific organizational objectives. For leaders seeking to act decisively in this space, deeper intelligence is the bridge between recognizing opportunity and capturing it.
For detailed analysis of this topic, please visit the official page: Reprocessed Medical Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


