



Mining Equipment Market 2026: Why 5.8% CAGR and Surface Mining Shifts Change Everything

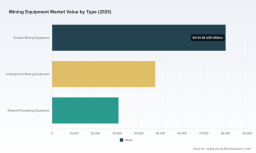
Strategic Trends and Commercial Opportunities in the Mining Equipment Market
The global mining equipment market is entering a phase of disciplined expansion, characterized by structural shifts in technology, regulatory pressure, and evolving demand patterns across commodity cycles. Between 2020 and 2025, market revenue grew from approximately $122.3 billion to $158.5 billion, reflecting a compound annual growth rate of 5.8% over the period. Forward projections indicate the market will continue expanding through 2032, with revenue expected to approach $235.6 billion by the end of the forecast horizon. This trajectory is not merely a function of commodity price cycles; it reflects a deeper realignment in how mining operations are designed, equipped, and operated. For executives and strategic planners, the opportunity lies in interpreting these structural shifts rather than extrapolating historical growth patterns.
The market remains moderately concentrated, with the top three players capturing roughly 52% of revenue and the top five approaching 65%. This concentration underscores the scale advantages required to compete in original equipment manufacturing, parts distribution, and aftermarket service networks. Yet concentration does not imply stagnation. Competitive dynamics are being reshaped by product differentiation in electrification, automation, and digital integration, as well as by supply chain reconfiguration and regional demand shifts. The following analysis examines the current market landscape, the forces driving change, the evolving competitive architecture, and the strategic implications for manufacturers, investors, and procurement leaders.
Market Landscape and Core Challenges
The mining equipment sector is navigating a transition from volume-driven expansion to value-driven differentiation. Revenue growth over the past five years has been supported by sustained capital expenditure in metal and mineral extraction, alongside replacement cycles for aging fleets. However, the same period has introduced several structural challenges that are reshaping competitive positioning and investment priorities.
First, decarbonization mandates and customer sustainability requirements are forcing a reevaluation of conventional equipment architectures. Mining operators are under increasing pressure to reduce scope 1 and scope 2 emissions, which is accelerating interest in battery-electric, hybrid, and hydrogen-ready platforms. This shift is not uniform across segments. Surface mining operations, which typically operate in open environments with higher payload requirements and longer haul distances, face different electrification constraints than underground operations, where ventilation costs, space limitations, and safety regulations create distinct engineering trade-offs. Equipment manufacturers must balance performance, total cost of ownership, and infrastructure readiness without compromising operational reliability.
Second, supply chain volatility and input cost dynamics are creating new margins pressures and sourcing strategies. In early 2026, steel prices remained near the bottom of the current price cycle, with little meaningful recovery projected for the year. At the same time, U.S. import tariffs of 25% on steel and aluminum have enabled domestic producers to capture greater market share and temporarily higher pricing, while the European Union's carbon border adjustment mechanism and tightened safeguard measures are expected to suppress near-term steel price recovery before stronger growth materializes in 2027. These dynamics are compounded by projections that global steel demand will rise modestly by 0.4% to 1.8 billion metric tonnes in 2026 following a 2.6% contraction in 2025. For equipment manufacturers, this environment requires disciplined procurement, regionalized sourcing where feasible, and pricing strategies that reflect both input cost trajectories and customer tolerance for price adjustments.
Mining Machine Market
Third, labor availability and skill constraints are affecting equipment design and service models. High-quality metallics availability may become a tighter constraint, supporting increased value in scrap grading and blending for mining equipment production. Beyond materials, the broader labor equation is shifting as mines adopt more automated and remotely supervised operations. This transition changes the skill profile required for maintenance, diagnostics, and fleet management, creating both a challenge for traditional service delivery and an opportunity for providers that can integrate training, remote support, and predictive maintenance into their commercial offerings.
These challenges are not isolated. They interact with each other and with regional demand patterns, creating a market environment where the winners are likely to be those that can integrate product innovation, supply chain resilience, and service differentiation rather than competing primarily on hardware specifications alone.
Key Drivers of Market Change
Several interconnected forces are shaping the direction of the mining equipment market. Understanding these drivers is essential for anticipating where demand will intensify, which product categories will gain share, and how competitive advantages will be constructed over the next several years.
Technology Innovation and Operational Integration
Automation and digital connectivity are moving from incremental features to core design principles. Manufacturers are increasingly embedding payload management, load-haul cycle optimization, and near-real-time operational data analysis into equipment platforms. Recent product launches illustrate this trajectory. In March 2026, Caterpillar introduced the Cat 6040 mining shovel integrating standard technologies such as Cat Payload to improve load-haul cycle efficiency. In April 2026, Volvo Construction Equipment launched the world's first serially produced electric articulated haulers for zero-emission quarry and mining operations. In April 2025, Hitachi Construction Machinery announced the LANDCROS Connect Insight solution for near-real-time operational data analysis of mining machinery. These developments point to a broader shift in which equipment is no longer evaluated solely on mechanical performance but also on its ability to generate actionable operational data and reduce energy intensity per ton moved.
Construction Equipment Market
Drilling and underground equipment are experiencing similar evolution. In May 2025, Epiroc introduced the Diamec Automated Rod Magazine for core drilling rigs, enabling 225 meters of automated drilling without manual input. This kind of automation reduces cycle interruptions, improves consistency, and addresses labor constraints in exploration and development drilling. The strategic implication is clear: equipment that reduces manual intervention, improves utilization rates, and integrates with broader site data ecosystems is gaining competitive relevance, particularly in operations where throughput consistency and energy efficiency are prioritized.
Policy and Regulatory Environment
Regulatory frameworks are becoming a decisive factor in equipment selection and regional market dynamics. Carbon-related regulations, import tariffs, and trade safeguards are reshaping cost structures and competitive positioning. The EU's carbon border adjustment mechanism and tightened safeguard measures are expected to influence steel pricing and import patterns, while U.S. tariffs on steel and aluminum have altered the domestic supply landscape. These policies do more than affect input costs; they influence where equipment is sourced, how total cost of ownership is calculated, and which manufacturers can compete effectively in specific regions.
Sustainability mandates are also affecting procurement criteria. Mining companies are increasingly required to demonstrate emissions reductions across their operations, which elevates the importance of equipment that supports lower energy consumption, alternative power sources, and reduced on-site emissions. This regulatory tailwind is not uniform across jurisdictions, but it is persistent enough to shape product roadmaps and commercial priorities, particularly in markets where government procurement, permitting, or community expectations are tied to environmental performance.
Demand-Side Shifts in Mining Operations
Demand for mining equipment is being reshaped by the commodity mix, operational efficiency goals, and the pace of fleet renewal. Metal mining continues to represent a substantial share of equipment demand, reflecting the criticality of copper, lithium, nickel, and other materials for electrification and industrial transition. Mineral mining and coal mining also drive significant equipment needs, though the growth trajectories and investment priorities differ by region and commodity strategy.
Beyond commodity volumes, demand is increasingly influenced by how mining companies conceptualize total cost of ownership. Operators are weighing not only purchase price but also energy consumption, maintenance intervals, parts availability, automation capabilities, and downtime risk. This shift favors suppliers that can offer integrated solutions, predictable service economics, and data-enabled performance guarantees. It also creates openings for differentiated offerings in segments where electrification, automation, or specialized underground configurations can deliver measurable operational improvements.
Supply Chain and Cost Structure Evolution
The cost structure of mining equipment production is undergoing recalibration. Input price cycles, trade policy, and material availability are influencing sourcing strategies and margin management. Steel prices near the bottom of their cycle, combined with tariff-driven regional price divergence, are prompting manufacturers to reconsider procurement timing, supplier diversification, and build-vs-source decisions. At the same time, expectations that global steel demand will stabilize and then grow modestly suggest that input cost volatility may persist rather than normalize quickly.
These dynamics are encouraging greater attention to material efficiency, scrap utilization, and supply chain transparency. The potential tightening of high-quality metallics availability is likely to increase the value of advanced scrap grading and blending practices in equipment production. Manufacturers that can manage material quality, reduce waste, and maintain delivery reliability under input constraints will be better positioned to protect margins and meet customer delivery expectations.
Competitive Landscape and Leading Strategies
The competitive architecture of the mining equipment market is defined by a mix of large, globally scaled manufacturers and specialized players with strong positions in specific equipment categories or operational environments. Scale confers advantages in R&D investment, global service networks, and the ability to standardize platforms across regions. Specialization, by contrast, can create defensible positions in underground equipment, drilling systems, mineral processing, or regional service networks where local knowledge and responsiveness are critical.
Caterpillar maintains a leading position in surface mining equipment, including haul trucks, excavators, loaders, and autonomous haulage systems, supported by a broad portfolio and integrated technology offerings. Komatsu competes across surface and underground equipment such as excavators, dump trucks, and drill rigs, and has been expanding its U.S. distribution footprint through strategic dealership acquisitions, including the acquisition of six Core Machinery dealerships in Arizona and California in June 2025 to strengthen its reach for southwest mining customers. Hitachi Construction Machinery produces hydraulic excavators and electric dump trucks for large-scale surface operations and has advanced its digital analytics capabilities through the LANDCROS Connect Insight solution.
In underground mining, Sandvik and Epiroc hold strong positions in rock drilling tools, excavation systems, and underground machinery, with Epiroc also advancing automation in drilling through products like the Diamec Automated Rod Magazine. Liebherr and Volvo Construction Equipment contribute to surface operations with haul trucks, excavators, and articulated haulers, with Volvo's recent entry into serially produced electric articulated haulers signaling a shift toward zero-emission equipment in quarry and mining settings. Sany Group is expanding its presence with electric and conventional mining excavators and loaders, reflecting broader competitive participation from Chinese manufacturers in both conventional and electrified categories.
Mineral processing and specialized equipment add further differentiation. Metso provides mineral processing equipment and machinery for mining operations, while Boart Longyear specializes in diamond core drilling equipment and services for exploration. Terex manufactures crushers, conveyors, and haul trucks, and J.H. Fletcher & Co. focuses on continuous miners, roof bolters, and underground equipment. MacLean Engineering supplies underground mining vehicles and battery-powered loaders, illustrating the growing relevance of electrified underground platforms. The inclusion of legacy assets such as Bucyrus International within the Caterpillar portfolio also highlights how historical acquisitions continue to shape product breadth and market reach.
Strategic Positioning and Differentiation
Leading manufacturers are differentiating along several axes. One is product electrification and zero-emission capability, as seen in Volvo's electric articulated haulers and Sany's electric excavators and loaders. Another is digital integration and operational analytics, reflected in Caterpillar's payload technologies, Hitachi's Connect Insight, and broader industry movement toward data-enabled fleet management. A third is service and distribution reach, where Komatsu's dealership expansion and established global service networks illustrate the importance of local responsiveness and parts availability. A fourth is specialization in underground or processing equipment, where Sandvik, Epiroc, Metso, and MacLean derive advantage from deep application expertise and targeted product architectures.
Market Evolution: Integration, Fragmentation, and New Entrants
The market is likely to continue evolving through a combination of consolidation, niche specialization, and new competitive pressure. Scale players may pursue selective acquisitions or partnerships to expand digital capabilities, electrified product lines, or regional service coverage. At the same time, specialized manufacturers can maintain or expand share by focusing on performance in constrained environments, such as underground operations or exploration drilling, where application-specific engineering matters more than broad platform standardization.
New entrants and expanding manufacturers are introducing additional competition, particularly in electrified equipment and cost-competitive conventional product lines. This is not necessarily a threat to incumbents if incumbents respond with clear differentiation in reliability, total cost of ownership, service integration, and data-enabled operations. The more significant risk is complacency in product roadmaps or service models in a market where customer expectations are shifting toward lower emissions, higher utilization, and more predictable operating costs.
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to shape market opportunities and strategic priorities.
One key trend is the acceleration of electrification and alternative-power equipment in selected segments. Serial production of electric articulated haulers and continued development of battery-powered underground loaders indicate that electrification is moving from pilot projects to commercial deployment in specific use cases. The opportunity lies in identifying where energy savings, ventilation reductions, regulatory compliance, and total cost of ownership align to make electric or hybrid equipment economically attractive. The risk is that electrification adoption may be uneven, constrained by charging infrastructure, payload requirements, and operational heterogeneity across sites.
A second trend is the deepening integration of automation and data analytics into equipment and fleet operations. Products that improve load-haul efficiency, automate drilling cycles, or provide near-real-time operational insights are becoming more common. The commercial implication is that value creation is shifting partly from hardware alone to the software, services, and performance assurance that surround it. Manufacturers and service providers that can translate operational data into measurable efficiency gains, reduced downtime, and better maintenance planning are likely to strengthen their competitive position. The uncertainty lies in the pace at which mining companies adopt integrated digital workflows and the degree to which data interoperability standards mature across sites and vendors.
PW Consulting
A third trend is the reconfiguration of supply chains and input cost management in response to policy and material availability. Tariff environments, carbon-related regulation, and steel demand projections suggest that regional cost structures will remain divergent and that material quality constraints may increase the importance of advanced scrap handling and blending. For equipment producers, the opportunity is to build more resilient sourcing, improve material efficiency, and communicate total cost of ownership in ways that account for policy-driven price dynamics. The risk is that input volatility and trade policy uncertainty could compress margins or disrupt delivery schedules if not managed proactively.
These trends converge on a common theme: competitive advantage will depend on the ability to combine product innovation with operational relevance, supply chain discipline, and service differentiation. Markets that are growing at a mid-single-digit rate can still generate significant value reallocation if participants position themselves in the right segments, with the right technology mix, and the right commercial model.
Strategic Recommendations for Decision Makers
For manufacturers, the priority is to align product roadmaps with the operational realities of decarbonization, automation, and total cost of ownership expectations. This means advancing electrified and hybrid options where they can deliver measurable benefits, embedding data and payload optimization into mainstream product lines, and strengthening service and distribution capabilities that reduce downtime and improve customer outcomes. It also means treating supply chain resilience and material efficiency as strategic capabilities rather than procurement details, particularly as input cost cycles and policy environments remain fluid.
For investors, the relevant question is where value is likely to accrue across the equipment and services value chain. Opportunities are probably strongest in companies that can combine scale with differentiated technology in electrification, automation, or underground specialization, and in providers that can capture recurring value through service, parts, and data-enabled performance offerings. Caution is warranted where competitive positioning depends primarily on price without corresponding advantages in reliability, service, or total cost of ownership, especially in an environment where input costs and regulatory dynamics can shift regional competitiveness quickly.
For procurement leaders and mining operators, the strategic imperative is to evaluate equipment decisions through a broader operational lens. This includes comparing conventional and electrified options not just on acquisition cost but on energy consumption, ventilation impact, maintenance patterns, automation potential, and service availability over the asset life. It also includes assessing supplier capabilities in digital integration, remote support, and parts logistics, since these factors increasingly influence uptime and operating economics. Where possible, procurement strategies should incorporate flexibility for fleet mixing, phased electrification, and service models that align supplier incentives with performance outcomes.
For all of these audiences, the value of detailed segmentation data, regional demand patterns, and company-level benchmarking is substantial. Nuanced decisions about product mix, market entry, service expansion, and procurement timing depend on granular insight into where growth is concentrated, which segments are gaining or losing share, and how competitive positioning is evolving across regions and applications. The broader trends outlined here provide direction, but the precision required for investment, product strategy, and sourcing decisions comes from deeper segmentation and company-level analysis.
Strategic positioning in the mining equipment market will increasingly be determined by how effectively organizations translate structural shifts into product, service, and supply chain decisions. The companies that act on these trends with discipline, focus, and operational relevance are best placed to capture value as the market continues its path toward $235.6 billion by 2032.
For detailed analysis of this topic, please visit the official page: Mining Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


