



Forging Presses Market 2026-2032: Inside the 4.3% CAGR and $281M Expansion

Strategic Trends and Commercial Opportunities in the Forging Presses Market
Market Overview and Core Challenges
The global forging presses market has demonstrated resilient, steady growth over the past half-decade, expanding from approximately 145.78 million USD in 2020 to an estimated 208.45 million USD in 2025. This trajectory reflects an underlying compound annual growth rate of 4.3 percent through the forecast period ending in 2032, when revenues are projected to reach 280.9 million USD. The market's expansion is not explosive, but it is structurally supported by fundamental industrial needs: the transformation of raw metal into high-strength, precision-shaped components remains indispensable across transportation, energy, and manufacturing sectors. Growth is being shaped less by cyclical surges and more by a steady accumulation of capacity upgrades, modernization programs, and the gradual migration toward higher-value forming technologies.
A defining characteristic of the current landscape is the widening gap between mature regional markets and those experiencing accelerated industrial investment. North America and Europe continue to anchor significant portions of market value, but Asia Pacific has emerged as the dominant geographic contributor to total market size, reflecting large-scale manufacturing expansion, infrastructure development, and growing domestic demand for forged components across automotive, heavy equipment, and industrial machinery supply chains. Latin America and the Middle East and Africa represent smaller but strategically relevant pockets of activity, often tied to localized industrial policy, resource-based manufacturing, and targeted capital projects. This geographic distribution is reshaping how equipment suppliers think about regional service footprints, localized support, and the balance between standardized offerings and region-specific configuration requirements.
Beneath the growth narrative, three structural challenges are redefining competitive dynamics and forcing strategic recalibration among manufacturers and end-users alike.
Fragmented Value Chains and Regional Capacity Gaps
While aggregate market figures suggest orderly growth, the underlying supply chain remains uneven. Many forging operations face bottlenecks in sourcing high-quality dies, specialized auxiliary equipment, and integrated automation modules. These gaps are not merely procurement inconveniences; they create execution risk for large press installations and complicate delivery timelines for operators trying to align new capacity with production schedules. The result is a market in which vendors capable of bundling presses with dies, handling systems, and control integration are gaining an advantage over those offering machine-only solutions. For end-users, this fragmentation raises the stakes of vendor selection, because the total installed capability of a forging line now depends on more than the press itself.
Energy Intensity and Efficiency Mandates
Forging presses are energy-intensive assets, and environmental as well as operational pressures are pushing the industry toward measurable efficiency gains. Regulatory expectations and internal sustainability targets increasingly require facilities to adopt technologies that deliver substantial reductions in energy consumption relative to conventional systems. This shift is not simply a compliance exercise. It is becoming a financial and operational differentiator, especially in regions where electricity costs, carbon exposure, or industrial energy policies are tightening. Presses that can recover kinetic energy, modulate power delivery more precisely, or integrate hybrid hydraulic-electric architectures are moving from niche innovation to practical necessity for operators seeking lower operating costs and greater production predictability.
Cold Forging Machine Market
Labor Constraints and Automation Pressure
Another persistent challenge is the availability of skilled labor for press operation, die setup, and process supervision. In several major forging markets, workforce constraints are accelerating investment in automation, digital control systems, and tool-less changeover strategies that reduce dependence on specialized manual intervention. This trend is reshaping equipment requirements: buyers are increasingly prioritizing press platforms that can integrate easily with automated material handling, in-process monitoring, and adaptive control logic. At the same time, the transition introduces a new form of complexity. Automation is not automatically plug-and-play, and the value of a press investment increasingly depends on how well it fits within a broader digitized production environment rather than on raw tonnage or stroke speed alone.
Key Drivers Shaping Market Evolution
The market's growth and direction are being pulled by a small set of powerful drivers that reinforce one another. These forces are not isolated trends; they interact to create pressure on legacy designs, reward certain technology pathways, and influence where capital is deployed next.
Mechanical Presses Market
Technology Innovation in Press Architecture and Energy Recovery
One of the most significant enablers of market change is the ongoing refinement of press architectures. Mechanical, hydraulic, and servo-based systems continue to coexist, but the competitive center of gravity is shifting toward designs that combine performance with lower energy input and greater process flexibility. Advanced systems now incorporate energy recovery mechanisms, hybrid drive configurations, and more responsive control architectures that allow manufacturers to run higher stroke rates while reducing waste heat and idle power draw. These innovations are not merely engineering achievements; they have commercial implications. They expand the range of applications that can be economically served by a single press platform, improve consistency in closed-die and open-die operations, and help manufacturers justify capital expenditure in an environment where operating cost and sustainability performance are under closer scrutiny. Recent large-scale installations illustrate how these technologies are moving from pilot demonstrations into production use. A major global press supplier recently began production on what is described as the world's largest forging press equipped with a kinetic energy recovering system, signaling that energy recovery is being engineered into high-capacity assets rather than treated as a retrofit concept. Around the same time frame, another delivery highlighted a full hybrid hydraulic-electric press achieving meaningful energy reduction at an automotive facility, reinforcing the point that hybrid drive strategies are becoming commercially relevant for Tier-1 production environments.
Policy, Regulation, and Industrial Modernization Directives
Policy and regulatory frameworks are increasingly shaping technical expectations and investment timing. Energy efficiency mandates are pushing forging operations to incorporate technologies that deliver substantial consumption reductions compared with conventional systems, and these requirements are influencing both new equipment selection and retrofit strategies. In parallel, industrial modernization programs in several regions are encouraging capacity upgrades that emphasize automation, digital traceability, and process consistency. Forging press suppliers are responding by designing products that align more closely with compliance-related performance targets while also supporting broader modernization goals such as reducedManual intervention, better repeatability, and higher throughput stability. This regulatory and policy context matters because it affects not only whether a press is purchased, but what specifications are considered acceptable in the first place, and how quickly operators are willing to replace or augment older equipment.
Demand-Side Shifts in Automotive and Aerospace Production
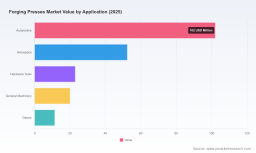
Demand patterns from end-use sectors remain central to market direction. Automotive production continues to exert strong pull on forging demand, driven by the need for structural components, safety-critical parts, and lightweighting initiatives that still rely on forged geometries for strength-to-weight performance. Aerospace and related high-integrity applications also contribute meaningfully, where material properties, tolerance control, and process reliability are especially important. These sectors share a common orientation: they are not simply buying tonnage; they are buying predictable quality, repeatable process windows, and the ability to integrate forging into broader automated production flows. As a result, demand-side behavior is shifting toward suppliers and press configurations that can support higher volumes without sacrificing control, and that can demonstrate clear pathway to lower scrap, reduced rework, and tighter process adherence. The commissioning of a fully automatic closed-die forging press at a chain manufacturing operation in China illustrates how high stroke-rate automation is being applied to production environments that prioritize throughput and consistency, a pattern that is likely to become more common as manufacturers pursue cost efficiency and capacity utilization.
Supply Chain Restructuring and Cost Dynamics
Cost structures across the forging ecosystem are being reshaped by material usage patterns, labor economics, and the broader push toward integrated solutions. Carbon steel remains the dominant raw material basis in forging due to its balance of cost and strength, which keeps material sourcing and scrap management central to operational economics. At the same time, labor shortages in forging operations are encouraging greater reliance on automated press systems and digital controls to reduce personnel constraints. Together, these factors are nudging the market toward a model in which total cost of ownership, uptime, and process automation are weighed more heavily than initial purchase price. For suppliers, this means that value propositions are increasingly tied to integration, service responsiveness, and the ability to help customers manage energy, labor, and throughput simultaneously. For buyers, the implication is that the most competitive offer may not be the one with the lowest headline price, but the one that reduces operational drag over the asset's life cycle.
Competitive Landscape and Leading Strategies
The forging press market is competitive, but it is not perfectly consolidated. The top three competitors hold roughly 30 percent of market share, while the top five account for approximately 35 percent. This concentration suggests a landscape in which scale and reputation matter, yet substantial room remains for specialized players, regional experts, and firms that differentiate through technology, application focus, or integration capability. The competitive field is populated by a mix of established Western manufacturers, European technology leaders, Japanese equipment developers, and U.S.-based specialists serving a range of mechanical, hydraulic, warm-hot, and servo press applications.
Strategic Positioning Among Leading Players
A useful way to read the competitive field is by the strategic emphasis each group brings to the market. Some manufacturers have carved out strong identities around custom hydraulic solutions for open-die and closed-die applications, positioning themselves as flexible problem-solvers for customers with non-standard tonnage, configuration, or process requirements. These firms compete on engineering responsiveness, application-specific design, and the ability to adapt a press to the customer's production intent rather than selling a purely standardized machine. Other players focus on standard and custom hydraulic hot forging presses with high tonnage capabilities, appealing to customers who need large-scale forming capacity and want a defined technical baseline with room for customization. Still others extend their portfolios across mechanical, hydraulic, and servo technologies, often as part of broader industrial groups, which allows them to offer cross-technology guidance and to match press type to the production rhythm and process constraints of a given application. In parallel, some suppliers emphasize mechanical and servo press solutions for high-volume production, where speed, repeatability, and integration with automated lines are especially valuable. There is also a meaningful segment of firms that supply forging presses and related industrial forming equipment while positioning themselves as practical partners for metal forming operations, often competing on responsiveness, service support, and regional availability. Finally, a separate tier of custom hydraulic and servo press specialists supports extremely large forming requirements, giving high-tonnage customers access to tailored solutions that go beyond common commercial configurations.
The strategic takeaway is that competition is increasingly multidimensional. While tonnage, brand heritage, and machine class still matter, differentiation is being redefined by how well a vendor can align press technology with energy performance, automation readiness, application-specific process control, and delivery of a complete forming solution. The companies that appear best positioned are those that can articulate a clear technical identity while still offering enough flexibility to meet varying customer requirements across regions and end-use sectors.
PW Consulting
Recent Developments as Indicators of Direction
Recent activity among leading equipment suppliers offers a window into where the market is heading. One of the most notable signals is the growing emphasis on energy recovery and hybrid drive technologies in flagship installations. The start of production on a world-scale forging press featuring kinetic energy recovery, and the delivery of a hybrid hydraulic-electric press with documented energy reduction, both point to a direction in which efficiency is being designed into major assets at the engineering level rather than added later. Another important indicator is the successful commissioning of a fully automatic closed-die forging press achieving high stroke rates at a manufacturing site in China, which reflects the market's accelerating interest in automation, throughput maximization, and integrated closed-die forming capability. Participation in industry technical conferences and exhibitions also remains relevant, as it signals continued investment in customer engagement, technology demonstration, and ecosystem visibility. Taken together, these developments suggest that the competitive dialogue is shifting from machine capability alone toward integrated performance, energy behavior, automation compatibility, and the ability to execute complex installations in demanding production environments.
Market Evolution: Consolidation, Fragmentation, and New Entry
Looking ahead, the competitive structure is likely to evolve along several paths at once. Consolidation pressure exists at the top, where larger, globally capable suppliers can leverage breadth of technology, after-sales networks, and the ability to serve multinational customers with consistent standards. At the same time, fragmentation persists at the regional and application level, where local expertise, shorter decision cycles, and specialized configurations can create durable niches. New entry and repositioning are also possible, especially for firms that bring credible expertise in servo drive technology, energy-efficient press design, or integrated automation packages. The market is not simply moving toward a winner-takes-all structure; it is moving toward a layered competitive environment in which global scale, regional presence, and technology differentiation each create distinct forms of advantage.
Future Outlook and Strategic Opportunities
Based on current market data and visible technology and demand trajectories, three trends stand out as particularly important for the next three to five years.
Efficiency as a Core Buying Criterion
Energy performance is expected to move from an important attribute to a core buying criterion for many forging press purchases. The combination of efficiency mandates, operating cost pressure, and demonstrated hybrid and energy-recovery solutions is likely to make energy behavior a more explicit part of procurement evaluation. For commercial strategy, this creates opportunities for suppliers that can quantify energy savings, demonstrate compatibility with existing facility constraints, and offer solutions that do not sacrifice forming performance. It also creates an opportunity for operators to align equipment selection with broader cost-reduction and sustainability goals, especially where press replacements or major upgrades are already on the horizon. The uncertainty here lies in how quickly different regions and customer segments translate efficiency expectations into purchasing behavior, and whether standardized efficiency benchmarking becomes common enough to simplify comparisons across competing press technologies.
Automation-Integrated Press Platforms
A second major trend is the continued migration toward press platforms designed for integration with automated material handling, in-process monitoring, and adaptive control. The push comes from labor constraints, throughput ambitions, and the desire for more consistent process outcomes. Over the next several years, the most attractive press solutions are likely to be those that can function as part of a coordinated production system rather than as isolated mechanical assets. This opens commercial opportunities for vendors that can offer smoother integration pathways, clearer automation interfaces, and support for faster changeovers and lower manual dependency. For end-users, the opportunity is to reduce variability and increase asset utilization, but the risk is that automation ambition outpaces the readiness of the surrounding process, maintenance, and skills infrastructure. The market will likely reward customers and suppliers that treat automation as a system-level decision, not just a machine feature.
Regional Demand Divergence and Application Specialization
A third trend is the widening of regional demand profiles and the corresponding value of application specialization. While the market as a whole is growing at a moderate pace, demand intensity varies by region and by end-use sector. Areas experiencing broad industrial expansion are likely to drive higher volumes of standard and semi-custom equipment demand, while more mature markets may focus on replacement, modernization, and higher-value specialized forming capabilities. In parallel, applications in automotive, aerospace, and high-integrity industrial components are likely to continue supporting demand for presses that can deliver strong process control and repeatable quality. This environment favors suppliers and service strategies that can tailor offerings to regional realities and application-specific requirements. It also creates a risk: companies that rely too heavily on a single market or a single application may be exposed if local investment cycles shift or if sector demand patterns change faster than expected.
Actionable Guidance for Decision Makers
For manufacturers evaluating forging press strategy, the most important move is to align equipment selection with the operational priorities that will matter most over the asset's life. That means weighing energy performance, automation compatibility, service availability, and application fit alongside tonnage and price. Manufacturers should also consider whether a press platform can support future needs such as hybrid drive upgrades, better process monitoring, or integration with material handling without requiring a full replacement later. Suppliers and producers that take a total-cost and process-consistency view are more likely to emerge with installations that perform well under real production conditions rather than only under ideal specification conditions.
For investors, the opportunity lies in identifying the segments where technology differentiation, automation readiness, and regional demand alignment create durable advantages. The market's moderate overall growth does not mean uniform opportunity; value is likely to concentrate around vendors and end-users that can demonstrate measurable efficiency gains, serve high-integrity applications, or integrate press assets into broader automated production systems. Investors should also watch for signs of competitive repositioning around energy recovery and hybrid technologies, since these areas appear to be moving from demonstration to deployment. As with any industrial equipment sector, execution risk, installation complexity, and regional demand variability should be factored into any opportunity assessment.
For procurement and operations leaders, the priority is to treat press procurement as a systems decision. Transparency around energy consumption, automation interfaces, maintenance demands, and changeover complexity should be part of the evaluation process, not optional add-ons. Procurement teams should also seek evidence that proposed solutions have been validated in similar application environments, and they should ensure that vendor capabilities extend beyond equipment supply to include support for integration, commissioning, and ongoing performance optimization. In a market where operating constraints and workforce realities increasingly shape outcomes, the strongest purchasing decisions are likely to be those that balance technical capability with long-term operational practicality.
The forging presses market is not defined by sudden disruption, but by a steady accumulation of technology, efficiency, automation, and regional demand shifts that are reshaping what buyers expect and what suppliers must deliver. For decision makers who need to move beyond high-level market size figures and understand segment-specific dynamics, competitive positioning, and application-driven demand patterns, deeper market intelligence can make the difference between a reasonable capital plan and a strategically robust one. More detailed breakdowns, company-level profiles, and segment-focused scenario analysis are available in the full research report, where the broader macro context is translated into actionable detail for specific business decisions.
For detailed analysis of this topic, please visit the official page: Forging Presses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


