



Rupture Disc Market: Why the 3.7% CAGR Trajectory Signals Strategic Shifts for 2026

Strategic Trends and Commercial Opportunities in the Rupture Disc Market
Navigating a Mature but Evolving Safety-Critical Segment
The global rupture disc market reflects the steady, requirement-driven nature of pressure relief equipment across process industries. Measured against a 2025 base year and projected through 2032, the market demonstrates a composite annual growth rate of 3.7%, expanding from an estimated 678.2 million USD in 2025 to 874.6 million USD by 2032. Historical movement between 2020 and 2025 shows moderate but consistent expansion, with revenue climbing from 597.5 million USD to 678.2 million USD over the period. This trajectory indicates a market where demand is anchored by regulatory requirements, operational safety mandates, and gradual capacity additions rather than volatile cyclical spikes.
When viewed across the historical window, the pattern underscores resilience. The 2020-2025 sequence moved through a brief contraction in 2021 before recovering through 2022 and 2023, then stabilizing near 646 million USD in 2024 before reaching the 2025 mark. The forecast horizon suggested a continued climb toward 722.27 million USD in 2026, 752.04 million USD in 2027, and 774.06 million USD in 2028, before a slight plateau near 773.96 million USD in 2029. Growth resumes afterwards, advancing to 796.12 million USD in 2030, 841.71 million USD in 2031, and 874.6 million USD in 2032. This shape implies that the segment will experience a transitional period around the late 2020s, likely shaped by order timing, replacement cycles, and the uneven rhythm of capital projects across regions.
Market concentration further clarifies the operating environment. The top three companies account for roughly 49.5% of revenue, while the top five reach about 65.2%. This distribution reflects a landscape where established manufacturers hold meaningful share through technical credibility, application-specific product lines, and long-standing customer relationships in process safety. At the same time, the space is not dominated by a single entity, leaving room for differentiation through specialization, service models, and regional execution.
Key Challenges and Inflection Points
The rupture disc market is entering a phase where growth is increasingly shaped by product suitability, qualification rigor, and the timing of end-use capital spending rather than by broad volume expansion alone. Several structural challenges stand out.
-
Qualification intensity and testing expectations are rising. Pressure relief components are increasingly expected to demonstrate traceable raw materials, lot-level qualification testing, and burst tolerance performance that exceeds baseline code requirements. Suppliers that cannot consistently document cycle life and performance consistency face greater friction in regulated and sanitary applications.
-
Demand timing is uneven across industries. While oil and gas, chemicals, and pharmaceuticals continue to anchor core demand, project pipelines differ by region and by budget cycle. Replacement activity can cushion downturns, but new installations often lag when capital expenditure decisions are delayed.
-
Segment differentiation is becoming a commercial necessity. The market spans metallic, graphite, and non-metallic rupture discs, each with distinct performance profiles for pressure relief, corrosion resistance, temperature exposure, and cleanability. Customers are selecting based on process conditions rather than commodity pricing, which pushes suppliers to align product design more closely with application-specific requirements.
These pressures create a market where success depends less on broad reach and more on technical fit, documentation reliability, and the ability to reduce installation or compliance friction for buyers.
Abrasive Disc Market
Core Drivers Shaping Market Direction
Technical Innovation and Application-Specific Engineering
Product development is increasingly oriented toward higher performance under demanding conditions and easier integration into complex systems. Recent moves to expand rupture disc families for larger sizes and high-performance overpressure protection show how manufacturers are targeting installations where pressure relief must be both reliable and scalable. Equally notable is the push toward assembly-based designs that simplify installation and improve process safety. Such products are not simply incremental variations; they reduce integration risk and support faster commissioning, which matters in environments where downtime is costly and safety validation is strict.
Innovation is also visible in how manufacturers are addressing material and performance requirements simultaneously. Metallic and graphite rupture discs are being positioned with emphasis on traceable sourcing and in-house lot qualification testing that surpasses standard code expectations for cycle life and burst tolerance. In high-compliance segments, this level of documentation is becoming part of the value proposition rather than a back-office requirement.
Regulatory and Standardization Pressure as a Demand Catalyst
Regulatory expectations and industry standards continue to reinforce demand for verified, repeatable pressure relief solutions. In pharmaceutical and biotechnology environments, sanitary rupture discs are expected to support traceability, cleanability, and sterilization, often aligned with recognized standards such as ASME BPE, USP Class VI, and 3A. In food and beverage processing, hygienic designs are expected to be compatible with cleaning-in-place and sterilization-in-place conditions while resisting vacuum exposure. These expectations push buyers toward products that can demonstrate compliance consistency across lots and operating conditions.
At the same time, certain materials are gaining traction because they align with specific process challenges. Graphite rupture discs, for example, are valued in some corrosive media applications due to temperature-independent material behavior and conformity expectations in regulated environments. This does not mean any single material dominates across all use cases; instead, it highlights that buyers are matching material properties to process environments more deliberately than in the past.
Demand-Side Shifts in Process Safety and Sanitary Applications
End-user demand is being shaped by a combination of operational safety priorities and the expanding requirements of hygienic processing. In chemical plants and oil and gas facilities, pressure relief remains a core function tied to equipment integrity and operational risk management. In pharmaceutical, biotechnology, and food-related applications, the emphasis shifts toward preventing contamination, enabling sterilization, and maintaining cleanliness without sacrificing overpressure protection.
This dual demand profile creates divergent purchase drivers. Process industries prioritize reliability, compatibility with harsh conditions, and long service life. Sanitary applications emphasize cleanability, compliance traceability, and compatibility with cleaning and sterilization routines. As a result, the same product category serves fundamentally different selection criteria depending on the end market, which diversifies the competitive battlefield.
Supply-Side and Cost Structure Considerations
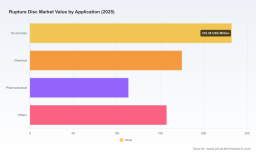
Cost dynamics in this market are closely linked to material selection, manufacturing precision, and qualification overhead. Metallic rupture discs make up the largest portion of the revenue base, with graphite and non-metallic products forming substantial but smaller portions of the mix. This distribution matters because material choice affects not only performance but also sourcing complexity, testing requirements, and pricing strategy.
Suppliers that invest in raw material traceability and in-house testing may face higher operational burdens, but they also reduce the risk of qualification failures and customer rejections. Over time, this can translate into stronger repeat business in applications where documentation and consistency are decisive. Conversely, cost pressures may intensify where buyers treat rupture discs as interchangeable unless a supplier can clearly justify performance advantages or compliance benefits.
Competitive Positioning and Strategic Differentiation
The competitive landscape is defined by manufacturers that have built strong reputations around specific application strengths, product architectures, and compliance-oriented designs.
Some manufacturers have concentrated on sanitary and hygienic rupture disc solutions designed for pharmaceutical, biotech, food, and beverage environments. These offerings emphasize reverse-acting and forward-acting designs, compatibility with cleaning and sterilization processes, and adherence to recognized standards. The value proposition here is not simply pressure relief; it is repeatable cleanliness, sterilization readiness, and documentation that supports regulated operations.
Other manufacturers have broadened their footprint across chemical, pharmaceutical, extrusion, and food industries with both metallic and graphite products, often spanning reverse-acting, forward-acting, sanitary, and ultra-low or bi-directional applications. This type of positioning supports a strategy of cross-industry reach, where customers in multiple process environments can source from a single supplier with a wide performance envelope.
There are also manufacturers focused on engineered, high-precision rupture discs and pressure relief components for more demanding or specialized systems. In these cases, differentiation comes from precision manufacturing, custom engineering support, and the ability to integrate rupture discs into broader pressure relief solutions.
Geographically, the field also includes internationally based manufacturers serving industrial pressure relief applications with dedicated product series. These companies contribute to a market structure where regional execution, product line breadth, and technical support can be as important as headline brand recognition.
Recent Activity as a Window into Strategic Priorities
Recent product activity among leading manufacturers points to a clear strategic emphasis on performance range, installation efficiency, and line expansion. One notable direction has been the extension of established rupture disc lines into larger sizes to address higher-demand industrial applications. This suggests that manufacturers are responding to customers who need overpressure protection in more demanding configurations without abandoning proven design principles.
Another important move has been the launch of cartridge-based rupture disc assemblies intended to simplify installation and improve process safety. This reflects a broader shift toward reducing integration complexity, which is particularly valuable in facilities where maintenance access, replacement time, and installation accuracy directly affect operational continuity.
In parallel, the introduction of new rupture disc families for high-performance overpressure protection shows that suppliers are not relying on legacy portfolios alone. Instead, they are expanding into product sets designed to cover a wider performance spectrum, which can help capture demand from customers seeking a more consistent platform across multiple installations or process conditions.
Together, these developments indicate competition is increasingly being fought on the basis of application coverage, integration convenience, and validated performance rather than basic presence in the category.
Market Structure and Evolution Patterns
The current concentration pattern suggests a market that is consolidated enough to reward scale and technical credibility, yet open enough to allow differentiation by specialization. Companies with strong positions in sanitary or hygienic segments can outperform in regulated environments even if they are not the largest overall. Similarly, suppliers with broad material coverage and engineering support can build relevance across multiple industries by reducing the need for customers to manage several sources for different rupture disc types.
Looking ahead, the structure may evolve through a combination of selective consolidation and continued segmentation. Larger players may strengthen their position by broadening product lines or acquiring specialized capabilities, especially where compliance, testing, and documentation create high barriers to switching. At the same time, smaller or more specialized manufacturers can persist by serving niche performance requirements, regional demand, or application-specific customization that larger platforms do not prioritize.
For buyers, this environment often translates into a trade-off between simplified sourcing and best-fit performance. For suppliers, it means that competitive advantage is increasingly tied to how well a product platform aligns with customer qualification needs, installation constraints, and process conditions.
Future Outlook: Three Trends to Watch
Trend 1: Compliance and Documentation as Commercial Gateways
Over the next several years, traceability, qualification testing, and standards alignment are likely to become even more central to purchasing decisions, especially in pharmaceutical, biotech, food, and beverage applications. Buyers may increasingly treat documented consistency as a prerequisite rather than a bonus. This creates an opportunity for suppliers that already operate with rigorous raw material controls and lot-level testing, and a challenge for those that cannot match the same level of evidence when customers compare options.
The commercial implication is clear: in regulated segments, product performance and product documentation are becoming inseparable. Companies that can streamline qualification, reduce validation burden, and maintain consistent performance across lots are better positioned to secure long-term preference.
Trend 2: Platform-Based Product Strategies and Integration Convenience
A second trend is the move toward product families and assemblies that make selection, installation, and replacement more straightforward. Expanding line sizes and introducing cartridge-style designs are examples of how manufacturers are trying to reduce friction in the field. If this direction continues, buyers may value platform consistency across units and sites because it simplifies inventory planning, maintenance, and engineering review.
This trend opens commercial opportunities for suppliers that can offer a coherent range rather than isolated point products. It also raises the stakes for those whose portfolios are fragmented or difficult to standardize across applications.
Trend 3: Material Selection Becoming More Context-Specific
The market is unlikely to converge on a single material solution. Instead, metallic, graphite, and non-metallic rupture discs are expected to retain distinct roles based on pressure requirements, corrosion exposure, temperature conditions, and sanitary needs. The more important shift is that selection may become more deliberate, with buyers matching material characteristics to process environments rather than defaulting to a standard choice.
PW Consulting
This creates opportunity for manufacturers that can clearly articulate when and why a given material is appropriate, particularly in corrosive or temperature-sensitive services. It also suggests that sales and technical support will matter as much as the product itself, because the right choice often depends on operating conditions that differ from one installation to the next.
Risks and Uncertainties
Despite a generally constructive growth outlook, several uncertainties bear watching. Capital expenditure timing in oil and gas and chemical end markets can delay new installations and shift demand toward replacement cycles. Regulatory interpretations and customer qualification expectations can also evolve, changing the documentation or performance thresholds required for approval. Finally, raw material sourcing and manufacturing quality control remain sensitive points; any inconsistency in materials or testing can quickly affect customer confidence in safety-critical applications.
In addition, the late-2020s plateau visible in the forecast suggests that growth may not be linear. Periods of stabilization can emerge as project timing, replacement cycles, and regional demand patterns interact. Companies that rely too heavily on a single end-use sector or a narrow material set may feel those pauses more acutely than diversified competitors.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
-
Align product roadmaps with the applications where compliance documentation and performance consistency matter most. In sanitary and regulated environments, the ability to prove traceability and repeatable burst tolerance can be as influential as the headline design features.
-
Reduce installation and integration friction wherever possible. Cartridge assemblies, broader size ranges, and clearer platform consistency can make a product line easier to specify, deploy, and maintain, which strengthens customer preference over time.
-
Treat material strategy as application strategy. Rather than competing on a single material across all use cases, sharpen the message around where metallic, graphite, or non-metallic rupture discs are the best fit and support that claim with technical evidence.
For Investors and Strategic Planners
-
Focus on suppliers that combine application specialization with credible qualification practices. In a market where the top five companies hold a majority share, durable advantage often comes from segments where technical barriers and documentation requirements limit easy substitution.
-
Watch for platform expansion and consolidation signals. Product line broadening, assembly-based designs, and moves into larger-scale industrial protection can indicate where manufacturers are trying to capture more share per customer and reduce churn.
-
Consider how end-use timing affects revenue visibility. Because demand is influenced by project cycles in oil and gas, chemicals, and pharmaceuticals, diversification across applications and regions can reduce exposure to localized capital spending delays.
Rubber Diaphragm Market
For Procurement and Operations Leaders
-
Evaluate rupture disc suppliers on total qualification burden, not just unit price. In safety-critical or sanitary applications, consistency of documentation, testing evidence, and standards alignment can reduce risk and speed approval.
-
Standardize where possible, but preserve application fit. A coherent product platform across sites can simplify maintenance and inventory, but it should still be matched to pressure, temperature, corrosion, and cleanability requirements.
-
Request clear evidence of lot-level quality control and material traceability, especially where corrosive media, sterilization conditions, or stringent compliance expectations are involved. This helps ensure that the selected product performs consistently across installations.
Why Deeper Intelligence Matters Now
The rupture disc market is not undergoing a sudden disruption, but it is becoming more demanding in the ways that matter most to commercial decisions: qualification rigor, application fit, integration convenience, and documentation reliability. In that environment, general market awareness is useful, but segment-level clarity is what supports confident product planning, sourcing choices, and investment prioritization.
Detailed segmentation data, regional demand patterns, material and application splits, company-level positioning, and procurement-relevant benchmarks can sharpen these decisions considerably. For teams evaluating where to invest, which applications to prioritize, and how to compare suppliers beyond price, a more granular view of the market can help translate broad trends into actionable next steps. Readers seeking that level of detail can find it in the full PW Consulting report, which extends the analysis into deeper segmentation, competitive detail, and tailored decision frameworks.
For detailed analysis of this topic, please visit the official page: Rupture Disc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


