



Tire Changers Market 2026: Why 6.8% CAGR and Asia Pacific’s Scale Shift Everything

Beyond the Service Bay: Strategic Shifts Reshaping the Tire Changers Market Through 2032
Market Trajectory: From Incremental Growth to Structural Expansion
The global tire changers market is undergoing a transformation that extends well beyond routine equipment replacement cycles. Valued at approximately 1,471 million USD in 2025, the market has expanded at a steady pace since 2020, when it stood near 1,135 million USD. This growth reflects not only broader automotive service activity but also a fundamental shift in how service centers, fleets, and independent shops approach wheel maintenance efficiency, safety compliance, and operational throughput.
Projecting forward through 2032, the market is expected to surpass 2,300 million USD, supported by a compound annual growth rate of 6.8 percent. The trajectory suggests a market that is maturing but still possesses meaningful expansion headroom, particularly as regional service infrastructure develops, vehicle fleets age, and new equipment configurations address increasingly complex rim and tire profiles. The growth is not uniform across all segments, however, and the divergence in adoption patterns points to strategic opportunities for players who can align product capabilities with evolving service demands.
Worldwide Tool Changers Market
Core Challenges at the Inflection Point
Several interconnected challenges are redefining how tire changer manufacturers, distributors, and end users navigate the market. These are not temporary friction points but structural shifts that will influence equipment selection, pricing dynamics, and competitive positioning for years to come.
First, tightening safety and operational compliance requirements are reshaping procurement criteria. Vehicle maintenance environments, particularly those supporting commercial fleets and heavy-duty operations, face heightened expectations around machine guarding, turntable accessibility, and workstation hazard mitigation. Industry guidance continues to emphasize that equipment must meet or exceed established safety standards to reduce compliance exposure and minimize unplanned downtime. For service operators, this elevates the importance of equipment that integrates protective design features without compromising speed or ease of use.
Second, shifting trade policies and import exposure are introducing volatility into equipment sourcing and cost structures. Recent policy movements have placed renewed attention on the origin of automotive service equipment, affecting pricing assumptions and supply continuity for buyers who rely on cross-border procurement. The change is prompting service businesses and manufacturers alike to reassess supply chain dependencies, localize component sourcing where feasible, and evaluate total cost of ownership rather than upfront price alone.
Third, the evolving tire and wheel landscape is placing new technical demands on change equipment. As service centers encounter wider variety in rim diameters, lower-profile tires, and mixed passenger and commercial workloads within the same bay, equipment that once performed adequately for generalized use is increasingly expected to handle more specialized applications. This is driving interest in flexible mount configurations, enhanced bead-breaking performance, and designs that reduce manual force requirements while maintaining operator control.
Key Drivers Accelerating Market Evolution
Technology Innovation and Equipment Differentiation
Innovation in tire changer design is moving beyond incremental feature additions toward more integrated, ergonomic, and application-specific solutions. A clear trend is the development of hybrid mount systems that blend the speed and consistency of automatic or semi-automatic operation with the adaptability of leverless or swing-arm configurations. These systems address a practical service center challenge: reducing changeover time while limiting tire and rim damage risk on challenging assemblies.
PW Consulting
Recent equipment introductions highlight this direction. One major engineering provider expanded its table-top and center-clamp offerings with models featuring hybrid leverless mount heads, enhanced torque capabilities, and integrated inflation systems designed to streamline the full change cycle. Additional center-clamp and swing-arm combinations have focused on merging the advantages of both configurations, giving operators more flexibility when working with difficult bead seats or non-standard rim geometries. In parallel, other manufacturers have refreshed product platforms with emphasis on shop efficiency, stronger jaw configurations for commercial wheel sizes, and simplified controls that support faster operator training.
The practical implication is that equipment performance is increasingly being measured by repeatability, operator safety, and the ability to handle a broader range of tire and wheel profiles without frequent re-tooling or manual intervention. For manufacturers, this creates a competitive environment where differentiation stems less from basic functionality and more from how well the equipment fits specific shop workflows.
Regulatory and Safety Standards as a Market Shaping Force
Regulatory expectations are becoming a more prominent element of equipment selection and procurement strategy. Safety guidelines relating to machine guarding, turntable edge protection, and workstation hazard control continue to influence how service centers evaluate tire changers, especially in commercial and fleet maintenance environments. Equipment that supports compliance through integrated guarding, clear operational zones, and reduced exposure to pinch or trip hazards is gaining preference in risk-conscious buying environments.
This regulatory emphasis interacts with operational realities in fleet service. Out-of-service criteria and downtime sensitivity make reliability and consistency important procurement considerations, not only from a safety standpoint but also from a logistics perspective. When maintenance interruptions carry consequences for fleet availability, equipment that supports predictable cycle times and reduces manual variability becomes more valuable. In this context, regulatory alignment is not simply a compliance checkbox; it is increasingly part of a broader operational resilience discussion.
Demand-Side Shifts in Service Behavior
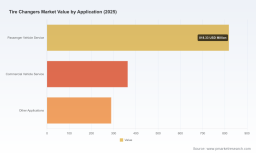
Service behavior is shifting on both the passenger and commercial sides, though for different reasons. Passenger vehicle service demand continues to benefit from growing vehicle parc activity, seasonal tire change programs, and a broader emphasis on preventive maintenance. At the same time, commercial vehicle service demand is being shaped by fleet maintenance requirements, uptime pressures, and the need to service larger and sometimes mixed wheel configurations efficiently.
These demand patterns are influencing the relative attractiveness of different equipment categories. Shops handling higher passenger vehicle volumes tend to prioritize fast change cycles, consistent mounting performance, and space-efficient equipment footprints. Commercial-focused operators place greater weight on robustness, bead-breaking capability, and compatibility with heavier or larger-diameter wheels. As service centers increasingly manage blended workloads, demand is rising for equipment that can adapt across these contexts without forcing separate line investments for each application type.
Cost Structure and Supply Chain Realignment
Cost dynamics are being reshaped by both input material considerations and broader sourcing strategy changes. Equipment that relies heavily on durable structural materials such as steel for frames and load-bearing components presents a different cost and longevity profile than lighter or fully imported alternatives. In an environment where procurement teams are more attentive to lifecycle durability, serviceability, and supply continuity, the emphasis is shifting toward equipment that offers predictable maintenance demands and resistance to premature wear.
At the same time, sourcing complexity is encouraging manufacturers and distributors to think more strategically about regional production footprints, component availability, and the balance between import dependency and localized assembly or fabrication. For buyers, this translates into greater scrutiny of supplier reliability, spare parts access, and the longer-term economic implications of equipment selection beyond the initial purchase price.
Competitive Landscape: Positioning, Differentiation, and Structural Change
The tire changers market features a mix of established manufacturers with strong regional presence, specialized equipment providers, and firms leveraging broader automotive service portfolios. Competitive advantage is increasingly defined by product versatility, workflow integration, and the ability to support compliance and durability expectations while maintaining effective pricing and service support.
One U.S.-based engineering company has continued to consolidate attention around its tire changer line by introducing multiple product updates within a short period. Its recent launches have emphasized hybrid leverless mount heads, enhanced torque delivery, integrated inflation systems, and lower locking disc configurations. These updates illustrate a strategy centered on expanding the capability range of core platforms while addressing difficult tire and rim combinations that can slow traditional change processes. By positioning its products as adaptable across table-top, center-clamp, and swing-arm use cases, the company is reinforcing a message of workflow flexibility for service centers that need to accommodate varied tire and wheel profiles.
Another U.S. manufacturer has taken a different but complementary approach, emphasizing domestically designed and built equipment with strong structural component choices and feature enhancements aimed at commercial wheel sizes. Recent updates have included stronger jaw options for larger commercial diameters, refreshed shop-facing branding, and product presentations tied to professional service audiences. The emphasis on steel-intensive construction and application-specific jaw configurations signals a focus on durability and commercial service demands, an angle that resonates with buyers concerned about heavy usage cycles and long equipment life.
Additional competitors reflect the breadth of the landscape. Some firms concentrate on car, truck, and motorcycle applications with accessible professional-grade solutions, often pairing tire changers with complementary shop equipment to deliver more complete service bay packages. Others, particularly in Europe, have built reputations around integrated wheel service systems, combining tire changers with balancers and alignment-related equipment to support full-service workflows. Chinese manufacturers have also continued to participate in the market with automatic and touchless-style designs that target efficiency and specialized mounting needs. Italian equipment makers remain notable for superautomatic and standard configurations directed at garages and service centers, while other established suppliers focus on variable-speed direct-drive designs or rim-clamp models tailored to repair shop use.
The overall competitive structure shows moderate concentration, with leading firms holding meaningful share while leaving substantial room for regional specialists and application-focused entrants. This fragmentation is likely to persist in the near term, but the nature of competition is shifting. Rather than competing only on basic equipment capability, manufacturers are increasingly differentiating through product families that span multiple mounting styles, integrated shop-system positioning, and feature sets that respond directly to compliance, durability, and operator efficiency expectations.
Market evolution is also being shaped by the interplay between established players and new product introductions that blur traditional category lines. Hybrid configurations, enhanced commercial wheel compatibility, and integrated shop efficiency features suggest that the boundary between fully automatic, semi-automatic, and manual-oriented equipment is becoming more flexible in practice. Buyers are increasingly evaluating platforms based on the operational outcomes they enable rather than strict equipment classification.
Tire Market
Future Trends Shaping the Next Three to Five Years
Trend One: Convergence Toward Flexible, Application-Responsive Platforms
Over the next several years, demand is likely to continue favoring tire changers that can handle a wider mix of tire and wheel profiles without requiring multiple dedicated machines. Hybrid mount systems, adaptable jaw or duckhead configurations, and designs that support both passenger and light commercial use will become increasingly important in mixed-workload service environments. This trend creates opportunity for manufacturers that can offer scalable platforms and for service centers that can consolidate equipment while expanding service coverage. It also introduces a risk: platforms that promise flexibility but sacrifice reliability, ease of training, or maintenance simplicity may struggle to retain buyer confidence.
Trend Two: Compliance, Safety, and Uptime as Core Purchase Criteria
Safety and regulatory alignment will continue moving from a secondary consideration to a primary procurement driver, especially in commercial fleet service and higher-volume maintenance environments. Equipment selection will increasingly account for guarding design, workstation layout, operator exposure reduction, and consistent cycle performance that supports downtime management. The commercial opportunity lies in products and service packages that frame compliance and uptime as integrated benefits rather than separate features. The uncertainty lies in how standards, inspection practices, and enforcement expectations may further evolve, which could change the relative weight of specific equipment attributes over time.
Trend Three: Regional Sourcing, Cost Discipline, and Lifecycle Value Thinking
As equipment buyers become more attentive to sourcing exposure, long-term durability, and total cost of ownership, market dynamics will favor suppliers that can articulate clear lifecycle value and maintain predictable parts and service support. Domestic or regionally anchored production strategies, durable structural design, and transparent maintenance requirements may gain relative advantage in segments where operational continuity matters most. At the same time, import-dependent supply paths may face continued pressure from policy changes and buyer risk tolerance. The strategic opportunity is for manufacturers and distributors to build clearer value narratives around durability, service access, and supply reliability, while buyers benefit from more disciplined equipment evaluation frameworks.
Strategic Implications for Decision Makers
For manufacturers and product leaders, the near-term priority is to strengthen platform versatility without diluting reliability. Product strategies that combine hybrid mounting options, commercial wheel compatibility, and clear operator-safety design are well positioned to address the converging demands of passenger and commercial service environments. Equally important is the ability to support these products with dependable parts availability, service guidance, and a value proposition that extends beyond initial pricing. Companies that can connect product features to measurable shop outcomes—reduced change time, lower operator fatigue, fewer compatibility limitations, and stronger compliance support—will have a stronger footing in an increasingly outcome-driven buying environment.
For investors and strategic partners, the market offers opportunity in segments where durability, compliance alignment, and mixed-application flexibility are gaining weight. Attention should be directed toward manufacturers with coherent product roadmaps, clear regional or supply-chain positioning, and the ability to serve both specialized and broad-service customers. Investment theses should account for the possibility that trade-policy exposure, raw material dynamics, and shifting procurement preferences may alter competitive advantages over time, making supplier resilience as important as product strength.
For procurement teams and service operators, equipment evaluation should move beyond headline specifications and incorporate workflow fit, safety design, commercial wheel compatibility, and long-term serviceability. The most effective purchasing decisions will increasingly reflect how equipment supports bay productivity, compliance readiness, and the ability to handle a broader mix of tire and wheel service demands without unnecessary specialization overhead. Framed this way, tire changers become not just a maintenance tool but part of a broader operational efficiency and risk management strategy.
Detailed segmentation data, company-level capability mapping, and application-specific demand patterns can materially sharpen these decisions. For organizations seeking a deeper view of regional dynamics, product-category shifts, and competitive positioning across the tire changers market, the full PW Consulting research report provides a more granular foundation for planning and investment prioritization.
For detailed analysis of this topic, please visit the official page: Tire Changers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


