



SPD Market Insights: Why 6.98% CAGR and $344.8M Value Redefine 2026 Growth

The Surge Protection Device Market at a Strategic Crossroads: Growth, Regulation, and the Shift Toward Integrated Infrastructure Protection
The global surge protection device (SPD) market has entered a phase of steady expansion, with total revenue crossing the $215 million mark in 2025 and a projected compound annual growth rate of 6.98 percent through 2032. The trajectory reflects a market that has evolved from a peripheral electrical accessory into a core component of resilient power infrastructure. Between 2020 and 2025, revenue climbed from approximately $163 million to $215 million, a pace that accelerated as building codes tightened, industrial automation expanded, and end users grew more sensitive to equipment downtime. Looking ahead, the market is expected to scale toward roughly $345 million by 2032, driven by a blend of regulatory mandates, electrification trends, and a structural shift toward smarter, more visible protection devices. Yet growth alone does not guarantee profitability or competitive advantage. The SPD landscape is shaped by a fragmented supplier base, shifting cost dynamics, and a regulatory environment that increasingly rewards devices with clear end-of-life signaling and fail-safe performance. For executives, investors, and procurement leaders, the question is no longer whether the market is expanding, but how value is being captured across regions, product categories, and end-use segments, and where strategic positioning can create durable differentiation.
A Market Characterized by Broad Adoption and Concentrated Competition
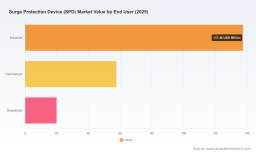
The overall market size has grown consistently over the past half-decade, with the most pronounced step-up occurring between 2022 and 2025. That acceleration aligns with a broader push toward protective infrastructure in both new construction and retrofit projects, as well as increased awareness of transient overvoltage risks in sensitive industrial and commercial environments. The forecast period through 2032 points to continued expansion, though the pace suggests a maturing market rather than a hypergrowth phase. Revenue growth is expected to be supported by higher penetration in industrial and commercial applications, where the cost of downtime and equipment damage far exceeds the upfront expense of protection devices. At the same time, residential adoption is expanding more gradually, constrained by installation complexity and cost sensitivity among homeowners.
Competition in the SPD market remains moderately concentrated, with the top three firms accounting for roughly 24.6 percent of revenue and the top five reaching about 26.2 percent. This concentration level indicates that while established players hold meaningful share, a long tail of regional and specialized manufacturers continues to compete on price, application-specific engineering, and local service relationships. The market structure creates both opportunity and vulnerability. Incumbents with broad product portfolios and strong compliance credentials can leverage scale and brand trust, while smaller firms can win in niche segments by addressing specific signal-level protection, hazardous-area needs, or localized regulatory requirements. The net effect is a market where differentiation is increasingly tied to integration, certification agility, and lifecycle visibility rather than standalone surge suppression performance alone.
Key Challenges and Inflection Points Shaping the Market
Several structural pressures are redefining how SPDs are specified, purchased, and maintained. The first is the growing emphasis on end-of-life visibility and proactive maintenance. Regulatory expectations and engineering best practices are pushing devices toward clear status indication, remote monitoring, and fail-safe disconnection. This shift is changing procurement criteria: buyers are no longer evaluating SPDs solely on surge current ratings and certification, but also on how easily a device can be inspected, replaced, and integrated into maintenance workflows. The second challenge involves cost dynamics at the installation and ownership level. Whole-house and commercial panel-mounted SPDs typically require professional electrician labor, which adds meaningful upfront expense and can slow adoption in price-sensitive residential and small commercial segments. At the same time, energy and raw material cost pressures are being passed through the supply chain, raising the sticker price of premium units and creating a tension between protection quality and budget constraints. The third inflection point is the regulatory and standards environment itself. Updated editions of key safety and performance standards are reshaping product design requirements, particularly around testing, classification, and lifecycle behavior. Manufacturers must navigate a landscape where compliance is not static; it evolves with each standards cycle, affecting product roadmaps, certification timelines, and competitive parity across regions. Together, these forces are moving the market from a transactional hardware business toward a more service-aware, compliance-driven, and integration-focused market.
Worldwide Ethernet Surge Protector Market
Key Drivers of Market Change
The market's trajectory is being shaped by four interlocking drivers: technological innovation, regulatory momentum, shifting demand-side behavior, and supply-side cost structures. Each driver influences not only volume growth but also the mix of products that win in different applications.
Technological Innovation: From Standalone Suppression to Integrated, Intelligent Protection
Innovation in SPDs is increasingly centered on integration, miniaturization, and lifecycle management rather than raw surge-handling capability alone. Modular and plug-in architectures are reducing installation friction by enabling faster replacement and panel-level integration without extensive rewiring. Narrow-profile designs are gaining traction in space-constrained distribution boards and control panels, where engineers must balance protection with physical layout constraints. At the device level, thermally protected MOV-based solutions and gas discharge tube combinations continue to evolve, with an emphasis on fail-safe disconnection that prevents a degraded device from becoming a hazard after repeated stress events. Equally important is the move toward end-of-life signaling and remote indication. As maintenance teams face higher labor costs and more complex asset portfolios, SPDs that can communicate status or provide clear visual indicators are becoming more valuable because they reduce inspection uncertainty and support planned replacement. This trend is especially relevant in commercial and industrial environments, where downtime avoidance is a primary purchase driver and where SPDs are increasingly specified as part of a broader power quality and resilience strategy rather than as isolated hardware.
Policy and Regulatory Environment: Standards as a Design and Competitive Force
Regulatory frameworks are no longer just compliance checkpoints; they are actively shaping product architecture and procurement standards. Updated editions of UL 1449 have reinforced expectations around end-of-life visibility, pushing manufacturers to design devices with clearer status feedback and more predictable maintenance behavior. Complementary updates to IEC standards for low-voltage AC SPDs have refined performance parameters, making it easier to compare devices across international supply chains while also raising the bar for consistent test compliance. In parallel, electrical code cycles and regional building requirements continue to influence where SPDs are mandated or strongly recommended, particularly in new construction and major renovations. The practical effect is twofold. First, compliance credentials are becoming a more significant competitive moat, because certification timelines and test coverage can delay product launches and affect market access. Second, specifiers are increasingly writing requirements around lifecycle behavior and maintenance readiness rather than surge rating alone, which rewards manufacturers that can demonstrate robust design, clear documentation, and reliable post-event behavior.
Demand-Side Shifts: Electrification, Downtime Sensitivity, and Professionalization of Installation
Demand is being reinforced by several structural changes in how power is consumed and protected. Industrial automation, data-dependent commercial operations, and the proliferation of sensitive electronics have raised the cost of transient overvoltage events, making protection a more visible line item in facility planning. In commercial and industrial settings, SPDs are increasingly bundled into broader power distribution and switchgear discussions, which shortens specification cycles when devices are already aligned with recognized panel or switchgear platforms. At the same time, installation patterns are shifting toward a more professionalized model. Whole-house and larger commercial installations often require qualified electricians, and that labor requirement introduces both cost and scheduling considerations for end users. As a result, demand is strongest where the protection value is easy to quantify, where installation can be streamlined, or where devices are integrated into equipment that is already being purchased for other reasons. Residential demand is growing more slowly, partly because the value proposition must overcome both cost sensitivity and installation friction, though it is supported by broader home resilience trends and insurance-related awareness.
Supply Chain and Cost Structure: Material Pressures, Pricing, and Value Perception
On the supply side, energy costs and raw material prices have been moving through the value chain, affecting both manufacturer margins and end-user pricing. Premium surge protection devices are not immune to these pressures, and in some cases the price increase has created hesitation among cost-conscious buyers. That dynamic is important because it can widen the gap between basic and advanced devices, potentially slowing adoption of higher-specification products unless their value is clearly communicated. At the same time, periodic maintenance and component replacement introduce recurring cost considerations, especially where maintenance teams must inspect and replace elements such as MOVs or gas discharge tubes over time. These factors are nudging the market toward designs that reduce inspection burden, simplify replacement, and provide better visibility into device health. The broader implication is that cost is no longer just an upfront purchase decision; it is increasingly a total-cost conversation that includes installation labor, maintenance effort, downtime risk, and the reliability of end-of-life handling.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a group of large, diversified electrical and power management companies, alongside specialized players with strong application-specific engineering. The market's moderate concentration suggests room for both broad-portfolio scale play and targeted differentiation. Several recent product and documentation moves illustrate how leading firms are positioning themselves.
Incumbent Strategies: Integration, Compliance Breadth, and Application-Specific Solutions
Schneider Electric has emphasized integration into commercial and industrial distribution boards, extending plug-in SPD offerings that fit into existing panel ecosystems without requiring additional bolt-on enclosures or upstream devices. The strategic intent is clear: make surge protection easier to specify and install by aligning it with recognized load centre and panel platforms, while also improving visibility through end-of-life monitoring and remote indication. This approach targets the commercial and industrial segments where downtime avoidance and maintenance planning matter most. Siemens has taken a related but distinct path, embedding ground reference monitoring into low-voltage switchgear and panels and positioning residential and commercial SPD families as part of a broader protection and power distribution conversation. By tying SPD functionality closer to the equipment already present in the system, Siemens is reinforcing an integrated-infrastructure narrative rather than treating surge protection as an add-on. Eaton continues to focus on high short-circuit current ratings and UL 1449 compliance within power distribution systems, UPS, and switchgear, appealing to buyers who want protection tightly coupled with rated distribution equipment and clear compliance credentials. ABB offers a broad type coverage across Type 1, Type 2, and Type 3 devices, including modular and industrial overvoltage ranges aligned with IEC and UL standards, which supports customers seeking multi-tier protection across different installation points. Mersen has concentrated on thermally protected, fail-safe designs and updated its technical documentation to reflect current UL 1449 and NEC expectations, signaling an emphasis on lifecycle safety and code-aligned specification support. Phoenix Contact has extended its surge protection range toward process automation, measurement and control signals, and hazardous-area environments, including ultra-narrow modular formats and designs optimized for industrial Ethernet and emerging communication protocols. This strategy targets the more specialized end of the market, where space constraints, signal integrity, and environmental requirements create higher engineering barriers.
The pattern across these players is not simply broader product lines; it is a strategic move toward integration points where protection can be specified more naturally, maintained more easily, and justified more clearly. Devices that fit into established panel systems, communicate status, or address signal-level protection in demanding environments are gaining traction because they reduce friction in both specification and operation.
Market Evolution: Integration, Specialization, and the Competitive Middle
The competitive landscape appears to be evolving along three axes. First, there is a push toward integration with existing infrastructure, whether in load centres, switchgear, UPS, or automation panels. This reduces installation burden and improves specification flow, but it also raises the importance of platform compatibility and cross-product validation. Second, there is continued specialization in high-value niches such as signal-level protection, hazardous-area environments, and narrow-profile modular devices. These segments reward engineering depth and can command stronger margins when the application is clearly defined. Third, the market's moderate concentration leaves space for regional and application-focused competitors to compete on service, price, and local specification relationships, especially where procurement teams value responsiveness and localized support. The likely outcome over the next few years is not a simple shakeout, but a more layered competitive environment in which broad incumbents compete on integration and compliance breadth, specialists compete on application performance and environmental fit, and regional players compete on service and speed. Success will increasingly depend on how well a company can align product design, certification readiness, and lifecycle messaging with the way buyers actually specify and maintain SPDs.
Future Trends and Commercial Opportunities
Looking ahead three to five years, three trends are likely to shape where growth and margin opportunities emerge.
Trend 1: Lifecyle-Aware SPDs as a Specification Default
End-of-life visibility, remote indication, and fail-safe disconnection are moving from differentiating features to expected attributes in commercial and industrial applications. As maintenance labor costs rise and downtime becomes more expensive, buyers are likely to favor devices that reduce inspection ambiguity and support planned replacement. The commercial opportunity lies not only in selling hardware, but in aligning product design with maintenance workflows and specification language. Manufacturers that can clearly communicate lifecycle behavior and maintenance readiness may find an advantage in tenders and engineering specs, particularly where facility teams are responsible for large asset bases and limited inspection windows.
Trend 2: Integration into Distribution, Switchgear, and Automation Ecosystems
SPD adoption is likely to accelerate where protection can be incorporated into equipment that is already being procured for other reasons. Plug-in architectures, narrow-profile modular devices, and panel-aligned designs reduce installation friction and make surge protection easier to bundle into broader infrastructure decisions. This trend creates opportunity for suppliers that can demonstrate compatibility, streamline specification, and reduce labor burden. It also creates a challenge for more standalone offerings, which may face longer specification cycles unless they solve a clearly differentiated application need. The strategic implication is that integration is becoming a growth multiplier, especially in commercial and industrial segments where the value of protection can be tied directly to uptime and equipment protection.
Trend 3: Standards-Driven Product Cycles and Regional Divergence
As standards continue to evolve, product cycles will be shaped less by a single breakthrough and more by recurring compliance updates, test coverage, and documentation rigor. Companies that can manage certification agility and keep pace with evolving requirements will be better positioned to maintain market access across regions. At the same time, regional differences in code adoption, installation practice, and preferred product formats will continue to create uneven opportunity sets. In some markets, residential and small-commercial growth may remain constrained by labor cost and price sensitivity, while industrial and larger commercial deployments continue to expand at a steadier pace. The opportunity here is to treat standards and regional requirements as a design input rather than an afterthought, especially for manufacturers with global ambitions or multi-market portfolios.
Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Persistent raw material and energy cost pressure could keep upward pressure on pricing, potentially slowing adoption of premium devices in cost-sensitive segments. Labor availability and installation cost may continue to constrain residential and small-commercial uptake, especially where whole-house solutions require professional installation. Standards evolution can also create transitional friction, as products are updated, re-tested, or repositioned to meet revised requirements. Finally, the market's moderate concentration means competitive dynamics can shift if regional players gain traction through service, pricing, or localized specification relationships. These risks do not undermine the growth outlook, but they do suggest that execution quality around compliance, integration, and cost communication will matter as much as product performance.
Implications for Decision Makers
The SPD market is no longer just a story about surge current ratings and basic certification. It is increasingly a story about how protection is specified, installed, maintained, and integrated into broader infrastructure. That shift creates different implications for different roles.
For Manufacturers
Differentiate through integration and lifecycle visibility rather than hardware specifications alone. Devices that fit naturally into established panel, switchgear, or automation ecosystems, and that provide clear status feedback or fail-safe behavior, are better positioned for specification in commercial and industrial environments. Equally important is certification readiness and documentation discipline, since evolving standards can influence both market access and buyer confidence. Manufacturers should also consider how installation labor and maintenance effort affect total cost perception, because reducing friction at deployment and inspection can be as valuable as improving surge-handling performance. Where possible, targeting high-value niches such as signal-level protection, hazardous-area environments, or narrow-profile modular formats can create stronger margins and more defensible positioning.
For Investors
Focus on business models and product strategies that benefit from recurring specification pull rather than one-off hardware sales. Value is likely to accrue to companies that can align with integration points, demonstrate compliance agility, and communicate total-cost advantages in downtime-sensitive segments. The market's moderate concentration suggests that scale alone does not guarantee outsized share gains; differentiation through application fit, lifecycle design, and specification alignment may be more durable. Investors should also watch how standards updates affect product roadmaps and regional access, because compliance execution can become a competitive differentiator or a launch bottleneck depending on the company's readiness.
PW Consulting
For Procurement and Specification Teams
Move the evaluation conversation beyond upfront price and basic ratings. Include installation labor, maintenance visibility, replacement simplicity, and compliance documentation in the selection criteria, because these factors increasingly determine real-world total cost and operational risk. Where possible, favor devices that integrate with existing distribution or panel platforms, and verify that end-of-life signaling or status indication aligns with your maintenance processes. In commercial and industrial contexts, specify for lifecycle behavior and downtime avoidance as much as for surge handling, since the clearest value often comes from reducing inspection uncertainty and planned replacement friction. In residential or small-commercial settings, weigh installation complexity and labor cost carefully, because these can be the main barriers to adoption even when the protection rationale is sound.
Surge Arresters Market
Strategic Intelligence as a Decision Multiplier
The SPD market is moving through a period in which growth is real, but value capture is uneven. Companies that treat surge protection as an integrated, lifecycle-aware, and standards-aligned part of infrastructure planning are better positioned to win specification, reduce installation and maintenance friction, and build credibility with buyers who are increasingly focused on uptime and operational resilience. For organizations making build, buy, partner, or specification decisions, the most useful intelligence is granular: it connects regional requirements, product formats, end-use dynamics, and competitive moves to the specific segments where a strategy will actually be tested. Detailed segmentation data, competitive profiling, and scenario analysis can help turn broad market direction into concrete commercial choices. For readers seeking a deeper dive into subsegment breakdowns, regional nuances, and customized strategic implications, the full PW Consulting market research report provides the structured detail needed to support planning and execution at the segment level.
For detailed analysis of this topic, please visit the official page: Surge Protection Device (SPD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


