



CNT Market’s 14.88% CAGR Trajectory: What Structural Shifts Are Really Driving It

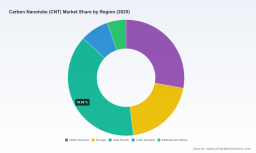
Carbon Nanotube Market Strategic Trends and Commercial Opportunities: A 2025–2032 Outlook
Carbon nanotubes have moved beyond laboratory promise into a phase of commercial scaling defined by structural demand, repeated capacity expansions, and increasing integration into mainstream material portfolios. Over the historical period from 2020 through 2025, the global carbon nanotube sector expanded from roughly 500 million USD to approximately 1.75 billion USD, reflecting a marked acceleration in the later years of the timeline. Current forecasting places the market on a 14.88 percent compound annual growth trajectory through 2032, with revenue projected to reach 4.59 billion USD by the end of the forecast window. This growth curve is not linear. It reflects a bimodal pattern in which early development years gave way to a step-change in commercialization as battery manufacturers, electronics assemblers, and advanced composite engineers began standardizing carbon nanotube additives into production processes.
For executives and investors, the central question has shifted from whether carbon nanotubes will scale to how the value chain will organize itself around scale. The answer increasingly depends on how quickly producers can translate capacity additions into consistent quality, how industrial buyers absorb new formulations without disrupting existing lines, and how regulatory frameworks mature around exposure, handling, and reporting requirements.
Market Context and Critical Inflection Points
The market is experiencing a transition from fragmented early-stage adoption to a more concentrated, application-led growth structure. Concentration among the leading participants remains significant, with the top three firms accounting for a substantial share of total revenue and the top five approaching a majority of market activity. This concentration is not accidental. It reflects the technical complexity of producing carbon nanotubes at consistent purity, the capital intensity of expanding production, and the importance of established supplier relationships in validation-heavy industries such as electronics, energy storage, and structural composites.
Two inflection points are shaping the near-term trajectory. The first is the move from pilot-scale validation to volume integration, especially in batteries and conductive formulations. As production capacity expands across multiple geographies, the limiting factor is no longer whether carbon nanotubes can be made, but whether dispersion quality, dust control, and batch-to-batch consistency can meet industrial acceptance thresholds at scale. The second inflection point is the growing intersection of nanomaterials with regulatory oversight. Carbon nanotubes are increasingly treated as a distinct class requiring documented risk and exposure data, which raises the compliance burden for manufacturers and processors while simultaneously reinforcing the advantage of established producers who already operate with structured quality systems and reporting processes.
The third pressure point is cost-driven selectivity among buyers. As more suppliers enter the market and capacity grows, industrial users are becoming more discerning about grade, dispersion format, and performance claims. This is a healthy maturation signal, but it also means that generic product offerings will face margin compression. The commercial battleground is now differentiating by capability rather than by availability alone.
Core Drivers Reshaping the Carbon Nanotube Market
Technological Innovation and Performance Breakthroughs
The most consequential technical shift is the migration of carbon nanotubes from niche enhancement materials to standard constituents in demanding applications. High-conductivity grades and tailored dispersions are now being positioned for lithium-ion battery anodes and cathodes, conductive plastics, and advanced composite systems. The strategic value lies in incremental but compounding performance gains: lower internal resistance, improved charge-transfer pathways, stronger mechanical reinforcement at lower loading levels, and formulation designs that reduce processing complexity.
Recent progress in dispersion engineering and co-catalyst development illustrates this trend well. Rather than chasing raw capacity alone, leading producers are increasingly focused on formulations that improve dispersibility, lower dust generation, and simplify downstream integration. That matters because industrial adoption often hinges on manufacturability. A material that delivers exceptional lab properties but is difficult to handle at scale will lose to a slightly less exotic alternative that behaves predictably in continuous production environments.
Policy and Regulatory Environment
Regulatory dynamics are becoming a defining part of the operating landscape. Under evolving chemical oversight frameworks, manufacturers, importers, and processors of carbon nanotubes are increasingly expected to submit risk and exposure data, and some jurisdictions have introduced reporting thresholds relevant to production and handling facilities. State-level surveys have also identified where carbon nanotubes are used across semiconductor, composite, and nanotechnology manufacturing sites, which signals a more active monitoring environment.
This regulatory trajectory has two practical implications. First, it adds a layer of compliance cost and administrative rigor, particularly for new entrants or smaller producers with less mature environmental, health, and safety infrastructure. Second, it creates a differentiation advantage for producers that can provide documented traceability, controlled manufacturing conditions, and formulation support that simplifies downstream compliance. In effect, regulatory maturation is pushing the market toward quality assurance as a strategic asset rather than a back-office function.
Worldwide Carbon Nano Cold Cathode Tube Market
Demand-Side Shifts in Electronics, Energy, and Advanced Materials
Demand is being pulled by several converging industrial priorities. In electronics and semiconductors, the push for more efficient conductive pathways and miniaturized components is creating steady interest in nanotube-based inks, formulations, and functional materials. In energy storage, battery performance, cycle life, and thermal behavior remain central engineering concerns, which makes conductive additives attractive when they can be integrated without compromising existing manufacturing economics. In structural composites and polymer systems, formulators are looking for reinforcement and conductivity improvements that can be achieved at practical loading levels without undermining processability.
What makes this phase different is the combination of volume and specificity. Buyers are not simply asking for carbon nanotubes; they are asking for grades that match particular processing routes, dispersion formats that minimize disruption, and performance consistency that survives scale-up. As a result, demand growth is increasingly tied to supplier capability in application engineering, not just tonnage.
Supply Chain and Cost Structure Dynamics
The cost structure of the market is evolving as production scales and geographic diversification increases. Capacity expansions across multiple regions are reshaping supply resilience, while the industrial focus on dispersion quality and low-dust formulations is changing what counts as a commercially viable product. In practical terms, the total delivered value of a carbon nanotube offering now depends on more than purity and price per kilogram. It includes the downstream burden of handling, dispersion, integration, and performance validation.
PW Consulting
Supply chains are also becoming more application-specific. Producers that can offer standardized dispersion formats and formulation support reduce the adoption friction for buyers, while those operating only at the powder level may face longer qualification cycles. This is gradually shifting the competitive center of gravity from raw production alone toward integrated material solutions.
Competitive Landscape and Strategic Positioning
The competitive field is increasingly defined by scale, application focus, and formulation capability. A small group of major producers is driving much of the capacity expansion and product standardization activity, while a broader set of specialized firms competes in high-purity, electronics-grade, or research-oriented segments. This dual structure is important: volume leadership is becoming more valuable in battery and conductive-additive markets, while specialty differentiation remains essential in semiconductors, printed electronics, and high-specification composites.
Several strategic patterns are visible across the leading participants.
-
Vertical integration around capacity and geography is a common theme. Firms are expanding plant networks to support growing demand from energy storage and conductive applications, while also positioning themselves closer to key downstream markets. This reduces logistical friction and strengthens supply reliability for large buyers.
-
Formulation and dispersion capability is becoming a differentiator. The ability to supply ready-to-use dispersions, low-dust grades, and iron-free or otherwise tailored formulations matters because it shortens adoption cycles and simplifies integration into battery and polymer processes.
-
Product-line diversification is widening the addressable market. Leading producers are building portfolios that span battery additives, conductive plastics, coatings, and composite reinforcements, which helps buffer demand volatility across end-use sectors.
Boron Nitride Nanotubes (BNNT) Market -
Specialization remains a viable path. Companies focused on high-purity semiconducting grades or research-grade materials continue to play an important role in enabling emerging uses, particularly where performance specificity outweighs volume considerations.
Capacity expansion is a dominant theme in recent industry activity. One major producer commissioned an additional facility that lifted total operating capacity by a significant margin, reflecting a deliberate push to support battery and conductive additive demand. Another volume-focused producer initiated a new cathode material project with phased capacity coming online in the near term. A leading single-walled carbon nanotube producer scaled dispersion capacity substantially through partner-based expansion in China. These moves are not isolated. They indicate a market where producers are racing to secure both volume and application proximity.
The competitive evolution is also likely to produce consolidation pressure over time. As the market matures, larger, well-capitalized producers with multi-application portfolios and strong formulation capabilities will be better positioned to absorb demand cycles and compliance requirements. At the same time, specialized entrants can still thrive where performance requirements are highly specific and switching costs are high. The net effect is a market that is simultaneously consolidating at the top and fragmenting in niche segments where precision and technical support matter more than scale.
Forward Trends and Strategic Implications for 2026–2032
Trend One: Battery and Energy Storage Applications Will Anchor Volume Growth
Energy storage remains one of the most important demand anchors for carbon nanotubes, particularly as conductive additives become more embedded in battery electrode design. The practical opportunity is not only in improved conductivity, but also in engineering gains such as reduced internal resistance and better material integration. As battery manufacturers continue to optimize performance and throughput, nanotube-based additives are likely to see broader acceptance where they can demonstrate measurable process and performance benefits.
The commercial implication is clear: producers that can consistently supply battery-grade formulations with strong quality control and application support will capture disproportionate value. Buyers, in turn, should evaluate supplier capability in dispersion design and qualification support rather than treating carbon nanotubes as a commodity input.
Trend Two: Regulatory and Handling Standards Will Reshape Sourcing Decisions
As reporting expectations and oversight mechanisms become more defined, sourcing decisions will increasingly factor in compliance readiness, exposure documentation, and handling characteristics. This trend does not necessarily slow the market, but it does raise the bar for operational maturity. Producers with structured quality systems and transparent documentation will have an advantage, while less organized participants may find it harder to enter regulated supply chains.
For industrial users, this means that supplier selection should incorporate compliance, safety, and handling considerations alongside performance metrics. For producers, it means that documentation, traceability, and formulation support are no longer optional enhancements; they are part of commercial competitiveness.
Trend Three: Formulation, Dispersion, and Application Engineering Will Outperform Raw Powder Competition
As capacity grows, the market will increasingly reward solutions that reduce integration risk. Dispersion quality, dust control, batch consistency, and ready-to-use formats will become more valuable than price alone. This is a typical maturation pattern in advanced materials: early competition centers on basic availability, and later competition centers on reliability, usability, and performance assurance at scale.
Strategically, this favors companies that invest in formulation know-how and customer-facing technical support. It also creates opportunities for partnerships between material producers and downstream formulators who can co-develop application-specific solutions.
Risks and Uncertainties
Several uncertainties could shape the pace and distribution of growth. Regulatory requirements may evolve faster than some producers can adapt, especially if exposure and risk assessment expectations expand. Overcapacity in certain grades could pressure margins if demand does not keep pace with new capacity, particularly where differentiation is weak. Application adoption may also be slower than anticipated in some sectors if validation cycles remain long or if alternative materials improve rapidly. Finally, supply chain concentration in specific geographies could create vulnerability if logistics, trade conditions, or local operating environments shift.
These risks do not undermine the broader growth outlook, but they justify disciplined capacity planning, strong application engineering, and careful attention to regulatory readiness.
Actionable Guidance for Decision Makers
For manufacturers and product developers, the priority is to treat carbon nanotube selection as an integration decision, not just a material purchase. Qualifying a supplier should include dispersion behavior, dust and handling characteristics, batch consistency, and the supplier's ability to support scale-up. Where feasible, co-developing formulations with experienced producers can reduce qualification time and improve performance predictability in production environments.
For investors, the most durable value creation is likely to come from companies that combine scalable capacity with formulation strength and multi-application portfolios. Pure capacity expansion without application support may generate volume but not necessarily margin resilience. Due diligence should therefore assess not only capacity milestones, but also dispersion capability, customer qualification progress, regulatory readiness, and the degree to which a company is embedded in high-value demand segments such as batteries and conductive materials.
For procurement and sourcing leaders, the market now rewards technical evaluation over simple price comparison. Evaluation criteria should include documented quality systems, handling and safety posture, dispersion formats, and track record in the specific application of interest. Diversifying across suppliers with different strengths can also reduce exposure to single-source risk, particularly where supply is concentrated or where regulatory and compliance expectations are tightening.
As the market moves deeper into this phase of scaling and standardization, the competitive edge will belong to organizations that can align material capability with operational reality. The most useful next step is to map current application requirements against supplier capabilities, identify where dispersion, quality, and compliance readiness matter most, and prioritize engagement with producers that can demonstrate measurable integration value rather than generic availability. Detailed segmentation data, supplier benchmarking, and application-specific pathway analysis can further sharpen these decisions and support more targeted commercial strategy.
For detailed analysis of this topic, please visit the official page: Carbon Nanotube (CNT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


