



KNX Products Market: Why 10.94% CAGR Through 2032 Changes Everything

The KNX Products Market: Strategic Trajectories and Commercial Imperatives
The KNX products market represents a mature yet rapidly evolving segment within the broader building automation ecosystem. As buildings worldwide transition from passive structures to intelligent, interconnected environments, KNX-certified solutions have solidified their position as a benchmark protocol for integrated control systems. The market has demonstrated consistent growth over the past half-decade, expanding from approximately 127.0 million USD in 2020 to an estimated 164.19 million USD in 2025. Projections indicate this trajectory will accelerate through the end of the decade, with the market reaching roughly 180.25 million USD in 2026 and climbing to 338.0 million USD by 2032. This expansion reflects a compound annual growth rate of approximately 10.94 percent, signaling that demand is not merely sustaining but compounding as architectural, technological, and regulatory forces converge.
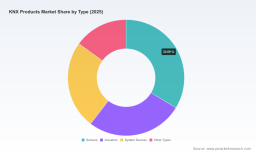
Such growth is not uniform across all vectors. The market's composition reveals a balanced but increasingly specialized demand structure, where sensors command the largest share of product allocation, followed by actuators, system devices, and ancillary product categories. Application-wise, lighting control remains the dominant use case, with HVAC control, energy management, shutter and blind control, and access and security systems forming a tightly interwoven secondary tier. Geographically, the market has historically been anchored in Europe, which accounts for the largest revenue share, while North America, Asia Pacific, Latin America, and the Middle East and Africa each contribute distinct but growing portions of total demand. The competitive arena remains moderately fragmented, with the top three players commanding roughly 24.0 percent of market revenue and the top five collectively holding about 36.0 percent. This concentration suggests a landscape where established incumbents retain substantial influence but where differentiation, regional adaptation, and technological refinement continue to create openings for strategic positioning.
Key Challenges and Inflection Points
Despite the favorable growth outlook, the KNX products market is navigating several structural challenges that will shape competitive outcomes over the next several years. The first challenge lies in protocol harmonization and interoperability expectations. While KNX enjoys strong recognition as a standardized, open protocol, building owners and system integrators increasingly expect seamless connectivity across heterogeneous ecosystems, including IP-based networks, cloud platforms, and proprietary IoT extensions. Manufacturers that treat KNX as a standalone control layer without addressing cross-protocol bridging risk losing relevance in projects where unified dashboards, remote accessibility, and data interoperability are non-negotiable requirements.
A second challenge emerges from the tension between standardization and customization. KNX-certified devices offer reliability and compatibility advantages, but many high-value commercial and luxury residential projects demand bespoke integration scenarios, localized regulatory compliance, and aesthetic differentiation. Suppliers must balance the efficiency of standardized product lines with the flexibility required for specialized deployments. Over-indexing on either extreme can erode margins or reduce market reach.
Third, the market faces an inflection point around skills and installation capacity. As KNX solutions expand from advanced residential projects into broader commercial, institutional, and multi-family environments, the availability of trained integrators and electricians becomes a bottleneck. The protocol's technical rigor is an asset for system performance, but it also raises the barrier to rapid deployment. Companies that invest in simplified configuration tools, stronger partner enablement, and clearer commissioning workflows are better positioned to scale adoption without compromising quality.
Key Drivers of Market Change
Technological Innovation and Protocol Evolution
Technology advancement is the most visible driver reshaping the KNX products market. The convergence of traditional KNX bus architecture with IP connectivity and IoT-enabled extensions is widening the addressable use cases for sensors, actuators, and system devices. Recent industry activity underscores this direction. In March 2026, the KNX Association showcased its member ecosystem at Light + Building, where multiple companies presented the latest KNX IoT and intelligent energy management solutions. This exhibition signaled a clear strategic emphasis: KNX is evolving beyond isolated control functions toward integrated energy intelligence, remote management, and data-aware building operations.
For manufacturers, this shift is not merely a feature upgrade. It reframes the value proposition of KNX-certified devices from static control components to enablers of measurable energy performance and operational insight. Sensors that once served localized detection functions are now being positioned as inputs for broader automation logic, while actuators and system devices are increasingly designed to interface with centralized analytics and demand-response strategies. Companies that embed connectivity, software-friendly interfaces, and upgrade pathways into their hardware portfolios are likely to capture disproportionate share in projects where building owners prioritize future-proofing over lowest initial cost.
Policy and Regulatory Momentum
Regulatory pressure is a powerful accelerant for KNX adoption, particularly in regions with aggressive building decarbonization targets. Policy frameworks are increasingly tying building performance to measurable energy outcomes, and automation systems have become essential instruments for compliance and optimization. The EU Energy Performance of Buildings Directive, for example, highlights that buildings account for approximately 40 percent of EU energy consumption and 36 percent of energy-related CO2 emissions. This regulatory context creates direct demand for control systems capable of monitoring, balancing, and reducing consumption across lighting, HVAC, shading, and security functions.
Within this environment, KNX-certified products are gaining relevance because they align with established energy performance assessment standards. Certified products can enable up to 50 percent energy savings in building automation when deployed in accordance with top Energy Performance Class requirements under EN 15232. This capacity is not a marginal benefit; it is becoming a core procurement rationale for public tenders, large-scale commercial developments, and retrofit programs where compliance and documented efficiency gains carry financial and reputational weight. For suppliers, regulatory tailwinds are most valuable when paired with clear documentation, certification transparency, and application guidance that helps project teams translate compliance goals into system design choices.
Smart Building Market
Demand-Side Shifts in Building Ownership and Operations
Demand patterns are also changing as building owners and facility operators reevaluate the role of automation in total cost of ownership. The traditional purchase logic centered on hardware price is giving way to a broader assessment that includes energy savings, comfort, maintenance predictability, and integration with corporate sustainability commitments. In residential segments, buyers are increasingly treating smart control not as a premium add-on but as a baseline expectation for new developments and high-end renovations. In commercial environments, operational resilience and energy cost control are driving facility managers to favor systems that can centralize control across multiple subsystems without creating vendor lock-in.
This shift has implications for product mix and go-to-market strategy. Lighting control remains the largest application area, but demand is increasingly cross-linked with HVAC control, energy management, and access and security workflows. Buyers are less interested in isolated subsystems and more interested in coherent environments where shading, climate, illumination, and security can respond to occupancy patterns and external conditions in a coordinated manner. As a result, suppliers offering integrated yet modular KNX portfolios are better aligned with how projects are being specified and evaluated.
Supply Chain and Cost Structure Considerations
Supply chain dynamics continue to influence competitive positioning, particularly for hardware-heavy product categories. The market's reliance on sensors, actuators, and system devices means that component availability, manufacturing efficiency, and logistics stability directly affect time-to-market and margin preservation. While the sector has not faced the same level of disruption as some consumer electronics segments, cost volatility and lead-time variability remain practical concerns for both producers and integrators. The companies most effectively managing these pressures are those that combine disciplined sourcing with product architectures that allow regional adaptation without excessive rework.
Cost structures are also being reshaped by the growing importance of software-supported configuration, remote diagnostics, and service-enabled offerings. As building automation becomes more data-centric, the economic value of a KNX product is increasingly tied to the surrounding ecosystem: documentation quality, integration support, training, and post-installation service. Manufacturers that treat these elements as part of the core offering, rather than as after-sales extras, can differentiate more effectively in a market where hardware specifications alone are becoming less sufficient as a competitive moat.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The competitive field in the KNX products market features a broad set of established manufacturers, many of whom anchor their KNX offerings in certified actuators, sensors, and control devices spanning lighting, heating, ventilation, and security applications. German and French firms feature prominently in this landscape, reflecting the deep integration of KNX within European building culture and procurement norms. Companies such as ABB AG through its BUSCH-JAEGER and STOTZ-KONTAKT units, Albrecht Jung GmbH & Co. KG, 4ba GmbH, Berker, B.E.G. Brück Electronic GmbH, Busch-Jaeger, Gira, Hager Group, MDT Technologies, Theben AG, and Siemens AG represent a strong presence of organizations with well-defined automation portfolios and established distribution relationships.
Beyond these, the landscape includes Legrand and Schneider Electric from France, Somfy from France, and a wider circle of specialists and regional players such as Eelectron, HDL Automation, IPAS GmbH, Lime International, STEINEL, Urmet, Weinzierl Engineering, Zennio Avance y Tecnologia S.L., and GVS. While their individual product emphasis varies, the collective profile suggests a market where many manufacturers compete on similar foundational capabilities: KNX certification, application breadth, and reliability. Differentiation therefore tends to emerge through brand strength, regional channel reach, design language, integration partnerships, and the ability to support complex project requirements end to end.
PW Consulting
Leading incumbents are increasingly distinguishing themselves not just by what they sell, but by how they enable deployment. Stronger technical documentation, expanded accessory ecosystems, integration with planning tools, and more intuitive commissioning processes can reduce friction for integrators and specifiers. In practice, this means that a manufacturer's strategic advantage may depend as much on its support infrastructure and partner network as on the specifications of individual devices. In a market where the top five players collectively hold around 36.0 percent of revenue, sustained leadership will likely belong to those who convert certification and product range into repeatable project wins and long-term specification loyalty.
Market Evolution: Consolidation, Specialization, and New Entry
The competitive landscape appears poised for selective consolidation and parallel specialization. On one hand, the moderate concentration levels indicate room for continued fragmentation, especially in regional markets where local service, compliance knowledge, and distributor relationships remain decisive. On the other hand, the increasing complexity of connected building projects favors larger portfolios, stronger R&D resources, and broader international support capabilities. This dynamic may encourage consolidation among mid-tier players seeking scale, while also creating space for niche specialists who excel in particular application areas such as lighting control, shading, or energy management.
New entrants and adjacent players are also likely to influence the market, especially where KNX intersects with IoT platforms, smart metering, and remote building management. The competitive threat is not necessarily direct displacement of KNX devices, but rather the expansion of expectations around what those devices must connect to and communicate with. Companies that can position KNX as the dependable field-level backbone within a broader digital architecture are likely to preserve and extend their relevance. Conversely, players that fail to adapt to cross-platform expectations may find their products confined to narrower, more price-sensitive segments.
Future Trends and Commercial Opportunities
Trend 1: Energy Intelligence as a Core Product Dimension
Over the next three to five years, energy management is expected to transition from a supporting application to a central design driver for KNX product strategies. Regulatory pressure, operating cost sensitivity, and corporate sustainability commitments are aligning to make measurable energy performance a priority in both new builds and retrofits. KNX systems that can coordinate lighting, HVAC, shading, and security while feeding usable data into building-level energy oversight will likely see stronger specification rates. The commercial opportunity lies in developing product combinations and configuration models that make energy outcomes easier to design, validate, and maintain. Suppliers that can demonstrate credible savings pathways and align their portfolios with recognized performance classes will have an advantage in tender processes and high-value projects.
Trend 2: Greater Emphasis on Interoperability and Remote Management
A second trend is the growing expectation that KNX deployments should integrate smoothly with broader digital building environments. This includes IP-based communication, cloud-connected monitoring, and interfaces that allow facility teams to manage multiple sites or subsystems from unified platforms. The commercial opportunity is not simply to add connectivity features, but to reduce the operational burden of KNX integration. Products that are easier to commission, easier to monitor, and easier to expand will appeal to integrators and building owners alike. This trend also creates opportunities for service-oriented models, where ongoing diagnostics, firmware management, and configuration support become part of the value chain rather than peripheral activities.
Trend 3: Regional Acceleration and Application Diversification
The third trend concerns the geographic and application broadening of demand. While Europe remains the strongest revenue base, regions such as Asia Pacific, North America, Latin America, and the Middle East and Africa are contributing increasing shares as building modernization programs, premium residential development, and commercial automation projects expand. At the same time, application demand is spreading beyond lighting control into HVAC control, shutter and blind control, energy management, and access and security control. The commercial opportunity here is twofold: manufacturers can pursue regional adaptation strategies that reflect local building norms, and they can develop application-focused bundles that mirror how projects are actually specified. Companies that treat regional growth as a replication of the European playbook may underappreciate the importance of local integration practices, certification expectations, and procurement channels.
Risks and Uncertainties
These opportunities are accompanied by meaningful uncertainties. One risk is that rapid software-centric innovation could shift value toward platform providers and integrators, compressing hardware margins if manufacturers are unable to justify premium pricing through differentiated performance or services. Another is regulatory variation: while some regions are tightening building performance requirements, others may move more slowly or prioritize different compliance mechanisms, creating uneven demand growth. A third risk relates to execution complexity. As products become more connected and application combinations more intricate, the potential for installation errors, commissioning delays, and support burdens increases. Companies that expand their portfolios without strengthening the corresponding enablement and service infrastructure may find that growth brings operational drag rather than profitable scale.
Strategic Implications for Decision Makers
For Manufacturers and Product Leaders
Manufacturers should prioritize building portfolios that combine KNX certification credibility with clear pathways for connectivity, energy management, and integration support. Rather than treating IoT capabilities as optional add-ons, they should be designed into the product architecture from the outset so that devices can function as dependable field-level components within broader digital building strategies. Equally important is the enablement ecosystem: planning tools, configuration guidance, commissioning support, and partner training can determine whether a strong product lineup translates into repeat specification and successful project outcomes. In a market where concentration remains moderate, differentiation through deployment ease and application coherence can be as important as hardware specifications.
For Investors and Strategic Capital
Investors should evaluate opportunities with attention to companies that can bridge hardware reliability and software-enabled value creation. The most attractive positions may be found where firms can demonstrate durable certification advantages, strong regional channel relationships, and the ability to serve cross-application demand such as lighting, HVAC, and energy management in a coordinated way. Capital allocation should also account for the growing importance of service, training, and integration support as margin contributors. In a market growing at a double-digit CAGR, value capture will increasingly depend on whether a company can convert demand growth into specification loyalty and repeatable project execution rather than one-time product sales.
For Procurement and Integration Leaders
Procurement and integration teams should approach KNX selection with a broader project lens. The lowest unit price may not deliver the best outcome if it increases commissioning complexity, limits future expandability, or weakens energy performance alignment. Evaluation criteria should include certification transparency, compatibility with planned energy management goals, ease of integration with existing or anticipated building platforms, and the quality of supplier support. Given the increasing importance of compliance and operational efficiency, procurement decisions should weigh how well a chosen product set can support documented performance goals over the building lifecycle. Early engagement with suppliers that can provide clear application guidance and integration pathways can reduce project risk and improve long-term value.
Conclusion
The KNX products market is entering a phase where growth is being reinforced by regulatory pressure, technological extension, and shifting expectations around energy performance and interoperability. The market's expansion from roughly 127.0 million USD in 2020 to an projected 338.0 million USD by 2032 reflects more than incremental demand; it reflects a structural realignment in how buildings are specified, commissioned, and operated. Sensors, actuators, and system devices remain foundational, but their commercial value is increasingly tied to how effectively they support lighting control, HVAC control, energy management, shading, and security within integrated environments.
IO-Link Market
For companies operating in this space, the strategic question is no longer whether KNX remains relevant, but how to position within a market that is becoming more connected, more performance-driven, and more application-integrated. The leaders who gain durable advantage will likely be those who combine certified product excellence with stronger enablement, clearer energy-performance alignment, and the ability to serve regional and application diversity without losing coherence. Detailed segment-level data, company-level comparisons, and customized strategic guidance can help decision makers convert these trends into concrete plans. For those seeking a deeper operational view of segmentation, competitive positioning, and forward demand pathways, the full research report provides a more granular foundation for strategy development.
For detailed analysis of this topic, please visit the official page: KNX Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


