



Water Filters Market 2026: Why a 7.7% CAGR and 84.2M Revenue Change Everything

Strategic Trends and Commercial Opportunities in the Water Filters Market
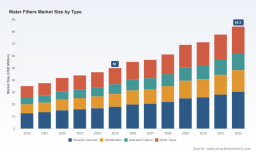
The global water filters market stood at approximately USD 50.0 million in 2025, continuing a steady expansion trajectory from USD 35.15 million in 2020. Over the historical period of 2020 to 2025, the sector demonstrated consistent growth, reflecting heightened awareness of water quality and increasing adoption of point-of-use treatment solutions. Looking ahead to the forecast period of 2026 to 2032, the market is projected to reach USD 84.2 million by the end of the forecast window, translating to a compound annual growth rate of 7.7 percent. This growth profile suggests a market that is maturing but still capable of expansion, driven by technological refinement, regulatory evolution, and shifting consumer expectations. For decision makers, the key question is not whether the market will grow, but which segments, geographies, and strategic positioning will capture disproportionate value as the landscape evolves.
Core Dynamics and Structural Challenges
A defining feature of the current market is its relatively fragmented structure. The top three players account for roughly 28.5 percent of total revenue, while the top five hold around 36.2 percent. This concentration level indicates that no single entity dominates the entire value chain, leaving room for specialized players, regional champions, and new entrants to compete on product differentiation, certification strength, and channel strategy. At the same time, fragmentation can pressure margins and create complexity in standardizing quality and compliance across diverse product portfolios. The industry is at a inflection point where brand trust, certification credibility, and supply chain reliability increasingly differentiate winners from laggards, rather than scale alone.
Three structural challenges shape the near-term outlook. First, regulatory tightening around contaminant reduction claims is raising the bar for product validation. Standards governing PFAS, heavy metals, and aesthetic performance are becoming more rigorous, requiring manufacturers to invest in testing, documentation, and continuous reformulation. Second, raw material cost volatility is compressing margins for certain filter technologies, particularly those dependent on activated carbon, where supply constraints and input price movements have become more pronounced. Third, consumer and commercial buyers are increasingly sophisticated, demanding clearer evidence of performance, water efficiency, and total cost of ownership rather than relying solely on brand familiarity. Together, these forces reward companies that can align innovation with credible certification and transparent value propositions, while exposing those that compete primarily on price without differentiated performance.
Key Drivers Shaping Market Trajectory
Technology Innovation and Certification-Led Differentiation
Technology advancement remains a central engine of growth, but the nature of innovation is shifting from basic filtration capability to targeted contaminant reduction and system efficiency. Reverse osmosis continues to represent the largest technology segment by revenue share, reflecting its broad applicability across residential and light commercial settings where comprehensive contaminant removal is valued. Ultrafiltration and activated carbon solutions also hold meaningful positions, serving use cases where taste, odor, chlorine, particulate, and specific chemical reductions are priorities. The market is increasingly rewarding products that combine multiple treatment stages, intelligent monitoring, and validated performance claims.
Certification dynamics are amplifying the impact of technical innovation. In November 2025, guidance from the EPA reinforced stricter test protocols for the NSF/ANSI 53 standard related to PFAS reduction in point-of-use water filters, requiring certified products to meet elevated contaminant reduction claims for PFOA and PFOS. This shift raises the competitive stakes for manufacturers that can demonstrate verified performance, while simultaneously creating a barrier for products that cannot substantiate their claims. More recently, in April 2026, NSF published its Annual Review and Impact Report 2025, outlining strategic priorities for water filtration standards and certifications for 2026. These developments signal a market where certification is not merely a compliance checkbox but a strategic asset that influences procurement decisions, retail placement, and customer trust.
Policy, Standards, and Regional Regulatory Divergence
Regulatory and standards activity is not uniform across regions, creating both complexity and opportunity. In addition to the tightened PFAS protocols in North American contexts, 2026 saw the NSF/ANSI 42 standard for aesthetic effects revised to require higher minimum recovery rates for water efficiency in certified water filters. This adjustment reflects a broader emphasis on water conservation and system efficiency, encouraging designs that reduce waste while maintaining performance. For manufacturers, the implication is clear: water efficiency is becoming a competitive dimension alongside contaminant reduction, especially in markets where utility costs, sustainability expectations, and resource constraints are rising.
Standards development is also expanding geographically. The launch of the NSF P535 Drinking Water Treatment Units – Filtration protocol for the Chinese market introduced verification for reduction claims covering lead, mercury, chromium, PFOA, PFOS, and BPA in domestic point-of-use systems. This kind of regional standards expansion helps formalize quality expectations in markets with growing middle-class demand and increasing public attention to drinking water safety. At the same time, divergent standards across regions increase the compliance burden for globally oriented product lines, favoring companies that can modularize development, align testing early in the design cycle, and treat regional certification as a core element of market entry strategy rather than a late-stage adaptation.
Air Filters Market
Demand-Side Shifts in Residential, Commercial, and Industrial Settings
Demand trends are evolving across application environments, though the residential segment continues to account for the largest share of market revenue. In homes, the driver is not only perceived taste improvement but also heightened concern about contaminants that are more difficult to detect without testing, including PFAS and certain heavy metals. Consumers are increasingly willing to pay for certified performance and are more attentive to filter replacement cycles, ease of maintenance, and the credibility of contaminant reduction claims. This shift pushes retailers and brands to communicate technical performance in accessible terms while maintaining rigorous certification backing.
Commercial and industrial applications, while smaller in aggregate revenue share, remain strategically important because they often involve higher volume, recurring replacement demand, and more stringent specification requirements. Facilities managers, hospitality operators, and light commercial users are increasingly integrating water treatment into broader sustainability and operational efficiency agendas. In these contexts, total cost of ownership, service reliability, and documentation of performance can matter as much as upfront price. The commercial and industrial segments therefore provide a pathway for differentiated offerings that combine certified filtration with service models, monitoring capabilities, and application-specific configuration.
Supply Chain, Raw Material Costs, and Input-Side Pressure
Supply-side dynamics are an increasingly important part of the market story. In the first quarter of 2026, activated carbon raw material prices in the United States averaged approximately USD 2,204 per metric ton, up from prior quarters due to constraints in coconut shell charcoal supply. For product lines reliant on activated carbon, this kind of input pressure can affect cost structures, pricing flexibility, and margin stability. The challenge is not simply short-term cost fluctuation but the need to manage supply resilience, validate alternative media where appropriate, and ensure that cost changes do not undermine the perceived value of certified performance.
Companies that proactively address input volatility through supplier diversification, formulation efficiency, and transparent communication tend to be better positioned to maintain consistency in product availability and performance claims. In a market where trust is closely tied to consistency, supply chain reliability becomes a strategic differentiator. This is especially true as end users and procurement teams become more aware of the operational consequences of filter performance variation, replacement frequency, and unexpected downtime in commercial settings.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The competitive set spans a range of business models, from retail-focused pitcher and dispenser brands to under-sink and whole-home system providers, and from diversified industrial suppliers to specialized filtration manufacturers. Their profiles illustrate how differentiation is being built across product format, certification emphasis, and channel strategy.
PW Consulting Automotive & Machinery Research Center
- Brita, headquartered in Menden, Germany, remains an active provider of pitcher, dispenser, and bottle water filters certified for taste, odor, and contaminant reduction, with a dominant position in retail volume sales. Its strength lies in everyday consumer accessibility, brand familiarity, and a product ecosystem that aligns with high-frequency replacement behavior.
- A.O. Smith Corporation, based in Auburn, Alabama, is an active manufacturer of under-sink and countertop reverse osmosis and carbon-based water filters, marketing the Aquasana and Pureit brands. Its positioning connects higher-performance treatment technologies with multi-brand portfolios that can address different customer segments and price points.
- Culligan International, located in Northbrook, Illinois, is an active provider of under-sink, pitcher, and whole-home water filtration systems with certified contaminant reduction. Its breadth across home water treatment formats supports a service-oriented model and a strong presence in installed solutions.
- Aquasana, headquartered in Middleburg Heights, Ohio, is an active manufacturer of under-sink and countertop water filters certified to NSF standards for heavy metals, chlorine, and PFAS reduction. Its emphasis on certified contaminant reduction aligns directly with the growing consumer focus on verifiable health-related performance.
- 3M Company, based in Saint Paul, Minnesota, is an active supplier of under-sink and point-of-use water filters and cartridges certified for reduction of volatile organic compounds, chlorine, and particulates. Its heritage in engineered materials and filtration media supports a technical credibility narrative in point-of-use applications.
- iSpring Water Systems LLC, in Atlanta, Georgia, is an active manufacturer of reverse osmosis and sediment/carbon water filter systems certified to NSF/ANSI standards. Its focus on certified RO and multi-stage systems reflects the ongoing demand for comprehensive home treatment solutions.
- Coway Co. Ltd., headquartered in Seongnam, South Korea, is an active provider of countertop, under-sink, and pitcher water purifiers and filters certified for health-related contaminants. Its presence illustrates the global nature of competition and the rising importance of certified performance in Asian and export markets.
- Pentair plc, located in Apopka, Florida, is an active supplier of residential and commercial water filtration systems and cartridges for point-of-use treatment. Its scope across residential and commercial applications positions it to capture demand in both everyday consumer settings and higher-specification commercial environments.
- ZeroWater, headquartered in Wilmington, Delaware, is an active provider of pitcher, dispenser, and faucet-mounted water filters certified to NSF/ANSI 58 for TDS reduction. Its emphasis on total dissolved solids reduction highlights how specific performance claims can anchor brand identity and consumer adoption.
Differentiation, Consolidation, and the Role of New Entrants
The competitive landscape is shaped less by a single dominant champion and more by overlapping spheres of advantage. Some players compete primarily on retail reach and convenience, others on certified contaminant reduction and technical documentation, and still others on installed systems and service relationships. The most resilient strategies tend to combine several of these elements: a clear performance claim, credible certification, reliable supply, and a channel approach that matches the product format to the buying journey.
Market concentration data suggests there is room for both consolidation and continued specialization. Larger players can leverage scale in procurement, testing, and distribution, while smaller or regional specialists can win by focusing on narrow application needs, localized certification, or distinctive product designs. At the same time, the evolving standards environment may encourage consolidation among companies that cannot sustain the cost and complexity of ongoing compliance and reformulation. New entrants are most likely to succeed when they address a specific unmet need, such as a highly targeted contaminant reduction claim, improved water efficiency, smart monitoring, or a service-led commercial model, rather than attempting to compete broadly on price in saturated retail formats.
Forward Outlook: Three Strategic Trends for the Next 3-5 Years
Trend 1: Certification as Commercial Currency
Over the next several years, certified performance is likely to become an even stronger commercial differentiator. As standards tighten around PFAS, heavy metals, and water efficiency, buyers in both consumer and commercial channels will increasingly rely on certification as a shorthand for trust. Products that can clearly document validated reduction claims, replacement consistency, and testing rigor will gain an advantage in retail, e-commerce, and specification-driven procurement. The commercial opportunity lies in turning certification into a visible part of the value proposition rather than a back-office requirement, using it to support pricing discipline, channel selection, and brand positioning. The risk is that certification without clear consumer communication or without consistent product execution becomes a costly compliance burden with limited commercial return.
Refrigerator Water Filters Market
Trend 2: Efficiency, Resource Sensitivity, and System Design
Water efficiency and resource-conscious design are expected to gain prominence as part of a broader sustainability and operating-cost agenda. Revisions to aesthetic and efficiency standards, combined with growing attention to water use in homes and facilities, will encourage product designs that reduce waste and improve recovery rates without compromising contaminant reduction. For manufacturers, this creates an opportunity to innovate around system architecture, filter life, and replacement economics. For commercial buyers, efficiency features can support broader sustainability goals and reduce total cost of ownership. The uncertainty is that efficiency requirements can increase design complexity and testing costs, particularly for smaller suppliers, potentially tilting the field toward companies with stronger engineering and compliance capabilities.
Trend 3: Regional Standardization and Market Formalization
The expansion of regional protocols, such as the newly launched NSF P535 filtration protocol for the Chinese market, points toward a future in which more markets formalize drinking water treatment expectations. As standards become more defined, demand in those markets may become more accessible to certified suppliers while also raising the entry barrier for products that cannot meet local verification requirements. This trend creates opportunities for companies that can navigate regional certification early and build local credibility, especially in high-growth regions where safety concerns and purchasing power are both rising. The counter-risk is regulatory fragmentation: differing test methods, claim language, and certification pathways can increase the cost of multi-region offerings and require more sophisticated product management.
Actionable Guidance for Decision Makers
For Manufacturers and Brand Leaders
Prioritize certification strategy as a core element of product development, not a final-stage approval step. Align engineering, claims language, and testing timelines early so that product launches can be supported by credible, up-to-date certifications. In parallel, evaluate input exposure across filter media and components, especially where activated carbon and other constrained materials play a central role. Diversifying supply, improving media utilization, and designing for consistent replacement performance can help protect margins and maintain trust. Finally, consider how product formats map to customer buying behavior: everyday retail products benefit from strong brand familiarity and clear, simple performance messaging, while installed and commercial solutions gain from documented performance, service reliability, and efficiency credentials.
For Investors and Strategic Allocators
Focus on business models that combine defensible certification, recurring replacement economics, and resilient supply chains. The most attractive opportunities are likely to emerge where companies can demonstrate differentiated contaminant reduction claims supported by recognized standards, while also managing input volatility and regional compliance complexity. In fragmented markets, scalable distribution, strong consumer trust, and the ability to expand into adjacent formats or service-led commercial offerings can create meaningful value. At the same time, attention should be paid to companies that depend heavily on price competition without clear performance differentiation, since tightening standards and input cost pressures may erode the economics of that approach over time.
For Procurement and Channel Decision Makers
Treat certification and documented performance as primary selection criteria, especially where contaminant reduction, water efficiency, and replacement consistency matter to end users or facility operations. Evaluate total cost of ownership rather than initial unit price alone, including replacement frequency, availability, service support, and compliance status. For commercial buyers, request evidence of testing and certification that matches the specific contaminants and use conditions relevant to the site. For retail and distribution partners, prioritize products that communicate performance clearly and can sustain consistent supply, since stockouts or inconsistent quality can quickly erode consumer confidence in a category where trust is central.
Closing Perspective
The water filters market is moving through a phase in which growth is supported by rising awareness, regulatory maturation, and continued product innovation, but value capture is increasingly tied to credibility, efficiency, and supply resilience. The combination of tighter contaminant reduction standards, expanded regional protocols, and input cost dynamics is reshaping the basis of competition. Companies that treat certification, water efficiency, and supply chain reliability as strategic assets are better positioned to convert market growth into durable advantage. For leaders seeking to act with confidence in a market that is both expanding and re-segmenting, detailed segment-level data, regional nuance, and tailored scenario analysis can make the difference between broad exposure and targeted opportunity. The full research report provides deeper segmentation data, regional detail, and customized strategic guidance for those looking to translate these trends into specific commercial decisions.
For detailed analysis of this topic, please visit the official page: Water Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


