



Borosilicate Glass Tubes Market: Why the 6.8% CAGR Through 2032 Redefines Competition

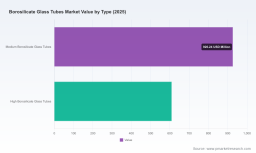
Strategic Trends & Commercial Opportunities in the Borosilicate Glass Tubes Market
Market Landscape and Core Pressures
The global borosilicate glass tubes market has demonstrated steady expansion over the past five years, moving from approximately $1.05 billion in 2020 to an estimated $1.54 billion in 2025. The trajectory reflects a compound annual growth rate of roughly 6.8 percent through 2032, with revenue projected to approach $2.4 billion by the end of the forecast period. This growth is not merely incremental; it is reshaping how manufacturers, procurement teams, and investors evaluate capacity, feedstock security, and long-term contract structures.
Behind the headline figures lies a market that is simultaneously broadening in application scope and tightening in operational discipline. Demand is no longer concentrated in traditional laboratory and chemical handling roles. Solar energy collection systems, pharmaceutical primary packaging, and heat-resistant industrial glassware are absorbing a growing share of production capacity. At the same time, the market remains moderately consolidated, with the top five producers accounting for just under half of total revenue. This concentration creates a landscape where scale, certification depth, and regional footprint matter, but it also leaves room for specialized players to compete on niche specifications, localized service, or sustainability credentials.
Key Challenges Shaping Strategic Positioning
Three pressures are forcing a recalibration of how incumbents and new entrants plan their next investment cycles.
- Feedstock volatility and constrained supply alternatives. Boric oxide and high-purity silica sand remain the foundational inputs for borosilicate formulations. The supplier base is limited, and disruptions in logistics or regional demand shifts can quickly translate into price moves at the tube level. Periodic spikes in boron-related costs have already rippled through procurement budgets, particularly when freight rates fluctuate or agricultural and industrial end-users compete for the same material pools.
- Regulatory alignment and certification overhead. Pharmaceutical and medical-grade applications demand strict adherence to quality management systems, including GMP-aligned certifications and traceable manufacturing controls. Maintaining compliance across multiple sites and product lines adds operational complexity. As global sourcing becomes more fragmented, buyers increasingly verify not just product specifications but the certification status of every production node in the supply chain.
- Carbon intensity and energy transition expectations. Energy-heavy melting processes sit at the core of glass tubing production. Rising interest in lower-carbon materials, coupled with procurement policies that factor environmental performance into supplier selection, is pushing manufacturers to reconsider furnace technology, energy sourcing, and process efficiency. Facilities that continue to rely on conventional thermal profiles may face growing friction in tenders where lifecycle emissions or renewable energy usage are evaluated alongside cost and quality.
Core Drivers Propelling Market Evolution
The expansion of borosilicate glass tubes is being pulled by a combination of technical, regulatory, demand-side, and supply-chain forces. Understanding which drivers are structural versus cyclical helps decision-makers prioritize where to allocate capital and operational attention.
Technical Innovation and Process Breakthroughs
Advances in melting technology and product formulation are changing what is commercially feasible. The introduction of all-electric melting furnaces powered by renewable energy represents a meaningful shift in how pharmaceutical-grade tubing can be produced at scale. By reducing reliance on fossil-derived heat, manufacturers can lower process emissions while maintaining the tight tolerances required for vials, cartridges, syringes, and laboratory capillaries. This development is not only an environmental milestone; it also creates a differentiator in procurement discussions where buyers increasingly weigh carbon performance alongside dimensional stability and breakage resistance.
In parallel, continuous improvements in tubing consistency, wall thickness control, and surface quality are expanding the usable range of borosilicate tubes in high-precision applications. For pharmaceutical packaging and laboratory apparatus, reliability across batches is critical. Producers that can demonstrate tighter process control and reliable certification coverage are better positioned to win long-term supply agreements, particularly in regions where local content preferences or risk-mitigation strategies favor domestic or nearshore sourcing.
Policy and Regulatory Environment
Regulatory dynamics are reinforcing demand for certified borosilicate glass in pharmaceutical and medical contexts. Quality management standards, GMP-aligned production requirements, and increasingly rigorous traceability expectations are raising the barrier to entry for non-specialized suppliers. Importantly, these requirements are not static. As health authorities and procurement organizations tighten expectations around material compatibility, contamination control, and supplier validation, the value of established certification portfolios grows.
Trade and sourcing patterns are also evolving. European import flows for borate materials have shown upward movement in recent years, with Türkiye continuing to play a central role as a supply origin. Such patterns highlight the interdependence between regional availability and production planning. Manufacturers that rely on a narrow set of feedstock channels must monitor geopolitical and trade developments closely, since shifts in import volumes or tariff structures can affect both cost and continuity.
Demand-Side Shifts in End-Use Behavior
Demand is being reshaped by how end users prioritize performance, sustainability, and supply resilience. In pharmaceutical packaging, the continued emphasis on primary container integrity and patient safety keeps borosilicate tubing at the center of vial and ampoule production. For laboratory and scientific applications, the need for chemically resistant, thermally stable glass remains a durable base load for the market.
At the same time, new application momentum is emerging from solar energy systems that utilize borosilicate-based tubes, alongside heat-related industrial glassware where temperature resistance and durability are essential. These segments do not just add volume; they change the specification mix. Buyers in these areas often weigh total cost of ownership, operational lifespan, and environmental exposure more heavily than upfront price alone. That shift encourages manufacturers to think beyond commodity supply and toward application-tailored performance, technical support, and longer-cycle partnerships.
Supply Chain and Cost Structure Dynamics
Cost structures are being tested by the intersection of energy pricing, feedstock availability, and logistics. Boron-related pricing has exhibited sensitivity to freight movement and seasonal demand from both glass manufacturing and agriculture, underscoring how even specialized materials can be influenced by broader commodity cycles. Because high-purity silica sand and boric oxide have limited comparable suppliers globally, supply-chain vulnerabilities are not theoretical; they are operational realities that can affect scheduling, margin planning, and customer commitments.
In response, several producers are rethinking geographic distribution of capacity. New facilities and joint ventures in key demand regions are intended to shorten lead times, reduce transport exposure, and improve responsiveness to local specification requirements. This regionalization trend also intersects with customer preferences for lower-risk sourcing, especially where pharmaceutical or regulated applications are concerned. The net effect is a market in which proximity, certification readiness, and feedstock management are becoming as strategically relevant as production scale alone.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a set of established players with deep application expertise, strong brand recognition in specific verticals, and increasingly visible efforts to align capacity with demand geography and sustainability expectations.
Quartz Tubing Market
Strategic Positioning of Leading Companies
Corning Incorporated continues to assert its position as a leading supplier of Type I borosilicate glass tubing for pharmaceutical primary packaging. Its focus on products such as Corning® 51 and Corning® 33 tubing underscores a strategy centered on regulatory-grade quality, pharmaceutical compatibility, and broad packaging formats including vials, ampoules, cartridges, and syringes. Recent activity includes the inauguration of a new pharmaceutical glass tubing manufacturing facility in India developed with joint venture partner SGD Pharma, alongside a move to strengthen the European production base through SGD Pharma's acquisition of Alphial S.r.l. These steps suggest a deliberate combination of regional capacity expansion and consolidation of pharmaceutical tubing assets.
SCHOTT AG maintains a prominent global presence in Type I borosilicate tubing through the FIOLAX® and DURAN® brands, covering pharmaceutical and laboratory applications across an extensive range of glass types. Its multi-product portfolio and long-standing certification infrastructure position it well for customers who require broad specification coverage and documented quality systems. The emphasis on maintaining ISO 9001 and ISO 15378 (GMP) certifications across tubing production sites reflects a strategic priority on compliance assurance and buyer confidence in regulated markets.
DWK Life Sciences focuses on premium laboratory borosilicate glass 3.3, including DURAN® tubing, rods, and capillaries for scientific, chemical, and industrial use. Its specialization supports a strategy built on application depth in laboratory and chemical contexts, where consistent quality and recognized brand trust matter highly. By concentrating on scientific and industrial performance rather than broad pharmaceutical packaging, DWK Life Sciences occupies a distinct flank in the market.
Nipro Corporation operates as a major global manufacturer of premium borosilicate tubing for pharmaceutical packaging, with multiple production sites supporting scale and regional flexibility. Its product range, including grades such as G38 and NSV51, highlights a pharmaceutical-oriented strategy with geographic breadth. This footprint supports continuity of supply and responsiveness across markets where packaging demand is growing or where localized production is preferred.
Nippon Electric Glass Co., Ltd. supplies BS-series borosilicate tubing for pharmaceutical containers and medical applications, and has recently drawn attention for beginning mass production of pharmaceutical glass tubing using an all-electric melting furnace with renewable energy at its Malaysia facility. This move positions the company at the intersection of quality-focused pharmaceutical supply and lower-carbon manufacturing, a combination that is likely to resonate with buyers assessing both performance and sustainability in their supplier evaluations.
Borosil Limited produces borosilicate glass tubes and rods for laboratory and scientific applications, representing a strong regional presence in a segment where trusted laboratory glassware remains a steady demand center. Its positioning shows how regional specialists can compete by aligning product range, service, and local market knowledge with the expectations of scientific and industrial buyers.
How the Landscape Is Evolving
The market is showing signs of both consolidation and targeted expansion. In pharmaceutical-grade tubing, activity suggests a push toward stronger regional production bases and bundled capability through partnerships or acquisitions. This is consistent with a broader pattern in which leading producers seek to reduce supply-chain distance, reinforce certification continuity, and capture growth in regions where pharmaceutical packaging demand is expanding.
At the same time, differentiation is increasingly multidimensional. Scale alone is no longer sufficient to secure advantage. Buyers compare suppliers on certification depth, energy and carbon profile, application-specific reliability, and logistics resilience. As a result, competition is becoming more segmented: some players compete primarily on pharmaceutical compliance and volume, others on laboratory-grade specialization, and a growing set of evaluators are paying attention to low-carbon process technology as a criterion in supplier selection.
New entrants and regional specialists can still find room by addressing localized needs, offering responsive service, or developing expertise in specific tube grades, dimensions, or end-use requirements. However, the certification burden and feedstock complexity mean that credibility and operational discipline are necessary for durable participation, especially in regulated segments.
Forward-Looking Trends and Commercial Implications
Looking across the 2026–2032 window, several trends are likely to shape where value accrues and where risk concentrates.
Trend 1: Regionalization of Pharmaceutical-Grade Capacity
Pharmaceutical packaging demand is expected to remain a central growth engine, and producers will continue to align capacity more closely with key demand regions. This regionalization reduces exposure to long logistics chains, supports faster response times, and can improve alignment with local sourcing expectations. For commercial actors, the implication is clear: supply relationships will increasingly favor vendors who can demonstrate not only product quality but also production proximity, local certification coverage, and predictable continuity.
Commercial opportunity lies in multi-year supply arrangements, technical co-development around container formats, and resilient backup sourcing strategies. Buyers can use regional capacity to reduce lead-time variability, while producers can use localized facilities to strengthen customer stickiness and expand share in growing markets.
Trend 2: Sustainability as a Procurement Filter
Lower-carbon production methods are moving from experimental narrative to commercial relevance. The adoption of all-electric melting and renewable energy sourcing in pharmaceutical tubing production signals that environmental performance can be integrated into high-precision manufacturing without abandoning the quality demands of regulated applications. As procurement teams broaden evaluation criteria, suppliers with demonstrable energy and emissions advantages may gain preference in tenders, particularly where corporate sustainability commitments or customer expectations create additional pressure.
PW Consulting
This trend creates opportunities for manufacturers to differentiate through process innovation and for buyers to align supply choices with broader environmental targets. The uncertainty lies in how consistently sustainability metrics will be weighted against cost, quality, and reliability across different regions and industries. Producers that invest early in measurable, verifiable improvements are better positioned than those that rely on generalized claims.
Trend 3: Application Diversification and Specification Complexity
demand is gradually broadening beyond traditional laboratory and chemical uses toward solar energy tubes, heat glassware, and other specialized applications. This diversification introduces both opportunity and complexity. Different applications impose different requirements on thermal performance, chemical resistance, dimensional tolerance, and lifecycle durability. Suppliers that can manage specification complexity while maintaining efficient production are more likely to capture margin across a wider set of use cases.
For buyers, the opportunity is to secure materials that fit long-term operational needs rather than simply meeting immediate cost targets. For suppliers, the risk is that spreading capacity across too many divergent specifications can erode efficiency if not managed with disciplined product architecture and demand forecasting.
Risk and Uncertainty Considerations
Several variables could alter the pace or distribution of growth. Feedstock availability and price movement remain a persistent risk, particularly where supplier alternatives are limited. Energy costs and the pace of transition to lower-carbon furnace technology will influence both operating economics and competitive positioning. Trade dynamics, including shifting import volumes and origin patterns for borate materials, can affect cost structures and sourcing strategies. Finally, demand timing in newer applications such as solar-related tubes may be uneven, creating pockets of rapid adoption in some regions or customer segments while remaining more gradual in others.
Borosilicate Glass Market
Strategic flexibility is essential. Organisations that lock into single-source feedstock arrangements, rigid capacity plans, or narrow application bets without monitoring these variables may find themselves exposed to cost shocks or demand mismatches.
Actionable Recommendations for Decision-Makers
Different roles in the value chain should prioritize different decisions, but all benefit from a clearer view of where market momentum is building and where vulnerability is accumulating.
For Manufacturers and Producers
- Align capacity expansion with regional demand centers and regulatory expectations. Where pharmaceutical or laboratory demand is growing, evaluate whether local or nearshore production can improve service levels and reduce logistics exposure.
- Invest in process differentiation that can be verified, not just promoted. All-electric melting, renewable energy integration, and documented certification coverage are examples of attributes that can be demonstrated to buyers and procurement teams with increasing scrutiny.
- Strengthen feedstock strategy. Diversify sourcing where feasible, monitor boron and silica supply dynamics, and build contingency planning into procurement and production schedules to reduce vulnerability to price or availability shocks.
- Manage specification complexity deliberately. Expanding into new application areas can be profitable, but only if product architecture, quality systems, and forecasting are designed to support varied requirements without sacrificing efficiency.
For Investors and Strategic Planners
- Focus on structural drivers rather than short-term volume spikes. The combination of pharmaceutical packaging demand, laboratory stability, and emerging application segments provides a multi-engine growth path, but the durability of each engine depends on regulatory continuity, feedstock stability, and energy economics.
- Evaluate competitive advantage through a broader lens. Scale remains relevant, but certification depth, regional footprint, process sustainability, and application specialization increasingly determine which players can defend pricing and win long-term contracts.
- Track consolidation signals and partnership activity. Joint ventures, facility launches, and acquisitions in pharmaceutical tubing indicate where incumbents believe durable value will be created. These moves can reveal shifts in regional strategy and capacity control.
- Incorporate supply-chain resilience into valuation and planning. Feedstock concentration and energy transition costs can affect margins and operational continuity, making them relevant to risk assessment as well as growth potential.
For Procurement and Sourcing Leaders
- Broaden supplier evaluation criteria. Quality and price remain essential, but certification coverage, production location, energy and carbon profile, and contingency capability should be part of the decision framework, especially for regulated or long-life applications.
- Use regional availability as a risk-mitigation lever. Where possible, balance global sourcing with regional or nearshore options to reduce lead-time variability and improve responsiveness to specification changes or urgent requirements.
- Engage earlier on application requirements. For solar, heat glassware, pharmaceutical packaging, and laboratory use, aligning on performance expectations and lifecycle needs before procurement can reduce rework, incompatibility risk, and total cost over time.
- Plan for feedstock and energy volatility. Build flexibility into contracts and inventory strategies where feasible, and monitor commodity and trade developments that can influence borosilicate tube costs and availability.
Closing Perspective
The borosilicate glass tubes market is moving through a phase in which growth is increasingly tied to application breadth, regulatory confidence, supply resilience, and process sustainability. The market's expansion from roughly $1.05 billion in 2020 toward nearly $2.4 billion by 2032 reflects more than incremental demand; it signals a shift in how value is created and protected. Feedstock constraints, certification expectations, and energy transition pressures are not marginal concerns. They are shaping supplier selection, capacity planning, and the definition of competitive advantage.
For manufacturers, the priority is to match capacity and differentiation with where demand is becoming most durable. For investors, the task is to distinguish structural growth from cyclical noise and to assess whether competitive positioning can withstand feedstock, energy, and trade volatility. For procurement leaders, the opportunity lies in using broader evaluation criteria to secure supply that supports both operational reliability and longer-term strategic goals.
Deeper segmentation data, region-by-region dynamics, application-level demand patterns, and company-specific strategic assessments can sharpen these decisions further. Detailed market intelligence is especially valuable when sizing growth opportunities in newer applications, evaluating the pace of regional capacity shifts, or benchmarking supplier claims against operational realities. In a market where feedstock, regulation, and sustainability expectations are all moving at once, timely and granular insight can make the difference between reactive sourcing and proactive strategy.
For detailed analysis of this topic, please visit the official page: Borosilicate Glass Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


