



Automated Material Handling Equipment: Why $52.16B in 2025 Changes Everything

The Automated Material Handling Equipment Market: Strategic Trends and Commercial Opportunities
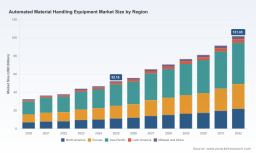
The global market for automated material handling equipment has reached a decisive inflection point. Valued at approximately $52.16 billion in 2025, the sector has expanded from $32.39 billion in 2020, reflecting a compound annual growth rate of 10.6% through the 2026–2032 forecast horizon. By the end of the projection period, revenue is expected to surpass $101.65 billion. This trajectory is not merely a function of incremental efficiency gains; it signals a structural reorientation of how goods are moved, stored, and sorted across manufacturing, distribution, and e-commerce ecosystems. The equipment category encompasses automated guided vehicles, conveyor and sorting systems, and automated storage and retrieval platforms, each addressing distinct operational pain points but increasingly converging through software-defined control layers and unified fleet orchestration.
Growth has been uneven but persistent across the historical window, with notable acceleration in recent years as labor market pressures, e-commerce fulfillment expectations, and supply chain redundancy requirements aligned. The market remains moderately fragmented, with the top five players collectively accounting for roughly 30% of revenue, indicating ample room for regional specialists, niche innovators, and well-capitalized consolidators. Executive teams evaluating capital allocation, capacity planning, or technology roadmaps must recognize that this is no longer a peripheral automation play. Material handling automation has become a core determinant of throughput scalability, labor flexibility, and real estate optimization. The following analysis examines the structural challenges shaping the market, the forces driving adoption, the evolving competitive architecture, and the strategic implications for operators, investors, and technology decision-makers.
Market Reality and the Defining Challenges
The headline growth figures mask a market navigating several simultaneous tensions. First, the distinction between nominal order value and real demand intensity has blurred. Rising input costs for steel, aluminum, and electronic components have pushed system pricing higher, inflating nominal revenue figures while complicating return-on-investment calculations for end users. Procurement teams are therefore scrutinizing total cost of ownership more rigorously, shifting conversations from unit price to lifecycle economics, energy consumption, and changeover flexibility.
Second, integration complexity remains a persistent barrier. Facilities rarely adopt a single equipment class in isolation. A typical deployment pairs autonomous mobile robots or guided vehicles with conveyor networks, storage retrieval systems, and warehouse execution software. The marginal benefit of each addition depends on data interoperability, safety zone management, and change management across shifts. Organizations that treat automation as a plug-and-play hardware purchase frequently encounter bottlenecks in commissioning, operator training, and downstream process alignment. The gap between purchasing equipment and realizing throughput gains continues to separate experienced integrators from inexperienced buyers.
Third, the operational environment is being reshaped by updated safety and integration expectations. Revised standards for automated guided vehicles have introduced clearer guidance on risk assessment, human-machine interaction zones, and fleet coordination. Compliance is no longer a checkbox exercise; it influences layout design, sensor selection, and software architecture. Companies that internalize these requirements early gain smoother commissioning paths, while those that retrofit controls after deployment face rework costs and schedule delays.
Implications for Decision-Makers
The practical takeaway is that equipment selection must be evaluated within a systems context. Leadership teams should assess whether their facilities have the data infrastructure, maintenance capabilities, and workforce readiness to absorb automation without creating new constraints. Projects that begin with process mapping, bottleneck identification, and clear performance targets tend to outperform those that start with a generic equipment specification.
Forces Reshaping Demand and Deployment
Several interconnected drivers explain why material handling automation is moving from selective adoption to broad-based necessity. Understanding these forces helps separate durable trends from cyclical noise.
Technology convergence is expanding the addressable use case. Autonomous mobile robots and guided vehicles have matured from fixed-path cart replacements to flexible fleet assets capable of dynamic routing, load balancing, and work assignment. Meanwhile, conveyor and sorting systems continue to improve in modularity and throughput density, and automated storage and retrieval platforms are becoming more adaptable to variable SKU profiles and mixed pallet handling. The real breakthrough lies in orchestration: software layers that translate order profiles, labor availability, and equipment status into sequenced movements. Facilities are increasingly evaluating fleets as unified workforces rather than isolated machines, which raises the strategic value of interoperable controls and open architecture.
Labor economics and operational resilience are accelerating adoption. Sustained wage pressure, turnover variability, and the need for consistent shift coverage are pushing operators toward equipment that can sustain throughput without proportional headcount growth. At the same time, supply chain disruptions have reinforced the value of predictable internal flow. Distribution and assembly environments, where speed and accuracy directly affect customer commitments, are leading adoption because automation there translates into measurable service-level improvements and reduced congestion during peak windows.
Regulatory and safety frameworks are maturing. The updated AGV standard provides clearer expectations for safe operation in shared spaces, influencing how vendors design navigation, sensing, and fallback behavior. Facilities that plan around these expectations from the outset can reduce rework and accelerate acceptance from safety teams and floor operators. For vendors, alignment with recognized safety expectations is becoming a competitive differentiator, especially in regulated or unionized environments where documented risk management matters.
Input cost dynamics are reshaping procurement strategies. Higher material and component costs have increased nominal project valuations, but they have also incentivized more disciplined scoping. Buyers are prioritizing incremental deployments, phased rollouts, and equipment that can be repurposed across seasons or product lines. This environment rewards vendors that offer scalable configurations, transparent pricing models, and integration support that reduces hidden failure costs.
What This Means in Practice
Organizations should treat automation decisions as multi-year operating model choices rather than single-cycle capital purchases. The most resilient strategies combine flexible hardware, software visibility, and workforce development plans. Vendors and integrators that can demonstrate measurable improvements in labor utilization, error reduction, and space efficiency will find stronger positioning than those competing solely on hardware features.
PW Consulting
Competitive Architecture and Strategic Positioning
The competitive landscape blends established global integrators, specialized equipment manufacturers, and increasingly ambitious regional players. Daifuku, Jungheinrich, KION Group, SSI SCHAEFER, Toyota Industries, BEUMER Group, Honeywell Intelligrated, Murata Manufacturing, KUKA, Dematic, Hyster-Yale, and Vanderlande each bring distinct strengths, but the market is not settling into a single template. Differentiation increasingly depends on the ability to combine hardware reliability with software orchestration, service responsiveness, and integration discipline.
Japanese and European incumbents with broad intralogistics portfolios continue to benefit from deep engineering heritage and global service networks. Companies offering end-to-end systems—from storage retrieval and sorting to vehicle fleets and control software—are well positioned for large, multi-zone facilities where process continuity matters more than component-level price competition. Their advantage lies in managing complexity across disciplines, reducing the coordination burden on the customer, and maintaining performance across mixed workflows.
Regional specialists and technology-focused entrants are carving out roles by targeting specific pain points or deployment models. Some emphasize omnidirectional handling, compact footprints, or rapid reconfiguration for high-mix environments. Others focus on software-driven fleet management, digital twin visualization, or simplified commissioning workflows. These entrants often win in scenarios where a customer needs a targeted improvement, a pilot-scale validation, or a solution that can be absorbed by a smaller engineering team. The presence of such players increases overall market dynamism and pushes larger incumbents to improve modularity and responsiveness.
Market Evolution Patterns
Consolidation is accelerating where it creates scale in service, software, and project delivery. Recent activity illustrates how ownership changes and brand repositioning are reshaping the landscape. The acquisition of Honeywell’s warehouse and workflow solutions division, including Intelligrated, by American Industrial Partners highlights interest in mature automation capabilities with established deployment track records. At the same time, brand transitions such as Pyramid’s emergence for Matthews Automation Solutions after Duravant’s acquisition signal that portfolio rationalization and clearer market positioning are becoming priorities. These moves matter because they affect post-deployment support, product roadmaps, and the continuity of software updates—factors that customers weigh heavily when selecting partners for multi-year operations.
Exhibition activity and product launches further reveal where innovation is concentrated. Demonstrations of advanced AMR and AGV platforms, omnidirectional pallet forklifts, and digital twin-enabled logistics systems indicate a market increasingly focused on flexibility, visibility, and faster commissioning. Next-generation vehicle introductions and smarter orchestration tools are not isolated events; they reflect an industry-wide push to reduce integration friction and make automation more accessible to facilities that previously considered such projects too complex or too capital-intensive.
Strategic Positioning Takeaways
Winning in this market requires more than hardware competence. Leaders combine dependable equipment with integration services, lifecycle support, and software that helps customers manage mixed fleets and changing order profiles. For customers, the practical question is not which vendor has the broadest catalog, but which partner can own the most difficult parts of deployment, training, and ongoing optimization within the customer’s operating context.
Worldwide Automated Storage Retrieval System Market
Forward Outlook: The Next Three to Five Years
The next phase of growth will be shaped by how the market resolves current tensions and expands into new operational contexts. Three developments are particularly consequential.
Fleet orchestration will become a primary value driver. As facilities operate mixed equipment sets—guided vehicles, autonomous mobile robots, conveyors, and retrieval systems—the competitive edge will shift toward software that coordinates work assignment, exception handling, and performance visibility across asset types. Customers will increasingly evaluate automation based on how smoothly it adapts to demand spikes, product mix changes, and staffing variability. Providers that deliver transparent dashboards, predictive upkeep signals, and configuration flexibility will be better positioned to defend margins and deepen customer relationships.
Modularity and phased deployment will broaden adoption. Large greenfield automation projects will remain important, but a growing share of activity will come from modular upgrades and incremental rollouts. Facilities will favor equipment that can be installed with minimal disruption, expanded as throughput grows, and repurposed when layout or product strategy changes. This trend favors vendors that can offer standardized building blocks, clear integration interfaces, and project plans that reduce downtime during cutover. It also increases the importance of simulation and digital twin tools, which let teams test layouts and workflow changes before physical installation.
Regional growth dynamics will diverge. Asia Pacific continues to represent the largest revenue share, reflecting the scale of manufacturing, distribution modernization, and e-commerce infrastructure investment in the region. Europe and North America remain strong contributors, driven by labor cost pressures, warehouse modernization, and stricter operational expectations. Emerging regions will grow from a smaller base but offer meaningful upside for vendors that can localize support, adapt to varying facility standards, and price solutions appropriately for different maturity levels. The market will not move uniformly; success will depend on aligning product complexity and service models with local buying conditions.
Material Handling Robotics Market Research
Risks and Uncertainties
Several factors could alter the pace or shape of growth. Persistent input cost volatility can compress project budgets or delay decisions if buyers cannot justify commitments under uncertain margin scenarios. Integration risk remains significant; projects that underestimate data compatibility, safety onboarding, or workforce change management may underperform and dampen enthusiasm for subsequent deployments. In addition, standards and safety expectations will continue to evolve, and vendors or customers that lag behind may face rework, compliance friction, or reputational exposure. Finally, the balance between in-house integration capability and outsourced partnering will influence outcomes. Organizations with limited internal expertise may depend heavily on vendors and system integrators, making partner quality and contract structure unusually important.
Actionable Priorities for Decision-Makers
Different stakeholders should focus on distinct but overlapping priorities as they navigate this market.
For manufacturers and operators planning automation: Begin with process clarity before equipment selection. Map the highest-friction flows, identify where variability undermines throughput, and define the operational outcomes that automation must deliver. Prioritize solutions that can integrate with existing control and data environments, and structure deployments in phases that allow performance validation before larger commitments. Invest in operator training and maintenance readiness early; the best equipment underperforms when the team lacks confidence in exception handling or changeover procedures. Where possible, favor modular architectures that allow expansion without full redesign, and evaluate total cost of ownership across energy, maintenance, downtime, and floor space utilization rather than focusing narrowly on purchase price.
For investors and corporate development teams: Value creation will increasingly come from software-enabled differentiation, service scalability, and portfolio alignment rather than hardware volume alone. Assess targets for their ability to manage integrated deployments, maintain software continuity, and support mixed-fleet environments. Watch for ownership changes and brand rationalization as indicators of strategic intent and post-merger service stability. Consider the growing importance of regional execution capability; companies that can localize integration, training, and support often capture share more durably than those competing only on specification sheets. Also monitor the shift toward orchestration and visibility tools, as these create recurring engagement points and can improve customer retention when they demonstrably reduce operational friction.
For procurement and technology buyers evaluating suppliers: Look beyond equipment features to integration discipline and lifecycle support. Ask how a vendor handles mixed-fleet coordination, exception resolution, safety compliance, and post-commissioning optimization. Verify that proposed layouts and workflows have been validated through simulation or pilot evidence where feasible, and clarify ownership of software updates, spare parts availability, and escalation paths. Structured selection processes that weigh deployment risk, service responsiveness, and adaptability to future layout changes will reduce the likelihood of costly rework and improve long-term performance.
Closing Perspective
The automated material handling equipment market is moving from a phase of selective adoption to one of broader operational dependence. Growth to more than $100 billion by the early 2030s reflects a structural shift in how facilities manage labor, throughput, and space under tighter service expectations and more volatile operating conditions. The organizations that benefit most will be those that treat automation as a coordinated system, align equipment choices with process realities, and build the internal capabilities needed to sustain performance after deployment.
Detailed segmentation, regional dynamics, and company-level profiling can materially improve capital planning, supplier selection, and investment prioritization. For teams that require granular data and tailored scenario analysis, the full market research report provides deeper breakdowns and structured guidance to support execution.
For detailed analysis of this topic, please visit the official page: Automated Material Handling Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


