



Feed Yeast Market: Why Live Yeast and Poultry Dominance Drive a 5.1% CAGR Through 2032

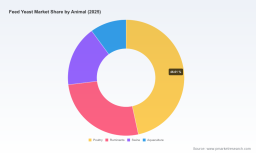
Navigating the Feed Yeast Market: Strategic Trends and Commercial Opportunities Through 2032
The global feed yeast market is entering a phase of measured but deliberate expansion. Over the past five years, the industry has evolved from a commodity-focused segment into a value-driven arena where strain specificity, functional efficacy, and supply chain reliability increasingly dictate purchasing decisions. By 2025, total market revenue reached approximately $150 million, reflecting a sustained upward trajectory from $115 million in 2020. The sector is projected to grow at a compound annual rate of 5.1 percent through 2032, when revenue is expected to approach $210 million. This growth profile signals more than incremental demand; it points to a structural shift in how livestock producers, aquaculture operators, and feed formulators view yeast-based inputs as functional nutrition tools rather than routine additives.
That said, the expansion is uneven, and the landscape carries notable friction. Market concentration remains pronounced, with the top three players accounting for roughly 65 percent of global revenue and the top five capturing over 82 percent. Such concentration reflects the capital intensity of modern fermentation infrastructure, the importance of technical service and veterinarian-level support, and the increasingly regionalized nature of regulatory requirements. For decision-makers, the implication is clear: scale alone no longer guarantees advantage. Differentiation, formulation expertise, and the ability to navigate shifting trade and compliance frameworks are becoming the decisive factors.
PW Consulting
Market Evolution and Structural Pressures
The feed yeast segment has matured along several axes simultaneously. Demand is being reshaped by tighter antibiotic restrictions, heightened scrutiny of gut health performance, and the broader movement toward preventive nutrition in monogastric and ruminant production. At the same time, the product portfolio has diversified beyond traditional live yeast into derivatives and spent yeast streams, each appealing to different technical and economic priorities. This evolution is not merely a story of more SKUs; it reflects a marketplace in which buyers are increasingly willing to trade a modest premium for measurable benefits in digestibility, pathogen binding, or stability during feed pelleting and storage.
Within this environment, a few structural pressures stand out as defining challenges for the next cycle. First, raw material economics create persistent volatility. The fermentation feedstock base that underpins Saccharomyces cerevisiae production remains sensitive to grain and energy inputs, and the average annual price for the core yeast input still ranges between $800 and $1,200 per metric ton as of 2025. This cost structure pressures margins and limits the ability of smaller players to compete on volume without sacrificing consistency or lead times. Second, trade policy is becoming a more material driver of regional pricing and sourcing decisions. In February 2026, a U.S. executive order introduced a 6.4 percent tariff on inactive yeasts under a specific tariff classification, excluding dried brewers’ yeast. While the measure does not apply uniformly across all feed yeast categories, it underscores how rapidly tariff exposure can alter the economics of cross-border supply and encourages buyers to reconsider sourcing portfolios. Third, regional production leadership is shifting the center of gravity in the market. China’s annual output now exceeds 200,000 tonnes and is primarily directed toward Asian and European markets, reinforcing a supply chain dynamic in which volume availability and export logistics play an outsized role in regional pricing behavior.
Core Drivers Reshaping the Market
Several interlocking forces are driving the current trajectory of the feed yeast market. Understanding these drivers is essential for evaluating where growth will materialize and which capabilities will translate into durable advantage.
Technological and Strain-Level Innovation
Innovation in this market is increasingly centered on strain selection, propagation efficiency, and functional reliability under real-world feeding conditions. The competitive edge is shifting from generic yeast inputs toward formulations designed for specific gastrointestinal targets, such as rumen stability, pathogen binding, or resilience during thermal processing. For producers, this means that manufacturing scale must be paired with application science: a large fermentation capacity is valuable, but the ability to document performance in target species and to provide technical guidance on inclusion rates and integration with other additives is what converts production capability into recurring demand. The industry context reinforces the point. Major producers operate fermentation infrastructure with annual capacity above 100,000 tonnes, yet the most differentiated offerings are increasingly defined by their functional claims and the evidence supporting them.
Regulatory and Compliance Environment
Regulatory dynamics are now a strategic variable rather than a background condition. Feed additives face varying approval pathways, renewal cycles, and labeling expectations across major markets. In Europe, for example, Alltech’s Yea-Sacc® yeast culture continues to be authorized for use in cattle feed under EFSA oversight, with renewals ongoing through 2025. Such continuity matters because it shapes buyer confidence in long-cycle procurement, especially for ruminant applications where health claims and compliance documentation carry significant weight. At the same time, the U.S. tariff action on certain inactive yeast categories illustrates the broader point that trade policy can alter the cost base of specific product types and incentivize formulation or sourcing shifts. Companies that actively monitor these regulatory and tariff signals, and that design portfolios with flexibility in mind, are better positioned to absorb shocks and preserve margin.
Yeast Market
Demand-Side Behavior and Animal Nutrition Priorities
The demand landscape is being reshaped by a combination of animal production economics and an evolving nutrition philosophy. Livestock operators are placing greater emphasis on gut health, feed conversion efficiency, and resilience to stress, especially in environments where preventive health strategies are replacing reactive treatments. Yeast-based inputs are increasingly evaluated through that lens: their value proposition is tied not only to nutrient contribution but also to functionality such as stabilization of the gastrointestinal environment, modulation of microbial balance, or binding of undesirable compounds. As a result, procurement decisions are becoming more evidence-driven, and buyers are more likely to seek technical support, trial data, and integration guidance alongside product specifications. This shift favors suppliers that can act as solution partners rather than simple vendors.
Supply Chain and Cost Structure Dynamics
Feed yeast production remains a scale-sensitive business. Fermentation, downstream processing, drying, and logistics all carry capital and operating requirements that reward continuity and keep smaller, underfunded entrants at a disadvantage. At the same time, the rise of integrated and cross-industry ownership is altering the supply base. A notable example is the acquisition of Leiber GmbH by Asahi Group Foods in March 2025, which consolidated brewers’ yeast production for both animal nutrition and food ingredient applications. Transactions of this type are not merely financial; they change operational priorities, improve access to certain raw material streams, and can create new avenues for cross-segment demand. For the feed yeast market, such moves hint at a broader trend in which ingredient producers seek to secure feedstock consistency, expand application portfolios, and reduce exposure to single-market volatility.
Competitive Landscape and Emerging Positioning
The competitive structure of the feed yeast market is dominated by a mix of global animal nutrition specialists, large ingredient companies, and regional producers with strong fermentation capabilities and technical service networks. The top players are not interchangeable; their strategic positioning reflects differences in geography, portfolio depth, application focus, and ownership structure. What unites the stronger performers is a tendency to build advantage around functional reliability and end-user support rather than price alone.
Among the firms shaping the current landscape, several patterns stand out. Angel Yeast has built a broad feed yeast portfolio spanning live yeast, inactive yeast, yeast extracts, and mycotoxin binders, and its scale-oriented production model is reinforced by participation in major trade forums such as SPACE 2025, where it showcased its full range of feed yeast solutions. This combination of volume capability and market-facing visibility helps the company maintain relevance across multiple buyer segments. Alltech continues to emphasize a more focused, science-backed approach through its Yea-Sacc® yeast culture for rumen health, leveraging regulatory continuity in Europe to support confidence in cattle feed applications. Lallemand and Lesaffre contribute from positions grounded in yeast strain expertise and broader animal health portfolios, often competing on the strength of application data and integrated nutrition messaging. Leiber’s position has evolved further following its acquisition, aligning brewers’ yeast capabilities with a larger group’s ingredient strategy and potentially expanding cross-market leverage. ADM, Novus, AB Agri, Chr. Hansen, Nutreco, and DSM-Firmenich each bring their own angles, whether through animal nutrition divisions, yeast cell wall components, or broader feed additive portfolios that incorporate yeast-derived inputs as part of a wider value proposition.
The market is not simply consolidating; it is also differentiating. Some players are moving toward integrated, multi-functional product systems, while others maintain a sharper focus on specific species or functional claims. The trend suggests a bifurcation in which scale and operational reliability protect share in commoditized segments, while application-specific formulation, documentation, and technical service drive growth in more demanding use cases. New entry is likely to remain difficult without access to fermentation capacity, regulatory fluency, and a credible technical narrative. At the same time, acquisition activity and cross-industry ownership may increase, especially where ingredient streams, regional distribution, or application expertise can be combined to create a stronger commercial position.
Worldwide Nutritional Yeast Market
Forward Outlook: Three Trends to Watch
Looking ahead to the 2026–2032 period, three developments are likely to define the commercial trajectory of the feed yeast market.
The first is a gradual shift from generic supplementation toward function-targeted formulations. As buyers increasingly evaluate yeast inputs for specific outcomes—such as rumen performance, gut stability, or resilience under stress—the market will reward products with clearer application narratives and stronger supporting evidence. Companies that invest in species-specific documentation, dosing guidance, and integration with other feed additives are more likely to secure repeat business and price resilience. The commercial opportunity here lies not just in product development but in the ability to translate technical claims into credible, practical recommendations for feed formulators and producers.
The second trend is regional recalibration of sourcing and pricing. Trade policy volatility, including tariff actions on certain inactive yeast categories, combined with concentrated production in key exporting countries, will encourage buyers to diversify supply sources and consider lead-time stability alongside unit cost. Suppliers with reliable export logistics, flexible packaging and specification options, and the ability to serve multiple regions will gain an edge. For manufacturers, regional demand growth will likely remain uneven, with some markets expanding faster as protein production intensifies and as nutrition programs become more preventive in design.
The third trend is continued portfolio and ownership consolidation, particularly where it enhances feedstock access, broadens application coverage, or strengthens technical service. Acquisitions that link yeast production with broader ingredient or food-grade operations can improve supply security and create cross-selling opportunities. At the same time, integration carries execution risk: differences in operating culture, quality systems, and customer expectations can complicate the anticipated benefits. The market will therefore reward operators that can combine scale with disciplined product stewardship and consistent technical support.
These trends carry both upside and uncertainty. Demand for functional nutrition is likely to remain supportive, but the pace of adoption will depend on economic conditions in animal production, the stringency of regulatory approvals, and the ability of suppliers to demonstrate consistent value. Cost pressures from feedstock inputs and the potential for additional trade measures also remain variables that can compress margins or shift competitive dynamics faster than expected. The companies best positioned to navigate this environment will be those that treat regulatory monitoring, supply resilience, and application documentation as core capabilities rather than peripheral concerns.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align fermentation scale with application credibility. Capacity provides optionality, but differentiation comes from strain performance, stability data, and the ability to guide customers through integration decisions. Building a portfolio that balances core volume products with more specialized, function-oriented offerings can help protect share while opening paths to higher-value engagements. Equally important is the discipline to track regulatory and tariff developments closely, because even narrow policy changes can reshape the economics of specific product types and influence sourcing preferences.
For investors, the market’s concentration pattern warrants attention. The dominance of a few large players suggests that scale, distribution, and technical service networks create meaningful barriers, but the presence of targeted acquisitions and cross-industry ownership also signals that value may be created through strategic combination rather than organic expansion alone. Due diligence should focus on the defensibility of functional claims, the stability of feedstock access, the exposure of each portfolio to trade and regulatory shifts, and the quality of customer support. In this market, durable growth is increasingly tied to reputation for reliability and efficacy, not simply to volume.
For procurement teams and feed formulators, the practical imperative is to evaluate yeast inputs as part of a broader nutrition strategy rather than as interchangeable commodities. Inclusion decisions should weigh functional performance, supply continuity, documentation quality, and the supplier’s ability to support integration with existing formulations. Diversifying sources where feasible can reduce exposure to regional disruptions and tariff fluctuations, while maintaining dialogue with suppliers that can provide species-specific guidance and consistent product quality. In an environment where pricing is influenced by both input costs and trade policy, proactive sourcing and evidence-based selection are likely to yield better outcomes than price-only comparisons.
The feed yeast market is moving toward a more demanding, more differentiated, and more regionally sensitive phase of its development. That shift creates opportunity for operators and buyers who treat functionality, compliance, and supply resilience as strategic assets. For decision-makers seeking a deeper view of segment trajectories, regional nuances, competitive positioning, and scenario-based implications, the full research report provides a more granular breakdown and tailored guidance to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Feed Yeast Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


