



Automotive Relay Market 2026: Why 6.2% CAGR and EV Demand Redefine Growth

Navigating the Automotive Relay Market: Strategic Trends and Commercial Opportunities
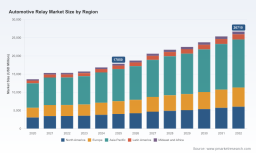
The automotive relay market is undergoing a structural transformation driven by vehicle electrification, evolving regulatory mandates, and shifting supply chain dynamics. Valued at approximately 17,850 million USD in 2025, the market has demonstrated consistent momentum over the past five years, expanding from roughly 13,600 million USD in 2020. This trajectory translates to a compound annual growth rate of 6.2 percent through 2032, positioning the segment as a steady contributor to broader automotive electrical components revenue. Rather than reflecting rapid disruption, the expansion pattern suggests incremental but persistent demand growth, underpinned by the increasing complexity of vehicle electrical architectures and the gradual replacement of mechanical switching components with more specialized relay solutions.
Regional and application distributions reveal a market that remains heavily anchored in established automotive manufacturing corridors, yet increasingly exposed to new demand vectors. Asia Pacific continues to command the largest share of overall volume, reflecting both legacy production capacity and accelerating domestic vehicle assembly. North America and Europe maintain substantial presence, though their growth profiles are increasingly shaped by regulatory timelines and platform-specific electrification strategies rather than pure volume expansion. From an application standpoint, powertrain and body/chassis systems remain the traditional volume anchors, while safety, HVAC, and battery management segments are gaining relative importance as vehicle electrical loads diversify. The market is also notably fragmented, with the top three participants capturing slightly under twenty percent of total revenue and the top five reaching roughly twenty-six percent, indicating that scale advantages exist but are not yet decisive enough to concentrate value exclusively among a handful of incumbents.
Key Challenges and Inflection Points
Despite the steady growth trajectory, the market faces several structural tensions that will define competitive outcomes over the next several years. The first challenge lies in reconciling traditional relay architectures with the electrical demands of modern vehicle platforms. As voltage levels rise and switching requirements become more bidirectional and high-frequency, conventional electromagnetic relays face performance and reliability constraints that necessitate redesigns, material substitutions, or migration toward alternative switching technologies in certain use cases. This creates a transitional period where suppliers must invest in new engineering capabilities without immediately retiring legacy product lines that still generate meaningful volume.
A second inflection point centers on cost structure volatility. Recent pricing actions across critical input materials, including contactors, relay accessories, glass epoxy multi-layer circuit board materials, and prepreg, signal a broader inflationary pressure on component production. These adjustments are not isolated procurement issues; they directly affect relay pricing feasibility, margin sustainability, and the ability of OEMs to absorb cost increases without altering component specifications or sourcing strategies. Suppliers that rely on rigid cost models or undifferentiated commodity positioning are especially exposed, while those with diversified material sourcing or integrated design capabilities are better positioned to manage fluctuations.
The third challenge involves the uneven pace of vehicle electrification across segments and geographies. While high-voltage and EV-related relay applications are expanding, the broader fleet transition remains staggered. Commercial vehicles, specialty platforms, and certain regional markets continue to rely on conventional electrical architectures, creating a hybrid demand environment where suppliers must simultaneously serve mature low-voltage applications and invest in higher-performance switching solutions. This dual demand profile complicates capacity planning, product roadmapping, and customer engagement strategies, particularly for manufacturers operating with limited flexibility across voltage classes and form factors.
Key Drivers Shaping Market Trajectory
Technological Innovation and High-Voltage Switching Evolution
Product development activity in the relay space increasingly reflects a shift from incremental refinement to targeted capability expansion. Recent launches illustrate how suppliers are responding to the need for compact, high-current, and gasless switching solutions tailored to next-generation electrification requirements. One notable example is the introduction of a high-voltage DC relay designed for 500 VDC and 120 A bidirectional operation, developed with a gasless plunger-type architecture that supports EV charging, battery systems, and power electronics applications while aligning with carbon-neutral design objectives. This type of product emphasizes two strategic priorities: enabling higher voltage and current handling within constrained packaging envelopes, and reducing reliance on gas-filled designs that carry environmental and regulatory complexity.
A parallel development is the launch of a high-current automotive relay built around magnetic arc blowout technology, engineered for industrial vehicle electrification and rated for substantial current and voltage ranges in a compact lightweight form factor. The design targets durability through defined operational lifecycles with integrated resistor and diode configurations, reflecting an emphasis on ruggedized performance for demanding vehicle platforms. Together, these examples underscore a broader trend: relay development is becoming more application-specific, with performance claims increasingly tied to real-world operating conditions, lifecycle expectations, and integration constraints rather than generic specification benchmarks.
Policy, Regulation, and Sustainability Alignment
Regulatory and sustainability expectations are shaping relay design choices in ways that extend beyond compliance. The move toward gasless relay architectures is not only a technical response to high-voltage switching needs but also a reflection of increasing attention to material use, emissions, and lifecycle considerations within component manufacturing. As vehicle manufacturers face broader decarbonization commitments and supply chain transparency requirements, relay suppliers that can offer designs reducing hazardous gas dependence or improving material efficiency gain a positional advantage in qualification processes and long-term sourcing discussions.
At the same time, regulatory pressure does not operate uniformly across regions or vehicle categories. Emissions standards, electrification incentives, and safety requirements influence the pace at which new relay specifications are adopted, creating a staggered demand environment. Suppliers that align product development with multiple regulatory trajectories, rather than optimizing for a single jurisdiction or platform, are better equipped to maintain relevance as qualification cycles lengthen and customer expectations broaden.
Demand-Side Shifts in Vehicle Electrification and Electrical Load Growth
Vehicle electrical architecture is becoming more decentralized and load-intensive, expanding the functional role of relays beyond traditional switching tasks. As platforms incorporate more electronic control units, higher-power comfort systems, advanced safety functions, and electrified powertrain components, the number and variety of switching points increase. This load growth supports continued demand for relays across multiple application areas, but it also raises performance expectations related to reliability, thermal management, and miniaturization.
In addition, the growing presence of electric and hybrid platforms is reshaping application priorities. High-voltage battery management, charging interfaces, and power distribution networks are creating new relay deployment contexts that differ materially from conventional low-voltage automotive use. These contexts require components that can handle higher stresses, support bidirectional power flow where relevant, and maintain consistent performance over extended service intervals. The demand shift is therefore not merely about volume growth; it is about a redefinition of the operating envelope in which relays must function.
Supply Chain Realignment and Cost Structure Pressures
Material and component pricing dynamics are reshaping the economics of relay production. Announcements of significant price increases for contactors, relay-related accessories, and printed circuit board materials indicate that supply chain costs are rising at a pace that cannot be ignored in product pricing strategies. These pressures affect both manufacturers and downstream customers, forcing a re-evaluation of specification thresholds, alternative material eligibility, and long-term contracting approaches.
For relay suppliers, the implication is clear: resilience increasingly depends on sourcing flexibility, design efficiency, and the ability to justify value beyond unit price. Suppliers that can integrate material optimization into product design, maintain multiple sourcing pathways, and communicate total cost of ownership benefits are more likely to preserve margins without sacrificing competitiveness. Conversely, those positioned as interchangeable commodity providers face greater vulnerability when input costs escalate and differentiation remains limited.
Competitive Landscape and Leading Strategies
The competitive field in the automotive relay market is broad and geographically diverse, featuring large multinational component suppliers, established electrical equipment manufacturers, and regional specialists with strong positions in specific voltage classes or application segments. This breadth matters because the market is not consolidating rapidly enough to eliminate differentiation opportunities, yet scale, engineering depth, and supply chain reach are becoming more valuable as product requirements intensify.
Leading participants tend to differentiate along several strategic axes. One is application-specific engineering, where suppliers build relay families optimized for high-voltage EV systems, industrial vehicle electrification, or compact PCB integration rather than offering generalized switching components. Another is integration and qualification support, which reduces customer adoption friction and strengthens long-term platform relationships. A third is material and manufacturing resilience, enabling suppliers to absorb cost volatility and sustain delivery reliability during periods of input-price instability. These dimensions are increasingly intertwined, as performance claims, sustainability attributes, and supply reliability all influence sourcing decisions.
Strategic Positioning Among Major Players
Global electronics and connectivity-focused suppliers often emphasize miniaturization, high-reliability contact systems, and broad automotive platform coverage. Their value proposition typically extends beyond the relay itself to include system-level integration support and a wide portfolio that can address multiple vehicle electrical functions. In the relay context, this approach helps capture demand across both conventional and electrified architectures, though it also requires sustained investment in product updates as voltage and current expectations rise.
Japanese manufacturers bring strong engineering discipline and a track record in component reliability, often targeting support for electrification, charging infrastructure, and precision switching applications. Their recent high-voltage relay introductions reflect a focus on compact designs, bidirectional capability, and environmental considerations such as gasless construction. This positions them as credible partners for customers seeking to align performance requirements with sustainability and packaging constraints.
European industrial and electrification-oriented players contribute depth in higher-power switching, robust contactor and relay ecosystems, and application support for demanding vehicle and industrial contexts. Their approach frequently combines electrical performance with broad accessory and system compatibility, which can be advantageous for customers prioritizing integration simplicity and lifecycle durability. At the same time, pricing sensitivity and material cost exposure remain important management considerations, particularly when input cost increases affect entire product families.
Chinese manufacturers have expanded their presence by combining volume production capability with growing engineering specialization across relay types and voltage ranges. Their strategic relevance lies in serving both domestic vehicle production growth and export-oriented supply chains, often with competitive cost structures and rapid capacity scaling. As application requirements become more demanding, however, sustained differentiation will depend on reliability validation, high-voltage capability, and the ability to meet international qualification expectations.
Market Evolution: Consolidation, Fragmentation, and New Entry Dynamics
The current market structure suggests that consolidation is occurring gradually rather than abruptly. The moderate concentration levels indicate that incumbents hold meaningful but not dominant shares, leaving room for specialized suppliers to compete on performance, region, or application fit. Over the next several years, differentiation is likely to sharpen as high-voltage and EV-related relay demand grows, rewarding suppliers that can reliably meet elevated electrical and environmental specifications.
PW Consulting Automotive & Machinery Research Center
At the same time, the market is not immune to fragmentation pressure. Regional manufacturing expansion, localized sourcing preferences, and platform-specific component requirements can sustain a diverse supplier base, especially where customers prioritize supply security or cost competitiveness. New entrants and niche specialists may find opportunities in targeted segments such as high-voltage DC switching, ruggedized industrial vehicle relays, or compact PCB-mounted solutions, particularly if they can demonstrate clear engineering advantages or sustainable design attributes. The strategic question for established players is whether to defend broadly across relay categories or concentrate resources on the highest-growth, highest-specification segments where performance and qualification barriers are rising.
Future Trends and Commercial Opportunities
High-Voltage and Bidirectional Switching Will Become a Core Differentiation Battleground
As vehicle electrical architectures continue to accommodate higher voltages and more complex power flow paths, relays designed for high-voltage DC applications and bidirectional switching are likely to capture disproportionate attention. This trend creates commercial opportunity for suppliers that can combine compact form factors, durable arc management, and gasless or environmentally optimized designs with validated performance claims. The opportunity is not limited to EV battery systems; it extends to charging interfaces, power distribution modules, and electrified commercial vehicle platforms where switching reliability and packaging efficiency are critical. Suppliers that establish early credibility in these specifications can strengthen platform qualifications and lock in long-term demand cycles.
Material Cost Volatility Will Redefine Value Propositions and Sourcing Strategies
The recent wave of input cost increases suggests that component pricing will remain a strategic concern rather than a temporary disruption. Over the next few years, the market is likely to see more active discussion of alternative materials, design-for-cost engineering, and long-term supply agreements that share or mitigate volatility. For relay manufacturers, this trend creates an opportunity to move up the value chain by offering solutions that reduce total system cost, simplify integration, or improve durability enough to justify premium positioning. For buyers, the opportunity lies in re-evaluating specification thresholds and supplier portfolios to balance performance requirements with cost resilience. Companies that treat material cost pressure as a design and sourcing challenge, rather than merely a procurement issue, will be better positioned to sustain margins and supply continuity.
Time Delay Relays Market
Application Diversification Will Drive Segment-Specific Relay Strategies
Relay demand is increasingly shaped by the functional needs of specific vehicle systems rather than by uniform fleet-wide replacement cycles. Powertrain, body and chassis, safety, comfort, and battery-related applications each impose distinct electrical, thermal, and lifecycle requirements. This diversification favors suppliers that can develop segment-specific relay families and support customers with application engineering rather than selling largely interchangeable products. It also creates opportunities for targeted growth in areas where electrical loads are expanding most rapidly and where reliability expectations are tightening. The commercial implication is that broad portfolio breadth alone will be less valuable than demonstrable fit to high-priority applications and the ability to validate performance under realistic operating conditions.
Worldwide Relay Output Module Market
Risks and Uncertainties to Monitor
Several uncertainties could alter the trajectory of these trends. If electrification adoption slows in certain regions or segments, high-voltage relay demand growth may not materialize as quickly as anticipated, leaving suppliers with elevated investment exposure in specialized product lines. If material cost pressures intensify further, margin compression could force price increases that test customer acceptance and accelerate the search for alternatives. If qualification cycles lengthen or sustainability requirements become more stringent, smaller or less-integrated suppliers may face disproportionate barriers to entry and retention. Finally, if alternative switching technologies gain traction in specific applications, traditional relay demand could face localized substitution risk, particularly where miniaturization, solid-state performance, or system-integration priorities dominate.
Strategic Recommendations for Decision-Makers
For Manufacturers and Component Suppliers
Focus product development on the intersection of high-voltage capability, compact packaging, and environmental optimization. Relay families that can demonstrate reliable performance under elevated voltage and current conditions, while reducing gas dependence or material intensity, are more likely to align with future platform requirements and qualification expectations. Equally important is supply chain resilience: diversify material sourcing, validate alternative input options where feasible, and build pricing strategies that can absorb volatility without eroding customer relationships. Where possible, invest in application engineering support that helps customers integrate relays into broader electrical architectures, since this deepens differentiation beyond unit specification comparisons.
For Investors and Strategic Capital Allocators
Evaluate relay-focused opportunities through the lens of specification upgrading and application alignment rather than volume growth alone. Companies with credible high-voltage DC relay capabilities, ruggedized industrial vehicle solutions, or differentiated sustainability attributes are better positioned to capture value as platform requirements intensify. Pay close attention to cost-structure resilience, sourcing flexibility, and the ability to sustain delivery reliability during periods of input-price instability. In addition, assess whether a target company’s portfolio is balanced across mature low-voltage demand and higher-growth electrification applications, since overconcentration in either direction can create vulnerability if adoption patterns shift.
For Procurement Teams and Vehicle Platform Buyers
Treat relay sourcing as a long-term performance and resilience decision, not a short-term price comparison. Specify requirements around voltage class, current handling, lifecycle durability, and environmental attributes where relevant, and validate supplier claims against realistic operating conditions. Diversify the supplier base where possible to reduce exposure to single-source cost shocks, while maintaining enough concentration to secure engineering support and qualification continuity. As input material costs remain volatile, consider multi-year agreements, alternative specification pathways, and total-cost frameworks that account for integration efficiency and service durability rather than initial unit price alone.
The automotive relay market is not defined by sudden disruption, but by a steady accumulation of technical, regulatory, and supply chain pressures that are reshaping how value is created and captured. Suppliers and buyers that anticipate these shifts, align product and sourcing strategies with emerging electrical architecture requirements, and build resilience into cost and qualification processes will be better positioned to convert market growth into durable commercial advantage. For organizations seeking a deeper breakdown of segment-level dynamics, regional demand patterns, and company-specific positioning across relay types and applications, a detailed research report can provide the granularity needed to translate these strategic themes into actionable planning.
For detailed analysis of this topic, please visit the official page: Automotive Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


