



Cleaning Robots Market: Why the 20.6% CAGR Isn’t the Full Growth Story

Cleaning Robots Market: Strategic Trends and Commercial Opportunities in an AI-Driven Automation Era
The global cleaning robots market has transitioned from a niche convenience category into a foundational component of the broader automation and facility management landscape. Valued at approximately 5.98 billion USD in 2020 and scaling to 14.8 billion USD by 2025, the sector has demonstrated compounding momentum that reflects deeper structural shifts in how spaces are maintained, managed, and optimized. Forward projections through 2032 point to sustained expansion, with the market trajectory aligning to a 20.6 percent CAGR across the forecast horizon. This growth is not merely a function of hardware adoption; it is being reshaped by software-defined navigation, operational labor economics, and evolving regulatory frameworks that collectively redefine what cleaning automation can deliver and where value is captured.
At the same time, the market stands at a strategic inflection point. Early adoption cycles were driven by consumer curiosity and premium residential upgrades. Today, the commercial and industrial segments are accelerating deployment, but with higher expectations for uptime, safety validation, integration with facility management systems, and measurable return on investment. The companies that navigate this shift successfully will be those that can pair compelling hardware with ecosystem-ready software, proven compliance postures, and service models that reduce total cost of ownership rather than simply lowering sticker prices.
Market Landscape: Growth Trajectory and Strategic Inflection Points
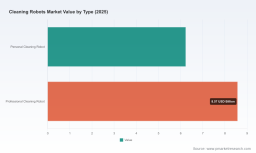
The headline scale of the market masks a more nuanced reality beneath the surface. Growth has been broad-based across product types and end-use contexts, yet the composition of value is shifting as capabilities converge and buyer expectations mature. Floor cleaning robots represent the largest product concentration, underscoring the enduring importance of routine surface maintenance in both homes and commercial premises. At the same time, specialized segments such as pool, lawn, and window cleaning robots are carving out defensible niches by solving specific operational pain points that generalist platforms cannot address efficiently.
One of the defining characteristics of the current market is moderate concentration. The top three players account for roughly 32 percent of total revenue, while the top five capture approximately 37 percent. This dispersion signals a market that is large enough to support multiple viable strategies, but not so fragmented that scale advantages are irrelevant. It also means that positioning, distribution strength, and vertical integration decisions can materially alter competitive outcomes.
Key Challenges and Turning Points
The sector is not simply riding a technological wave; it is contending with several structural challenges that will separate durable players from transient ones.
- From feature parity to reliability economics. Early differentiation was heavily reliant on incremental features, yet buyers now reward consistent performance, simpler maintenance, and fewer service interruptions. As competition intensifies, the cost of warranty claims, spare parts logistics, and field support is becoming a decisive margin lever.
- Navigation and obstacle handling at scale. Real-world environments are cluttered, dynamic, and unpredictable. The market is moving past controlled demonstrations toward deployment in spaces with mixed flooring, moving obstacles, pets, cables, and high-traffic transitions. Robots that can maintain cleaning quality without frequent intervention will increasingly define category leadership.
- Data, privacy, and operational compliance. Cloud-connected robots generate continuous streams of environmental and usage data. This creates value for remote diagnostics and fleet optimization, but it also introduces governance obligations. As privacy expectations rise and safety standards evolve for mobile platforms, compliance is shifting from a back-office concern to a commercial prerequisite.
These challenges are not purely risks; they are also filters. They reward manufacturers that can operationalize reliability, integrate safety-by-design thinking, and build transparent data practices into product architecture.
Core Drivers Reshaping Demand and Competitive Advantage
The market’s momentum is being shaped by four interlocking forces. Understanding how they interact is essential for positioning products, allocating capital, and deciding where to compete.
Technology Innovation and the Software-Defined Cleaning Robot
The most consequential breakthroughs are less about mechanical cleaning and more about perception, planning, and adaptation. High-precision navigation, dynamic obstacle avoidance, and adaptive cleaning modes are transforming robots from pre-programmed floor machines into responsive environment-aware systems. In residential settings, this translates into better results around furniture, pet areas, and transitional spaces. In commercial environments, it enables repeatable cleanliness with reduced supervision.
Artificial intelligence is also expanding the functional envelope of cleaning robots. Stain detection, surface-type recognition, and task-specific mode switching allow a single platform to handle broader scope without sacrificing cleaning quality. This matters because it changes the value proposition from “automation for convenience” to “automation for consistency and coverage,” which is far more defensible in procurement decisions.
Policy and Regulatory Environment as a Competitive Variable
Regulatory and standards activity is increasingly shaping product design and go-to-market timelines. Recent updates to safety requirements for industrial mobile robots, alongside active specifications for commercial cleaning equipment, are reinforcing the importance of functional safety, risk assessment, and performance validation. At the same time, working-stage guidance on dynamically stable mobile platforms is pushing manufacturers to think more carefully about balance performance and safe operation zones.
Beyond hardware safety, data governance has become an integral part of market access. GDPR and CCPA compliance are now baseline expectations for cloud-connected deployments, and independent security certifications are increasingly used as trust signals in commercial procurement. These developments do not simply constrain the market; they raise the bar for entry and reward organizations that build compliance into their engineering and operational processes early.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the residential side, cleaning robots are increasingly evaluated as part of a broader smart-home or household management experience rather than as isolated appliances. Buyers are looking for seamless setup, low-friction maintenance, and cleaning outcomes that perform reliably across varied household conditions. This has raised the importance of user experience, dock intelligence, and maintenance automation, since these factors directly affect long-term satisfaction and retention.
In commercial and industrial contexts, the driver is different but equally powerful: the search for predictable service quality under constrained labor availability. Facility operators are not simply looking to replace labor; they are trying to stabilize outcomes, extend cleaning coverage across shifts, and reduce variability in hygiene standards. This is why commercial-grade platforms that can operate in demanding environments with minimal supervision are gaining traction, and why deployments are increasingly judged by uptime and service-level consistency.
Supply Chain and Cost Structure Evolution
Hardware economics are being reshaped by component availability, integration complexity, and the cost of differentiated software stacks. Commodities such as basic sensors and standard drive components have seen gradual normalization, but high-value differentiation is migrating toward navigation subsystems, AI processing, dock intelligence, and service ecosystems. As a result, manufacturers face a strategic choice: compete on volume and cost efficiency in more standardized segments, or invest in higher-margin platforms that combine superior perception, cleaner software integration, and stronger after-sales value.
This dynamic is also reshaping partnerships. Rather than building every capability internally, some companies are pursuing co-development arrangements and ecosystem alliances to accelerate time-to-market and broaden compatibility. Such moves can reduce development risk and improve product completeness, but they also require careful management of brand positioning, data handling, and long-term dependency.
Competitive Landscape: Positioning, Differentiation, and Evolution
The competitive field reflects the market’s breadth. Players range from consumer-focused leaders with strong brand equity and ecosystem reach to specialist manufacturers concentrated on professional and commercial cleaning, and to diversified electronics companies leveraging robotics as an extension of broader home portfolios.
Strategic Positioning Among Leading Companies
Several patterns are visible among the most influential participants.
Worldwide Toilet Cleaning Robot Market
- Residential AI leadership. Organizations such as iRobot have built strong recognition around home cleaning platforms that combine advanced navigation, self-emptying infrastructure, and multi-function cleaning modes. Their strategic advantage lies in brand trust, recurring attachment through docks and consumables, and a product architecture designed around residential usability.
- Navigation and mop-integration differentiation. Companies like Ecovacs Robotics and Roborock have emphasized high-precision navigation, self-washing mop systems, and AI-based obstacle handling. Their push has centered on improving cleaning completeness while reducing manual intervention, which is increasingly important in premium residential segments and larger indoor spaces.
- Commercial-grade specialization. Manufacturers such as Kärcher and SoftBank Robotics are oriented toward professional and facility-scale applications, where robustness, multi-surface capability, and operational endurance matter more than consumer-friendly packaging. Their value proposition is rooted in integration with facility workflows and the ability to deploy reliably in hotels, hospitals, and large public or industrial premises.
- Broad portfolio extension from consumer electronics. LG and Samsung have approached cleaning robots as part of wider appliance and smart-home ecosystems, using suction performance, self-cleaning infrastructure, and connectivity integration as differentiators. This approach can create cross-selling advantages and platform synergies, especially where consumers already trust the brand in adjacent categories.
- Niche autonomy in specialized environments. In pool cleaning, companies such as Maytronics have maintained relevance through purpose-built autonomy for a distinct use case, showing that specialized navigation and durability in water environments can sustain a strong position even as broader segments consolidate. SharkNinja has similarly leaned into brand-led AI vacuums and mops with features such as self-emptying systems and stain-detection technologies, illustrating how strong consumer branding can support robotics entry and expansion.
How the Landscape Is Evolving
The market is exhibiting a mix of consolidation pressure and deliberate differentiation. Some competitors are expanding into adjacent cleaning contexts, while others are narrowing focus to specific environments where they can command stronger pricing and service relationships. Alliances and co-development initiatives are becoming more common as companies seek to extend capabilities without stretching internal resources too thin. At the same time, new entrants are testing highly targeted solutions for overlooked tasks, particularly in commercial hygiene where labor constraints and cleanliness standards create persistent demand.
Recent developments highlight this direction. Strategic partnerships are being used to combine complementary expertise and accelerate next-generation solutions. Product launches are increasingly focused on autonomous restroom cleaning and expanded commercial fleets, reflecting a move toward higher-complexity environments that demand greater autonomy and task-specific engineering. Milestones such as major commercial scrubber sales thresholds also indicate that demand for professional automation is not theoretical; it is scaling in practice.
In this environment, competitive advantage is increasingly determined by the ability to deliver complete solutions rather than isolated hardware. That includes navigation reliability, maintenance design, safety and compliance documentation, integration with operational systems, and service economics. Companies that can prove they reduce operational friction for the buyer will have a stronger position than those competing primarily on feature lists or price alone.
Forward-Looking Trends and Where Value Will Concentrate
Looking ahead across the next three to five years, the market is likely to be shaped by a small number of durable trends. These trends create both opportunity and risk, depending on how organizations position themselves.
Trend 1: Commercial and Facility-Scale Automation as a Growth Anchor
The commercial segment is poised to become an increasingly important growth engine. Labor availability, consistency requirements, and the operational cost of manual cleaning are pushing facility managers toward autonomous solutions that can supplement or partially replace repetitive maintenance tasks. This trend favors robust platforms, clear service-level commitments, and proven performance in demanding environments. The commercial opportunity is not limited to large venues; it extends to offices, retail spaces, healthcare facilities, and educational environments where standardized cleanliness and coverage matter.
Commercial deployment also raises the stakes for total cost of ownership. Buyers will increasingly compare the combined cost of acquisition, maintenance, consumables, downtime, and supervision rather than focusing solely on unit price. Manufacturers that can document operational savings and reduce intervention requirements will have a stronger commercial narrative.
Trend 2: Convergence of Cleaning and Environmental Intelligence
Cleaning robots are becoming more embedded in broader environmental sensing and facility management workflows. Navigation and perception technologies that support cleaning can also support monitoring, mapping, and task coordination. This opens the door to broader value creation: robots that not only clean but also contribute to space utilization insight, maintenance scheduling, or workflow coordination.
This convergence creates opportunities for differentiated platforms, but it also introduces integration challenges. Data handling, interoperability, and system reliability become more important as robots participate in larger operational ecosystems. Privacy and security expectations will continue to shape what is commercially acceptable, especially in environments where cameras, sensors, or continuous connectivity are involved.
Trend 3: Safety, Compliance, and Trust as Commercial Entry Conditions
Safety standards, performance specifications, and data governance requirements are becoming more visible in procurement and deployment decisions. This is likely to accelerate product maturation, but it may also slow entry for players that lack engineering rigor or documentation discipline. Trust is becoming a competitive asset: operators want platforms that are not only effective, but also safe around people, dependable in varied environments, and transparent in how they handle operational data.
The implication is clear. Companies that treat safety and data governance as engineering and commercial priorities, rather than as legal afterthoughts, will find it easier to scale deployments and win enterprise confidence.
Logistics Robots Market
Risks and Uncertainties
Several uncertainties could shape the pace and shape of growth. Economic volatility may affect both consumer discretionary spending and enterprise capital allocation, influencing adoption timing across segments. Competition could compress margins in more standardized categories if differentiation fails to keep pace. Regulatory and standards developments may change product requirements faster than some organizations can adapt. Finally, the market may see segmentation intensify, where generalist platforms struggle to match the economics and performance of specialists in demanding niches.
Strategic Playbooks for Decision-Makers
The cleaning robots market rewards clarity of purpose. Whether the objective is manufacturing, investment, or procurement, the most useful question is not whether the market is growing, but where value is being created and how to capture it.
For Manufacturers and Product Leaders
- Decide where to win, not just what to build. The market supports both broad consumer platforms and specialized commercial solutions, but managing both without clear differentiation is difficult. Define the environments, tasks, and customer types where the company can credibly outperform, then align navigation, cleaning mechanism, maintenance design, and service model to that target.
- Prioritize reliability economics. Cleaning outcomes, uptime, and service simplicity increasingly determine long-term reputation and margin. Invest in perception robustness, obstacle handling, consumable and dock design, and field support processes that reduce repeat visits and warranty exposure.
- Make compliance and data trust part of the product story. Functional safety, performance validation, and responsible data handling are no longer optional polish. They are part of how commercial buyers evaluate risk and how consumers evaluate long-term trust.
For Investors
Capital allocation should be guided by durability of advantage rather than headline growth alone. The most attractive opportunities are likely to be found where there is a combination of clear demand drivers, defensible technology or niche focus, and economic models that scale through service, software, or specialized hardware rather than relying purely on unit volume. Assess whether a company can sustain differentiation as navigation and cleaning features become more common, and whether its go-to-market model can support commercial deployments where procurement cycles and reliability expectations are stricter. Also pay attention to partnerships and ecosystem moves, since they can accelerate capability but also change dependency structures and competitive positioning.
For Procurement and Operations Leaders
- Evaluate the full operational picture. Compare solutions on cleaning consistency, supervision requirements, maintenance burden, and integration with existing workflows. A lower upfront cost can be outweighed by higher intervention, downtime, or consumable complexity.
- Request evidence relevant to your environment. Demonstrations in idealized settings are useful, but procurement decisions should be informed by performance data, safety documentation, and deployment support that match the specific space type, traffic patterns, and cleanliness standards involved.
- Plan for service and lifecycle management. Autonomous cleaning is not a one-time purchase decision. It is an operational relationship. Assurance around support response, spare availability, software updates, and data handling practices can be as important as the hardware itself.
The Practical Payoff of Deeper Market Intelligence
The dynamics in this market are moving quickly enough that broad directional understanding is necessary but not sufficient. Segment-specific economics, company-level positioning, regional deployment patterns, and emerging product strategies can materially change the attractiveness of a particular opportunity or the risk profile of a given vendor choice. Decision-makers who need to compare options, size entry points, or evaluate competitive threats will benefit from more granular intelligence that connects market structure to actionable choices.
PW Consulting
For organizations looking to move from general awareness to confident execution, a detailed study of segment trends, company strategies, and commercial implications can provide the granularity needed to prioritize investments, shape product roadmaps, and negotiate procurement decisions with greater clarity. Access to more detailed research allows leaders to test assumptions, compare scenarios, and identify where to commit resources before the market shifts further.
For detailed analysis of this topic, please visit the official page: Cleaning Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


