



Medical Equipment Maintenance Market: Why 9.9% CAGR and Preventive Services Redefine Growth to $110.08B

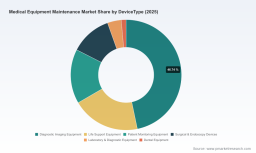
The Medical Equipment Maintenance Market: Strategic Trends and Commercial Opportunities (2025–2032)
1. Market Snapshot and Core Challenges
The global medical equipment maintenance market has entered a period of pronounced expansion, with total revenue reaching approximately 57.0 billion in 2025 and projected to climb to 110.08 billion by 2032. This trajectory reflects a compound annual growth rate of 9.9 percent across the forecast horizon, signaling a structural shift rather than a short-term cyclical upturn. Over the past five years, the market has steadily moved from fragmented, reactive repair models toward integrated lifecycle management programs, driven by rising capital intensity in healthcare delivery and an accelerating push toward operational resilience.
Despite this momentum, the sector faces meaningful headwinds that will shape competitive positioning over the next several years. First, the boundary between servicing and remanufacturing continues to generate regulatory and commercial friction. Healthcare providers, OEMs, and third-party operators must navigate evolving guidance on what constitutes acceptable post-market maintenance versus material modification, a distinction that carries direct implications for liability, scope of work, and pricing models. Second, labor constraints and specialized skill shortages are compressing service capacity. The industry relies heavily on trained clinical engineers and field technicians, and the supply of qualified personnel has not kept pace with the volume of installed equipment across aging hospital fleets. Third, installed-base complexity is increasing faster than many organizations’ service capabilities. Devices are becoming more software-defined, interconnected, and modular, which raises the bar for diagnostic precision, parts logistics, and remote intervention.
These challenges are not merely operational footnotes; they define where value will be captured. Organizations that treat maintenance as a predictable, data-enabled discipline will be better positioned to protect uptime, manage total cost of ownership, and align service delivery with clinical and financial performance targets.
2. Key Drivers Shaping Market Direction
Technology Innovation and Intelligent Service Models
Predictive and condition-based maintenance is rapidly moving from pilot programs to mainstream adoption. AI-enabled monitoring, remote diagnostics, and connected device telemetry are allowing service teams to anticipate failures before they affect clinical workflows. Recent activity illustrates how quickly this capability is becoming table stakes. In 2025, GE HealthCare expanded its enterprise software and imaging service footprint through the acquisition of Intelerad Medical Systems Corporation for 2.3 billion, while also entering a seven-year Care Alliance with Sutter Health to deploy AI-powered imaging systems across more than 300 facilities. Separately, a collaboration with IBM Watson Health was announced to launch AI-powered predictive maintenance services for medical imaging equipment. Philips also moved to strengthen its informatics-driven service positioning after securing FDA approval for IntelliSpace Enterprise Edition 6.0, which includes predictive maintenance capabilities for imaging systems.
For commercial leaders, the implication is clear: maintenance is increasingly sold and evaluated as an outcomes-based capability rather than a labor-hours contract. Solutions that can reduce unplanned downtime, extend useful life, and integrate with clinical and operational data are gaining preference, especially in high-acuity environments where device availability directly affects throughput and care continuity.
Regulatory and Standards Evolution
The regulatory environment is tightening in ways that favor disciplined, well-documented service programs. The FDA Quality Management System Regulation became effective in early 2026, incorporating ISO 13485:2016 by reference and applying to manufacturers as well as facilities engaged in remanufacturing or servicing. This alignment raises the expectations for quality systems, traceability, and controlled processes across the service ecosystem. At the same time, the Joint Commission streamlined its accreditation standards effective January 1, 2026, consolidating previous requirements for inspecting, testing, and maintaining medical equipment into a single element of performance that hospitals must ensure essential equipment remains in safe operating condition.
These developments create a dual effect. On one hand, they increase compliance burden and can raise the cost of service delivery for organizations that depend on informal or poorly documented practices. On the other hand, they strengthen the commercial case for providers and OEMs that can demonstrate structured quality management, standardized procedures, and auditable maintenance records. In practical terms, regulatory momentum is rewarding service models that are transparent, repeatable, and integrated with device lifecycle governance.
Demand-Side Shifts in Healthcare Operations
Healthcare providers are under sustained pressure to optimize capital deployment, reduce total cost of ownership, and maintain service levels with constrained operational budgets. These pressures are pushing procurement teams to evaluate service contracts not as ancillary expenses but as strategic levers for equipment reliability and cost predictability. Hospitals and health systems are increasingly seeking bundled programs that combine preventive maintenance, corrective support, and operational oversight, rather than managing multiple fragmented vendor relationships.
This demand-side evolution is also visible in regional capacity expansion. Sodexo India opened a 6,700 square-foot Healthcare Technology Management facility in Kolkata, equipped with six specialized labs designed to support up to 500,000 devices. The move reflects broader interest in building localized service capacity that can respond faster, reduce logistics latency, and improve coverage density. For the market overall, it signals that service delivery is becoming more geographically distributed and more sensitive to response-time expectations.
Cost Structure and Supply Chain Dynamics
Parts availability, labor economics, and reverse logistics continue to shape service margins and contract design. As devices become more software-centric and modular, the economics of repair are shifting. In some categories, rapid diagnostics and component-level replacement can improve asset utilization and reduce total cost, while in others, specialized parts sourcing and calibration requirements tighten margins and extend resolution times. At the same time, remanufacturing and refurbishment pathways are gaining attention as organizations look for ways to extend asset life without compromising performance or compliance.
A recent FDA guidance finalized in 2024 clarified the distinction between remanufacturing and servicing of reusable medical devices, emphasizing that proper servicing is critical to continued performance and overall product lifecycle management. More recently, FDA finalized guidance on Predetermined Change Control Plans for AI/ML-enabled devices, enabling manufacturers to include post-market algorithm update plans in initial submissions. Together, these signals indicate that device lifecycles are being managed more actively, and service providers will need clearer frameworks for supporting evolving software and hardware configurations over time.
3. Competitive Landscape and Leading Strategies
The medical equipment maintenance market remains concentrated, with a small group of large players commanding a substantial share of high-value service contracts. GE HealthCare, Siemens Healthineers, Philips, and Medtronic each bring strong brand recognition, deep installed-base relationships, and the ability to bundle maintenance with device sales, informatics platforms, and clinical workflow solutions. This integration is a defining competitive advantage, because it links service delivery directly to equipment performance data, service history, and lifecycle planning.
Worldwide Heavy Equipment Maintenance Service Market
GE HealthCare has emphasized AI-driven predictive maintenance, imaging and cardiology service, and the expansion of enterprise software portfolios. Siemens Healthineers has focused on diagnostic imaging, laboratory, and therapeutic equipment maintenance with remote monitoring and service contracts tailored to healthcare facilities. Philips has leaned into informatics platforms with predictive capabilities, positioning maintenance as part of a broader clinical technology ecosystem. Medtronic’s service model is particularly relevant in implanted devices, cardiac rhythm management, and minimally invasive surgical equipment, where ongoing service and maintenance contracts intersect with clinical risk and long-term patient outcomes.
Outside the largest OEMs, a second tier of specialists is carving out differentiated positions. B. Braun has concentrated on infusion, dialysis, and related equipment maintenance across hospital settings. STERIS has built a strong identity around sterilization, infection prevention, and equipment maintenance and repair services. Agiliti and TriMedx have taken a more holistic approach to clinical engineering, equipment maintenance, and technology management, often targeting health systems that want to consolidate service oversight or improve asset utilization across diverse device fleets.
PW Consulting
Several strategic themes are shaping how these players compete. First, integration is becoming more important than isolated repair capability. Providers increasingly prefer partners that can combine maintenance with remote monitoring, data analytics, spare-parts logistics, and technology lifecycle planning. Second, AI-enabled service differentiation is accelerating. Predictive maintenance, automated fault diagnosis, and algorithm-driven scheduling are transitioning from innovative features to differentiators that affect contract selection and retention. Third, partnerships and acquisitions are being used to extend reach. The 2025 acquisition by GE HealthCare and collaborations with major health systems and technology partners highlight a pattern of strengthening software, informatics, and enterprise service capabilities rather than competing solely on field labor.
At the same time, the landscape is not static. Regional capacity investments, such as the Healthcare Technology Management facility in Kolkata, point to growing appetite for localized service delivery and specialized lab infrastructure. This suggests an ongoing tension between centralized, OEM-led service models and regional or third-party operators that can offer flexibility, coverage density, or niche device expertise. For buyers and investors, the relevant question is whether a provider’s model can scale while maintaining quality, compliance, and responsiveness across heterogeneous equipment portfolios.
4. Forward Outlook: Three Trends to Watch Through 2032
From Preventive Schedules to Predictive, Data-Connected Service
Preventive maintenance will remain foundational, but its role is likely to evolve from calendar-based tasks toward continuously informed service planning. Devices that generate operational telemetry, error logs, and performance trends will enable more precise intervention windows, which can reduce unnecessary visits while improving readiness. The commercial opportunity lies in contracts and service architectures that reward reliability, faster diagnosis, and deferred capital replacement. Organizations that can operationalize predictive insights across large installed bases will have a clearer path to differentiated pricing, stronger retention, and better asset utilization outcomes.
One risk is uneven data quality and interoperability. Predictive models are only as effective as the underlying device data, integration maturity, and process discipline supporting them. If telemetry coverage is incomplete or service workflows cannot act quickly on alerts, the theoretical gains from AI-driven maintenance may fail to materialize in practice.
Regulation-Driven Professionalization of Service Delivery
As quality management expectations rise and accreditation standards consolidate around safe operating condition requirements, service delivery is likely to become more formalized. Documentation, training, traceability, and controlled procedures will carry greater commercial weight, especially for organizations involved in remanufacturing or servicing activities that intersect with regulatory oversight. The trend favors providers that can standardize processes across sites and demonstrate compliance without imposing excessive administrative burden on clinical staff.
The uncertainty here is speed and consistency of adoption. Regulatory clarity is improving, but implementation varies by facility type, region, and device category. Market participants that assume uniform compliance behavior may misjudge the timeline for contract wins, service standardization, or partnership requirements.
Lifecycle Extension, Modularity, and Strategic Refurbishment
With device complexity rising and capital budgets under pressure, lifecycle management is gaining strategic importance. Maintenance programs are increasingly evaluated not only on uptime but also on whether they enable longer useful life, component-level optimization, and responsible refurbishment where appropriate. This creates opportunities for service providers that can combine repair expertise with parts logistics, calibration, software updates, and disposal or redeployment planning. It also raises the importance of clear boundaries between servicing and remanufacturing, since misclassification can create regulatory, quality, and commercial risk.
A key risk is that lifecycle extension strategies can be undermined by unavailable parts, obsolete software support, or changing clinical requirements. Without strong reverse logistics and lifecycle governance, maintenance programs may extend service duration without improving total cost outcomes.
5. Strategic Actions for Decision-Makers
For manufacturers and OEMs, the priority is to embed service intelligence into the product and contract architecture early. Predictive capabilities, remote diagnostics, and integrated informatics should be treated as core elements of the service offering rather than optional add-ons. Aligning service design with regulatory expectations for quality management and device lifecycle management can reduce downstream friction and strengthen contract positioning. Where possible, manufacturers should also consider how partnerships, acquisitions, and software expansion can broaden enterprise value beyond individual device repairs.
For investors, the market’s expansion is attractive, but differentiation will depend on execution quality. Due diligence should focus on whether a service provider has durable mechanisms for predictive maintenance, compliance readiness, geographic coverage, and parts logistics. Concentration in the market suggests that scale and brand matter, yet there is also room for specialists that address underserved device categories, regional demand, or integrated technology management. The most resilient business models will likely combine recurring service revenue with demonstrated improvements in uptime, total cost of ownership, and operational simplicity for customers.
Worldwide Pharmaceutical Equipment Maintenance Services Market
For healthcare procurement and clinical engineering teams, the decision framework should shift from lowest headline price to total value under real operating conditions. Contracts that provide transparent service levels, remote monitoring, rapid response, and well-documented quality processes can reduce hidden costs associated with downtime, repeated visits, and compliance gaps. Procurement teams should also evaluate whether the service provider can support mixed device portfolios, evolving software configurations, and future lifecycle needs rather than optimizing for a single equipment category in isolation.
Given the pace of regulatory change, technology adoption, and competitive consolidation, timely access to granular market intelligence is increasingly important for shaping contracts, portfolio strategy, and investment priorities. Readers seeking deeper segmentation data, regional expansion patterns, and customized recommendations aligned with specific device portfolios or service models may find value in PW Consulting’s comprehensive research report on the medical equipment maintenance market.
For detailed analysis of this topic, please visit the official page: Medical Equipment Maintenance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


