



IVC Filters Market to Reach $212M by 2032: Why 9.4% CAGR Signals a Strategic Shift

The Inferior Vena Cava Filter Market: Strategic Trends and Commercial Opportunities in a High-Growth Landscape
The Inferior Vena Cava (IVC) Filter Market has entered a phase of accelerated expansion, driven by a convergence of epidemiological shifts, technological maturity, and evolving clinical protocols. As of 2025, the global market valuation stands at approximately 113.0 million USD, reflecting a compound annual growth rate of 9.4 percent across the forecast horizon extending to 2032. Historical trajectories from 2020 through 2025 demonstrate consistent upward momentum, with revenues climbing from 72.0 million USD to the current baseline, signaling sustained adoption and procedural volume increases. Looking forward, the market is projected to surpass 212.0 million USD by the end of the forecast period in 2032. Such financial expansion underscores a structural shift in how venous thromboembolism and pulmonary embolism prevention are managed, particularly as minimally invasive vascular interventions continue to gain procedural preference over pharmacological monotherapy in high-risk cohorts. For executives and investors, this trajectory signals more than incremental revenue growth; it points toward a market undergoing redefinition through product innovation, regulatory scrutiny, and procurement evolution. Understanding the mechanics behind this expansion is essential for positioning portfolios, allocating capital, and shaping commercialization strategies in a space where clinical credibility and supply chain reliability are becoming decisive competitive moats.
Current Landscape and Core Challenges
Despite robust top-line growth, the industry is navigating a set of interconnected challenges that will shape competitive outcomes over the next several years. The first and most pressing is the intensifying regulatory and litigation environment surrounding retrievable filter safety and retrieval compliance. Decades of clinical use have produced a well-documented awareness of migration, fracture, and perforation risks, which has translated into heightened post-market surveillance expectations and a persistent volume of multidistrict litigation. As of mid-2026, more than 6,500 pending cases remain active against major manufacturers related to IVC filter complications, reinforcing the cost of quality, traceability, and post-market evidence generation. For companies operating in this space, risk management has moved from a compliance function to a strategic imperative that influences procurement decisions, hospital formulary inclusion, and insurance liability considerations.
The second challenge lies in balancing clinical adoption with appropriate retrieval practices. Regulatory bodies have repeatedly emphasized timely removal of retrievable filters once the acute risk of pulmonary embolism has subsided, yet real-world retrieval rates often lag behind clinical intent due to patient follow-up fragmentation, procedural scheduling constraints, and institutional workflow limitations. This gap between guideline expectations and bedside execution creates both a clinical liability and a commercial friction point: products that simplify retrieval, reduce procedural time, or offer convertible design features gain meaningful differentiation in an environment where retrieval compliance is increasingly measured and scrutinized.
PW Consulting Automotive & Machinery Research Center
The third challenge emerges from the supply chain and cost structure dynamics governing interventional vascular devices. While reimbursement frameworks provide baseline facility payment references, including facility Medicare payments for intravascular vena cava filter insertion, hospitals and health systems are under continuous margin pressure to optimize procedural efficiency and reduce total cost of care. Device complexity, introducer system reliability, and procedural duration directly influence operating room throughput and clinical satisfaction. Any resistance in device delivery, sheath navigation, or retrieval mechanics can translate into operational delays, resource reallocation, and downstream cost impacts. In this context, manufacturers must align engineering performance not only with clinical efficacy but also with the economic realities of high-volume procedural environments.
Blood Filter Market
Key Drivers of Market Change
Multiple interconnected forces are propelling the IVC filter market beyond its historical baseline. These drivers are reshaping product roadmaps, influencing procurement criteria, and clarifying where long-term value will accrue.
Technological Innovation and Design Breakthroughs
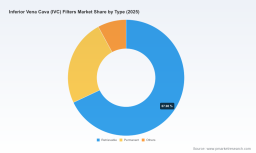
Product engineering continues to be a primary catalyst for market evolution. The dominance of retrievable filter architectures in current usage reflects a broader clinical preference for devices that can be deployed as temporary protective measures and removed once the risk window closes. At the same time, next-generation retrieval technologies are altering the risk-reward calculus for difficult removals. The regulatory classification of laser-powered IVC filter retrieval catheters into class II with special controls marks an important milestone, formalizing a category that was previously positioned for failure cases where conventional methods were insufficient. This classification is not merely an administrative event; it creates a regulated pathway for advanced retrieval tools, broadens the clinical toolkit for complex extractions, and opens commercial avenues for companies developing adjunctive systems that support safer, faster, and more controlled filter removal. For manufacturers, the opportunity lies in designing filter platforms that integrate smoothly with evolving retrieval accessories and in developing proprietary extraction or repositioning systems that reduce procedural friction and improve physician confidence.
Policy and Regulatory Environment
Regulatory communication and classification decisions have exerted a long-running influence on the market and continue to do so. Earlier safety communications encouraging timely retrieval of retrievable filters have reshaped expectations around device lifecycle management and institutional oversight. More recently, the formal classification of laser-based retrieval catheters reinforces the regulatory direction toward risk-based controls and evidence-supported special controls. Such actions signal that the market is moving toward more explicit post-market obligations, including device tracking, retrieval documentation, and real-world performance monitoring. This trajectory affects not only product design and labeling but also commercial operations, as manufacturers must demonstrate robust quality systems, adverse event responsiveness, and traceability across the device lifecycle. In parallel, reimbursement structures remain a structural enabler of procedural volume, but they also impose expectations for efficiency and predictable outcomes. The interplay between reimbursement clarity and regulatory stringency is shaping which product categories gain formulary preference and how hospitals balance clinical utility against liability and workflow considerations.
Demand-Side Shifts in Clinical Behavior
Clinician and institutional behavior is evolving in response to both clinical evidence and operational realities. The preference for retrievable filters underscores a strategy of temporary protection in patients who may not require permanent mechanical filtration, while also reflecting the need for adaptable solutions in patients with evolving anticoagulation status or uncertain duration of risk. At the same time, institutions are increasingly focused on procedural standardization and complication reduction. Devices that offer consistent deployment characteristics, predictable filtering performance, and retrieval-friendly configurations are gaining favor because they reduce procedural variability and support protocol-driven care. Another demand-side development is the growing attention to convertible and repositionable designs, which allow procedural adjustments during deployment and can ease the clinical burden associated with suboptimal initial placement. In hospital procurement, these attributes matter because they influence case time, physician training requirements, and post-procedure management load. As centers seek to streamline interventional workflows while maintaining patient safety standards, device simplicity, reliability, and retrieval compatibility are becoming central evaluation criteria.
Supply Chain and Cost Structure Considerations
Cost dynamics in the IVC filter market are increasingly influenced by total procedural economics rather than unit device price alone. Hospitals evaluate devices through the lens of operating room efficiency, ancillary consumable usage, complication-related costs, and retrieval logistics. A device that delivers reliable delivery system performance and minimizes introducer resistance, for example, supports smoother procedural flow and reduces the likelihood of delays or vein-related complications that can escalate care complexity. Conversely, product issues that introduce procedural resistance or increase the risk of vascular injury can have disproportionate cost consequences, undermining both clinical outcomes and institutional efficiency metrics. Supply chain resilience also matters as manufacturers must ensure consistent availability of both primary filters and retrieval accessories, particularly as advanced removal technologies become more embedded in standard practice. Companies that can integrate device and retrieval system offerings into a coherent procedural solution, while maintaining stable production and distribution capabilities, are better positioned to meet procurement expectations in cost-sensitive environments.
Competitive Landscape and Leading Strategies
The market structure is characterized by meaningful concentration among established players, yet competitive advantage is increasingly defined by product differentiation, procedural reliability, and lifecycle management rather than scale alone. Leading manufacturers have built portfolios around retrievable filter platforms, convertible designs, and retrieval-compatible systems, with individual companies emphasizing distinct clinical narratives and engineering strengths.
Strategic Positioning and Differentiation
Cook Medical remains a prominent reference point in the market, anchored by retrievable filter offerings such as the Celect Platinum and the Günther Tulip filter. Its commercial strength has been linked to broad procedural familiarity and a long track record in the space, though its market standing is simultaneously shaped by ongoing litigation associated with filter complications. For competitors, this environment underscores the strategic value of proactive retrieval compatibility, transparent post-market data, and design features that reduce long-term risk profiles. Becton, Dickinson and Company (BD) has emphasized its Denali filter platform, reflecting a strategy aligned with large-scale commercial infrastructure and integration within broader interventional portfolios. Argon Medical Devices, Inc. has focused on its Option Elite retrievable vena cava filter system, positioning itself around retrieval functionality and procedural versatility. Cordis Corporation, operating within Cardinal Health, has maintained presence through retrievable and permanent filter lines such as the OptEase and TrapEase platforms, emphasizing established product heritage in multiple filter categories. B. Braun Interventional Systems, Inc. offers convertible and lower-profile filter options through its VenaTech line, highlighting design flexibility and deployment adaptability. ALN Implants Chirurgicaux contributes a European-origin perspective with optional filter systems and associated extraction and repositioning capabilities, reinforcing a strategy centered on retrieval enablement and procedural control.
Central Venous Catheters Market
Across these players, differentiation is emerging around several axes: retrieval compatibility, delivery system performance, convertible or repositionable features, and the breadth of ancillary systems that support filter removal and repositioning. Companies that treat the filter as part of an end-to-end procedural workflow, rather than a standalone implant, are building more defensible positions in a market where retrieval compliance and procedural reliability are increasingly central to clinical and procurement evaluation.
Market Evolution and Consolidation Dynamics
The competitive landscape is likely to evolve through selective consolidation, portfolio rationalization, and targeted innovation rather than pure volume expansion. As regulatory expectations rise and retrieval-related technologies mature, smaller or narrowly focused players may face pressure to demonstrate differentiated clinical value, robust quality systems, and reliable supply. At the same time, established manufacturers may pursue complementary capabilities in retrieval, imaging support, or procedural accessories to strengthen integrated offerings. There is also room for new entrants that bring specialized retrieval technologies, advanced delivery mechanics, or novel materials that improve long-term compatibility and reduce complication risk. However, entry barriers remain meaningful because the market rewards regulatory experience, post-market surveillance infrastructure, and established clinician relationships. For incumbents, the strategic priority is to convert product familiarity into procedural value propositions that explicitly address retrieval, reliability, and total cost of procedural care. For challengers, the opportunity lies in solving specific pain points that broader portfolios have not fully addressed, particularly in difficult retrieval scenarios and delivery consistency.
Future Trends and Commercial Implications
Looking ahead over the next three to five years, several trends are likely to shape the direction of the market and define where commercial value will concentrate. These trends do not merely extend existing growth; they change the metrics by which success is measured.
Retrieval-Centric Product Architecture as a Baseline Expectation
As retrieval compliance becomes more closely monitored and retrieval technologies become more established, filter design will increasingly be judged through the lens of how easily and safely a device can be removed. Retrievable filters will continue to dominate usage, but the differentiating question will shift from whether a filter is retrievable to how predictable, efficient, and low-risk retrieval is in real-world settings. This will favor designs that support smoother sheath navigation, reduce mechanical resistance, and integrate with advanced retrieval tools when conventional removal is insufficient. For manufacturers, the commercial implication is clear: retrieval efficacy and procedural simplicity will become core value propositions rather than secondary features. For hospitals, this trend reinforces procurement criteria that prioritize devices capable of supporting standardized retrieval protocols and minimizing complication-related follow-up costs. The associated risk is that products with weaker delivery or retrieval performance may face growing clinical skepticism, formulary exclusion, or liability exposure if complications or procedural delays emerge.
Advanced Retrieval Technologies and Adjacent Market Expansion
The formalization of laser-based retrieval catheter classification points toward broader adoption of adjunctive removal technologies, particularly for cases where conventional techniques are challenged by endothelial incorporation or structural complexity. As these technologies become part of accepted clinical pathways, they create opportunities for companies offering complementary devices, training, procedural support, and bundled solutions. The commercial upside extends beyond the filter itself to the surrounding ecosystem of retrieval accessories, procedural optimization tools, and service models that support complex interventions. However, this trend introduces uncertainty around reimbursement allocation, clinical adoption variability, and the need for robust training and documentation. Companies that can demonstrate safety, efficiency, and procedural cost reduction in difficult retrieval scenarios are more likely to capture value, while those that enter without clear clinical differentiation or risk documentation may find adoption constrained by hospital procurement caution.
Evidence Generation, Post-Market Transparency, and Procurement Rigor
The combination of ongoing litigation, regulatory communication history, and class-based device controls is increasing the premium on evidence generation and post-market transparency. Institutions and procurement teams are likely to place greater weight on real-world performance data, retrieval documentation, adverse event responsiveness, and quality system credibility. This creates a strategic expectation for manufacturers to maintain comprehensive post-market programs, support clinical registries or real-world evidence initiatives, and communicate device lifecycle management clearly. For investors and executives, the trend implies that brand trust and data credibility will increasingly influence market share dynamics, especially in a concentrated market where a few players hold a large share of revenue. The risk side of this trend is that any reputational or compliance gap can have outsized effects in a market where clinical safety narratives are closely watched and where procedural liability concerns are already elevated.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to align product development with retrieval compatibility, delivery reliability, and procedural transparency. Investment in filter platforms should be evaluated not only by implantation performance but also by removal ease, integration with retrieval accessories, and the robustness of post-market surveillance. Companies should also examine opportunities to bundle filters with repositioning or extraction systems where such integration reduces procedural friction and supports compliance with timely retrieval expectations. In parallel, supply chain discipline and consistent availability of both primary devices and retrieval components should be treated as competitive differentiators in settings where procedural efficiency directly impacts hospital economics.
For investors, the market offers growth potential, but valuation and risk assessment must account for regulatory, litigation, and execution dynamics. The strongest opportunities are likely to emerge from companies with differentiated retrieval capabilities, credible post-market data programs, and clear strategies for navigating class-based device controls and reimbursement realities. Due diligence should consider not only revenue momentum but also device lifecycle management, complication-related risk exposure, and the capacity to sustain reimbursement alignment while expanding into adjacent retrieval technologies. Diversification across filter categories and retrieval-supporting portfolios can reduce dependence on any single product narrative, particularly in a market where clinical reputation and procedural reliability are tightly linked to commercial outcomes.
For procurement teams and health system leaders, device evaluation should increasingly incorporate retrieval workflow, procedural reliability, and total cost implications rather than unit pricing alone. Questions to explore include how consistently a device delivers without excessive resistance, how retrieval complexity is managed, how the manufacturer supports post-market documentation and adverse event responsiveness, and how the device performs within institutional protocols for timely removal. Preference for products that reduce variability and support standardized retrieval pathways can help lower downstream complication costs and improve procedural predictability. At the same time, procurement strategies should account for supply continuity and the need for training support as advanced retrieval tools become more integrated into clinical practice.
For stakeholders seeking a deeper, segment-level view of market sizing, regional dynamics, product category splits, application patterns, competitive benchmarks, and customized scenario planning, the full PW Consulting research report provides a more granular analytical foundation. The complete study extends the discussion beyond the strategic overview presented here and offers detailed data structures, forecasting detail, and tailored recommendations designed to support operational planning and investment decisions in a market where clinical credibility and procedural efficiency are becoming the decisive dimensions of long-term competitive advantage.
For detailed analysis of this topic, please visit the official page: Inferior Vena Cava (IVC) Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


