



Flexible Heating Element Market: Why 8.37% CAGR and EV Demand Reshape Strategy

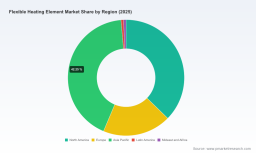
Navigating the Flexible Heating Element Market: Strategic Trends and Commercial Opportunities
The flexible heating element market has evolved from a niche thermal management solution into a critical enabler of performance across high-growth industries. This analysis examines the market's trajectory, the structural forces reshaping competitive dynamics, and the strategic imperatives for manufacturers, investors, and procurement leaders navigating the next cycle of growth.
Market Overview and Current Challenges
The global market for flexible heating elements has demonstrated consistent expansion over the past half-decade, driven by cross-sector demand for precision thermal control, compact form factors, and reliable performance in demanding environments. From 2020 through 2025, the market grew from approximately $0.95 billion to $1.42 billion, reflecting an accelerating adoption curve as end-use industries integrated flexible heating into increasingly complex product architectures. Forecasts indicate the market will continue its upward trajectory through 2032, surpassing the $2.4 billion mark by the end of the forecast window and maintaining a compound annual growth rate of 8.37 percent. This growth profile places flexible heating alongside other high-value thermal management sub-segments, but the underlying demand drivers are distinct in their technical specificity and regulatory sensitivity.
PW Consulting Automotive & Machinery Research Center
Several structural challenges are reshaping how companies approach product development, pricing, and market entry. First, the divergence in material performance requirements across application verticals has pressured manufacturers to specialize rather than pursue broad commoditization strategies. Flexible heaters deployed in semiconductor processing, medical instrumentation, or aerospace assemblies demand different thermal profiles, reliability thresholds, and certification pathways. Companies that attempt to serve all segments with generic portfolios are encountering margin compression and longer qualification cycles. Second, the cost structure of advanced flexible heating technologies remains elevated relative to traditional alternatives. Precision etching, lamination, and custom trace design for polyimide-based solutions introduce manufacturing complexity that raises unit costs significantly compared to rigid heating alternatives. Carbon-based and specialty conductive traces further compound material expenses, creating a cost differential that buyers must weigh against performance gains. Third, regulatory and certification requirements are tightening across target markets. Energy efficiency expectations, safety standards, and application-specific qualification frameworks are becoming non-negotiable market access conditions rather than optional differentiators. These dynamics are compressing the timeline from concept to volume production and rewarding organizations with established compliance capabilities and engineering partner ecosystems.
Worldwide Contact Heating Elements Market
Key Drivers Reshaping the Market
Technological Innovation and Material Performance
Material science advances are the most persistent driver of market evolution. Polyimide-based flexible heaters continue to gain traction in applications requiring high watt density, thermal stability, and compatibility with precision electronic assemblies. Recent industry demonstrations have highlighted pure-polyimide heater architectures achieving UL 94 V0 certification and progressing through ESA qualification pathways, signaling that high-reliability flexible heating is becoming viable for space-grade and mission-critical deployments. At the same time, silicone rubber solutions remain dominant where cost sensitivity, form-factor flexibility, and moderate thermal requirements intersect. The parallel development of both material tracks reflects a market that is simultaneously pushing performance boundaries and optimizing for volume economics. Innovations in integrated sensors, embedded thermocouples, and custom circuit design are also reducing the friction between heating element selection and system-level thermal management. Manufacturers offering combined heating and sensing solutions are shortening integration cycles for OEMs that previously managed these components separately.
Policy and Regulatory Environment
Regulatory expectations are acting as both a constraint and a catalyst. Stringent energy efficiency standards and safety requirements are pushing manufacturers toward designs that minimize thermal waste, improve temperature uniformity, and reduce failure modes. In medical and space applications, recognized construction standards and qualification frameworks have become baseline requirements rather than premium features. The emergence of clear certification milestones, such as UL recognition and ESCC qualification for specialized flexible heaters, is narrowing the field for suppliers serving regulated verticals. This regulatory intensification favors established players with documented qualification histories and penalizes new entrants lacking the testing infrastructure or compliance documentation to compete in high-stakes segments. Simultaneously, it creates an opportunity for suppliers that can package compliance readiness as a service, reducing the burden on OEMs navigating complex approval processes.
Demand-Side Shifts in End-Use Industries
Demand patterns are being reshaped by architectural changes in key end-use sectors. In automotive and transportation, the continued emphasis on battery thermal management and cabin comfort solutions is increasing the relevance of flexible heaters that can be integrated into tight mechanical envelopes without compromising durability. Electronics and semiconductor applications are driving demand for localized, precisely controlled heating in processing equipment, test fixtures, and advanced packaging workflows. Medical device manufacturers are seeking high-wattage flexible heating options that enable faster thermal response in compact instrumentation, while aerospace and defense programs are prioritizing lightweight, high-reliability heating solutions with documented qualification records. These demand shifts are not uniform; they create pockets of accelerated growth where performance requirements align with the technical advantages of flexible heating. Companies able to map application-specific requirements to material and design capabilities are seeing stronger conversion rates and shorter sales cycles in targeted verticals.
Supply Chain and Cost Structure Dynamics
Cost structures in flexible heating are being recalibrated by a combination of material pricing, processing complexity, and customer demand for lower minimum order quantities. Specialty conductive traces and carbon-based materials continue to elevate raw material costs relative to silicone rubber alternatives, while precision etching and lamination steps add manufacturing overhead for polyimide-based products. At the same time, new market entrants are introducing low-MOQ offerings and free design support to reduce barriers for prototyping and low-volume production. This shift is particularly relevant for electronics, EV, and medical applications where design iteration cycles are short and upfront cost risk must be minimized. The tension between premium material performance and accessible entry pricing is creating a more stratified market, with volume-driven cost optimization on one end and high-reliability, specification-driven solutions on the other. Suppliers that can navigate this spectrum without sacrificing quality or lead time are positioning themselves to capture demand across multiple tiers of the market.
Competitive Landscape and Leading Strategies
The competitive field in flexible heating is defined by a mix of established manufacturers with deep application expertise and newer entrants lowering barriers to adoption through accessible pricing and design support. Market concentration remains moderate, with a core group of leading suppliers accounting for a significant share of high-value contracts, while a broader tail of regional and specialty providers competes on customization, lead time, and niche qualification capabilities.
Electric Heating Elements (Electric Heater) Market
Several strategic positioning patterns are emerging among the most competitive players. One clear approach is engineering partnership and custom material specialization. Suppliers that emphasize custom polymer thick film, silicone rubber, polyimide, and etched foil technologies are building advantage through the ability to adapt heater geometry, watt density, and sensor integration to specific customer architectures. This model thrives in applications where standard off-the-shelf solutions cannot meet thermal or mechanical constraints, such as mission-critical medical assemblies or high-reliability aerospace systems. A second approach centers on accessibility and speed for prototyping and low-volume production. By removing minimum order quantity requirements, offering free circuit design assistance, and accelerating delivery timelines, some providers are capturing early-stage design wins in electronics, EV, and medical applications. This strategy is particularly effective in environments where engineers are evaluating multiple thermal options before committing to volume tooling. A third approach is qualification leadership in regulated verticals. Companies advancing ESA qualification, ESCC compliance, and UL certification for specialized polyimide heaters are differentiating through documented reliability and the ability to support space and high-performance applications with reduced qualification burden for the buyer.
Recent company-level developments illustrate these dynamics in action. In late 2025, one Italian manufacturer presented validation data on a pure-polyimide flexible heater architecture, including cross-sectional analysis, thermal aging results, cycled life testing, UL 94 V0 certification, and ongoing ESA qualification. Around the same period, the same group showcased flexible heating solutions at a major space commerce event and later presented thermal management systems incorporating flexible heater options at a mobility conference. These activities signal a deliberate push into high-reliability and transportation-adjacent applications where qualification and system-level integration are decisive. In early 2025, a provider of highly customized flexible heaters introduced a high-wattage polyimide heater aimed at medical applications, supporting elevated watt density and higher operating temperatures. Meanwhile, a China-based manufacturer expanded its offerings with a full flexible heater product line spanning polyimide and silicone rubber, removing MOQ constraints, including free design support, and emphasizing rapid delivery for prototyping. Together, these moves highlight a market where leaders are simultaneously advancing performance credentials and broadening access points for design-phase customers.
The competitive landscape is evolving through a combination of specialization and selective convergence. On one side, demand for application-specific qualification and advanced material configurations is encouraging divergence, as manufacturers deepen expertise in targeted verticals rather than competing on generic specifications. On the other side, the entry of lower-friction prototyping and low-MOQ providers is broadening the supplier base at the design stage, increasing pressure on incumbents to clarify their value proposition beyond legacy relationships. The likely outcome is a more layered competitive structure: premium, qualification-heavy suppliers anchoring high-reliability and regulated segments, agile custom manufacturers serving engineering-intensive applications, and accessible providers capturing early design exploration and shorter-run production. Integration activity may increase where scale advantages in materials, testing, and certification can be leveraged, but the market's technical diversity suggests that pure breadth plays will face persistent margin and service-level challenges.
Future Trends and Commercial Implications
Trend 1: Qualification-as-a-Service Becomes a Competitive Differentiator
As regulatory expectations and application-specific qualification requirements become more entrenched, suppliers that can package compliance readiness, testing documentation, and recognized construction standards as part of their offering will gain an advantage in medical, aerospace, and high-reliability industrial applications. Over the next three to five years, this trend will likely intensify as OEMs seek to reduce internal qualification burden and compress time-to-market. The commercial opportunity lies in positioning flexible heating not just as a component but as a qualified subsystem that lowers integration risk. The associated risk is that certification pathways remain fragmented across regions and application categories, creating uneven market access and raising the cost of maintaining multi-jurisdiction compliance.
Trend 2: High-Watt Density and Precision Thermal Control Expand into New Applications
Advances in polyimide and specialty heater architectures are enabling higher watt density and tighter temperature control in compact form factors. This is opening doors in medical instrumentation, advanced electronics processing, and selective automotive thermal management scenarios where rapid thermal response and spatial constraints are critical. The commercial implication is a gradual shift in addressable use cases beyond traditional heating roles, creating incremental growth in segments that previously relied on less flexible thermal solutions. The risk is that performance claims must be substantiated through consistent manufacturing quality and validated life testing, particularly in regulated applications where failure modes carry high consequences.
Trend 3: Lower- friction Entry Models Accelerate Design-Phase Competition
The availability of low-MOQ offerings, free design support, and rapid prototyping pathways is changing how flexible heating solutions are evaluated and selected. Engineering teams are increasingly able to test multiple material and geometry options early in the design cycle, which raises the importance of first-turn responsiveness and design collaboration. For suppliers, this trend expands the top of the funnel but also increases the volume of speculative design activity that must be managed efficiently. The commercial opportunity is to convert early-phase engagement into volume production through reliable execution, consistent quality, and clear scaling pathways. The risk is margin erosion if prototyping convenience is not paired with a credible plan for transitioning customers to higher-volume, cost-optimized production models.
Strategic Recommendations for Decision-Makers
For manufacturers and suppliers, the most effective path is to align product portfolios with application-specific qualification needs and material performance requirements rather than competing solely on breadth. Companies should prioritize documented certification status where regulated verticals are a strategic target, invest in engineering collaboration that reduces integration risk for customers, and maintain a credible low-volume entry point without compromising the economics of scale production. Differentiation will increasingly come from the ability to manage the full arc from prototype to qualified volume production, not from component specification alone.
For investors, the market presents selective opportunities where technical barriers, qualification depth, and application concentration combine to support durable positioning. Capital allocation should favor companies with clear vertical focus, demonstrated compliance capabilities, and operating models that can absorb the cost complexity of advanced materials without relying on undifferentiated volume. Monitoring the pace of certification progression, the emergence of integrated heating-and-sensing offerings, and the extent to which accessible prototyping models convert into recurring production demand will be important indicators of which players are building sustainable advantage.
For procurement and engineering leaders, the priority is to treat flexible heating selection as a system-level decision rather than a component sourcing exercise. Evaluating suppliers on qualification documentation, design support responsiveness, and the ability to scale from prototype to production will reduce downstream integration risk. Where performance requirements justify it, premium material architectures and recognized certifications should be weighed against total lifecycle cost and reliability exposure rather than unit price in isolation. Early engagement with suppliers that can provide both design flexibility and compliant production pathways will shorten qualification timelines and improve launch certainty.
The flexible heating element market is moving toward a more segmented, qualification-aware, and design-integrated future. Companies that understand where performance, regulation, and cost dynamics intersect will be best positioned to capture the next phase of growth. For decision-makers seeking detailed segmentation data, competitive benchmarking, and customized scenario planning across regions and applications, the full research report provides the deeper dataset and structured analysis required to translate these trends into specific organizational actions.
For detailed analysis of this topic, please visit the official page: Flexible Heating Element Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


