



DNA Sequencing Market: How 14.9% CAGR and NGS Redefine Growth

The DNA Sequencing Market: Strategic Trends and Commercial Opportunities for the Next Decade
The global DNA sequencing market has entered a decisive phase of expansion, driven by converging advances in platform technology, regulatory momentum, and widening clinical adoption. From 2020 through 2025, the market grew from approximately $9.1 billion to $16.9 billion, reflecting a sustained upward trajectory that has extended into early forecast years. Projections point to continued acceleration through 2032, with the market anticipated to reach $44.6 billion and a compound annual growth rate of 14.9% across the forecast horizon. This growth is not merely incremental; it reflects a structural shift in how sequencing is positioned across research, clinical diagnostics, public health, and commercial genomics.
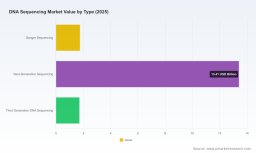
The current market base is anchored by next-generation sequencing, which commands the largest revenue share and underpins most high-throughput diagnostic and research workflows. Alongside this dominant modality, third-generation and single-molecule approaches are carving out specialized niches where read length, phasing, or real-time observation deliver distinct analytical advantages. The segment composition reveals a market that is simultaneously consolidating around platform standardization while preserving room for differentiated technologies that address specific biological or operational questions.
Beneath the headline growth figures, however, lie structural tensions that will shape competitive outcomes over the next several years. Three challenges stand out as particularly consequential. First, the industry faces mounting pressure to translate sequencing throughput into interpretable clinical action without inflating downstream bioinformatics costs. Second, supply chain and reagent economics remain sensitive to manufacturing scale, component availability, and the geographic concentration of platform suppliers. Third, the market is navigating a regulatory evolution that is becoming more prescriptive around validation, quality control, and data comparability, especially as sequencing moves deeper into diagnostic and therapeutic development pathways.
These dynamics matter because they determine who can convert technology leadership into durable commercial advantage. Companies that treat sequencing solely as an instrument business are increasingly exposed to commoditization risk, while those that integrate workflows, informatics, and evidence generation are building moats around recurring value.
Key Drivers Shaping the Market Trajectory
The expansion of sequencing adoption is being propelled by a set of reinforcing drivers rather than a single breakthrough. Understanding their interplay is essential for assessing where value will accumulate.
Technology Innovation and Platform Differentiation
Platform innovation continues to reshape what sequencing can deliver in terms of speed, cost, and biological resolution. Short-read next-generation systems remain the workhorse for high-volume applications, but long-read and single-molecule technologies are expanding the envelope for structural variant detection, haplotype resolution, and complex genome assembly. At the same time, a new wave of benchtop and high-throughput systems is targeting broader accessibility, with an emphasis on lowering total cost of ownership and simplifying operational complexity.
Recent product activity illustrates this direction. Illumina introduced a distributed whole-genome sequencing solution for highly sensitive minimal residual disease research, initially available to select partners with a broader commercial launch planned for 2027. This move signals a strategic push toward ultra-sensitive detection workflows that could bridge research and clinical oncology applications. In a different segment, Clear Labs launched an automated next-generation sequencing solution for Mycobacterium species identification and tuberculosis drug resistance mutation detection, underscoring how automation and targeted assay design are converging to reduce hands-on time and standardize results in pathogen testing.
The practical implication is that technology leadership is increasingly defined by workflow completeness rather than raw sequencing output alone. Systems that reduce sample preparation variability, streamline library construction, or pair sequencing with purpose-built analytics are gaining traction because they lower the barrier to reliable deployment across laboratories with varying levels of expertise.
Policy and Regulatory Environment
Regulatory and standardization activity is moving from passive oversight toward more active enablement, particularly where sequencing can improve safety assessment, outbreak response, and clinical trial initiation. In April 2026, the FDA distributed for comment a draft guidance on next-generation sequencing-based methods for safety assessment of genome editing in human gene therapy products, an indication that regulators are building frameworks to support more efficient evaluation of advanced therapies.
In parallel, public health mandates are creating structured demand for whole-genome sequencing in surveillance and outbreak investigation. The European Commission adopted regulation requiring member states to perform whole-genome sequencing on selected foodborne pathogen isolates for outbreak investigations, a policy shift that institutionalizes sequencing as a standard tool in epidemiological response. This kind of regulatory anchoring matters because it converts occasional demand into recurring, protocol-driven usage.
Standardization efforts are also advancing on the technical side. Development of ISO quality control metrics for DNA sequencing informatics has been progressing through enquiry phases, reflecting an industry-wide recognition that data quality, metadata consistency, and comparability across platforms will become increasingly important as sequencing data supports cross-institutional decision-making. Collectively, these regulatory and standards movements reduce ambiguity for adopters, but they also raise the bar for vendors that must demonstrate validation readiness and documentation rigor.
Demand-Side Shifts in Clinical and Commercial Settings
Demand is broadening beyond traditional research settings as sequencing becomes embedded in clinical workflows, precision medicine programs, and applied genomics. Oncology remains a central application arena, where sequencing supports biomarker discovery, therapy selection, residual disease monitoring, and translational research. At the same time, reproductive health, clinical investigation, and specialized typing applications continue to expand as laboratories seek higher-resolution insights from smaller sample volumes or more complex biological questions.
DNA Microarray Market
A notable demand-side shift is the growing expectation that sequencing output should be paired with interpretable, clinically relevant reporting. Laboratories and health systems are less interested in raw sequence generation in isolation; they want integrated solutions that connect assay performance with actionable interpretation, whether for oncology panels, infectious disease characterization, or transplant-related typing. This expectation is nudging the market toward solution-oriented commercialization, where value is created not just by selling instruments and reagents but by reducing the operational and cognitive burden on end users.
Sanger Sequencing Service Market
Cost Structure and Supply Chain Realities
Cost dynamics remain a fundamental driver of adoption, but the conversation has evolved beyond instrument price alone. Total cost of ownership now encompasses reagent economics, throughput utilization, labor intensity, failure rates, and informatics overhead. Manufacturers that can improve reagent efficiency, increase instrument uptime, or reduce consumable waste are able to offer compelling economics even when headline pricing appears similar across competitors.
Supply chain resilience has also become a strategic concern. The concentration of platform manufacturing and key consumable production creates dependencies that can affect availability, lead times, and regional pricing. As a result, some customers are evaluating multi-vendor strategies or prioritizing suppliers with stronger regional support and service networks. For vendors, this environment rewards operational reliability and transparent supply planning as much as it rewards technical specifications.
Competitive Landscape and Leading Strategies
The competitive structure of the DNA sequencing market is characterized by high concentration at the top, alongside active experimentation by emerging and specialized players. Roughly two-thirds of market revenue is associated with a small group of leading firms, and the top five together account for a substantial majority of revenue. This concentration does not imply stagnation; rather, it reflects the scale advantages involved in platform development, global service support, consumables ecosystems, and regulatory readiness.
Illumina remains a central force in next-generation sequencing, with a broad installed base and a portfolio spanning instruments, reagents, and applications-oriented research tools. Its recent emphasis on distributed whole-genome sequencing for minimal residual disease research suggests a strategy aimed at deepening relevance in high-value oncology workflows where sensitivity and reproducibility are paramount. Thermo Fisher Scientific offers a complementary breadth, combining next-generation sequencing, Sanger sequencing, and genomics instruments with a large consumables footprint. Its advantage lies in portfolio integration across multiple laboratory needs, which can simplify procurement and cross-platform support for institutions seeking operational consistency.
Oxford Nanopore Technologies and Pacific Biosciences represent long-read and single-molecule approaches with distinct technological identities. Oxford Nanopore’s nanopore-based platforms emphasize portable and real-time sequencing capabilities, which can be advantageous for field deployment, rapid pathogen characterization, and applications where flexibility matters. Pacific Biosciences focuses on high-fidelity long-read systems and single-molecule real-time technology, positioning around accuracy and read length for complex genomic analysis. Both companies illustrate how specialized technology narratives can sustain differentiated market positions even within a market dominated by short-read scale.
A second tier of challengers and specialists is expanding the boundaries of cost, automation, and application focus. Element Biosciences has introduced a benchtop next-generation sequencing platform designed for high-throughput, cost-effective sequencing, targeting laboratories that want strong performance without the footprint or economics of larger systems. Ultima Genomics has pursued high-throughput, cost-efficient sequencing for population-scale genomics, an approach that speaks directly to large cohort studies and initiatives where per-sample economics are critical. BGI Group, through its MGI technology offerings, continues to compete with whole-genome and targeted sequencing platforms, leveraging manufacturing scale and regional presence.
QIAGEN remains relevant through library preparation, sequencing panels, and hybrid capture technologies, areas where upstream sample and target enrichment can be as important as the sequencing run itself. Clear Labs is advancing fully automated next-generation sequencing for pathogen and oncology applications, with product activity such as its automated mycobacteria and tuberculosis resistance solution highlighting a focus on hands-off, clinically oriented workflows. Tempus AI illustrates a different model altogether, integrating whole-genome sequencing assays with an artificial intelligence-driven precision medicine platform, effectively linking sequencing data to decision support and clinical interpretation.
This landscape is evolving along several axes. One is consolidation around integrated solutions, where instrument, consumable, software, and support offerings are bundled to reduce fragmentation for customers. Another is fragmentation at the application layer, where specialists compete on speed, automation, or niche assay performance rather than on general-purpose throughput alone. A third is the continued entry of new platforms that challenge incumbent economics, particularly in benchtop and high-throughput cost-per-sample segments. The net effect is a market where incumbents must defend installed bases and recurring consumables revenue while newcomers and specialists attempt to open whitespace through operational simplicity, price advantage, or application specificity.
Future Trends and Commercial Implications
Looking ahead three to five years, several trends are likely to define the market's direction and shape commercial opportunities.
One major trend is the continued movement from sequencing as a data generation step toward sequencing as an integrated diagnostic and decision-support component. This will favor organizations that can align assay design, automation, bioinformatics, and reporting into cohesive workflows. The commercial opportunity lies in reducing turnaround time and interpretation burden, particularly in oncology and infectious disease settings where timely results influence clinical decisions. The risk is that integration expectations rise faster than standardization, creating interoperability challenges and increasing the cost of maintaining multiple workflow ecosystems.
A second trend is the growing institutionalization of whole-genome sequencing in public health, food safety, and surveillance contexts. Regulatory and policy anchors can create durable demand, but they also require consistent quality, traceability, and comparability across laboratories. Companies positioned to support standardized surveillance workflows, including validated panels, reference materials, and data reporting tools, may benefit from this shift. The uncertainty lies in how uniformly these mandates are implemented across regions and how quickly resource-constrained laboratories can adopt the required infrastructure.
A third trend is the intensifying competition around cost-efficient scale. As more platforms pursue lower per-sample economics, pressure will increase on incumbents to defend margins through workflow efficiency, service models, and differentiated applications rather than price alone. This environment can accelerate adoption among cost-sensitive users, but it also raises the stakes for suppliers that depend heavily on reagent and consumable revenue. The strategic opportunity is to pair economic competitiveness with value-added services such as bioinformatics, assay optimization, and laboratory workflow consulting, which can improve stickiness and reduce direct price sensitivity.
Across these trends, a shared risk is the possibility that technological promise outpaces evidentiary and regulatory readiness in certain clinical settings. Where claims outstrip validated utility, adoption may slow, reimbursement pathways may remain uncertain, and customers may become more cautious about platform commitments. Another risk is geopolitical and supply chain volatility, which can affect reagent availability, service continuity, and regional pricing stability. Companies planning long-cycle investments should therefore model not only technology adoption but also resilience and support capacity.
Strategic Actions for Decision-Makers
The current market environment rewards clarity of positioning and discipline in execution. Different stakeholder groups will need to prioritize differently, but several actions are broadly relevant.
For sequencing platform and consumable manufacturers, the priority is to strengthen total workflow value rather than competing solely on instrument specifications. That means investing in assay compatibility, library preparation efficiency, automation, and bioinformatics support that reduce customer friction. It also means preparing for a regulatory environment that increasingly expects validation documentation and quality control rigor. Companies that can demonstrate reliable performance across diverse laboratory settings, while maintaining clear service and supply commitments, will be better positioned to defend recurring revenue and expand into higher-value applications.
For investors, the most important question is where durable demand is being created versus where adoption depends primarily on technology enthusiasm. Workflow-integrated solutions, surveillance-driven public health demand, and oncology applications with clear clinical interpretation pathways offer stronger signals of sustained use than instrument launches alone. At the same time, concentration in the market means that competitive disruption can come from cost-efficient challengers, application specialists, or software-centric models that change how sequencing data is converted into decisions. Due diligence should therefore assess not only platform performance but also consumables economics, service networks, regulatory readiness, and the defensibility of any proprietary informatics or assay IP.
For procurement and laboratory decision-makers, the focus should be on total cost of ownership and operational fit. Instruments with attractive sticker prices can become expensive if they underutilize capacity, require specialized labor, or create informatics bottlenecks. Evaluating vendors on reliability, support responsiveness, assay breadth, and compatibility with existing workflows can yield better long-term outcomes than selecting solely on benchmark performance. It is also prudent to consider multi-platform strategies where applicable, especially in settings where application diversity or supply resilience matters more than single-vendor simplicity.
Across all of these roles, the pace of change in sequencing technology, regulation, and application design makes timely, detailed market intelligence valuable. Segment-level demand patterns, regional adoption differences, platform economics, and the regulatory calendar all influence where opportunities are emerging and where assumptions may be outdated. For organizations seeking deeper segmentation data, competitive benchmarking, and tailored scenario planning, a more detailed study of the DNA sequencing market can provide the granularity needed to support investment, product, and procurement decisions with greater confidence.
PW Consulting Health Care Research Center
For detailed analysis of this topic, please visit the official page: DNA Sequencing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


