



Liquid Malt Extracts Market: Why the 3.8% CAGR Story Is Just the Beginning

Strategic Horizons: Navigating the Liquid Malt Extracts Market Amidst Transition and Growth
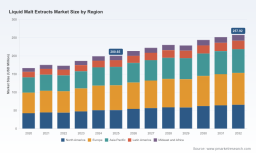
The liquid malt extracts market is at an inflection point where steady growth intersects with complex operational and strategic shifts. Based on 2025 as the base year, the market has demonstrated resilience over the historical period from 2020 to 2025, and current trajectories suggest a compound annual growth rate of 3.8% throughout the forecast period extending to 2032. The total revenue is projected to evolve from approximately 200.65 million in 2025 to nearly 257.92 million by 2032. This expansion is not merely a reflection of population growth but indicates a deepening integration of malt extracts into diverse value chains, driven by shifting consumer preferences and industrial efficiencies. However, the path forward is not uniform; it is characterized by specific challenges that require strategic navigation to capitalize on the projected upside.
Market Overview and Structural Dynamics
The broader market landscape suggests a moderate but consistent expansion, with the revenue trajectory indicating a cumulative increase over the forecast horizon. The top three players hold a combined share of 28.4%, while the top five account for 39.5%, indicating a moderately concentrated market structure that leaves room for both established dominance and targeted disruption by niche players. This fragmentation across the competitive spectrum suggests that while scale advantages exist, specialization and regional agility remain viable pathways for growth.
Key Challenges and Inflection Points
Despite the positive growth outlook, the industry faces distinct headwinds that could alter competitive dynamics. First, raw material volatility presents a persistent operational risk. Barley, the dominant upstream feedstock, is subject to regional price fluctuations. Recent data points to a 5% month-to-month increase in US malting barley prices in early 2026, signaling that cost pressures can escalate rapidly, squeezing margins for manufacturers who lack hedging strategies or diversified sourcing networks. Second, regulatory frameworks are reshaping cost structures and sourcing requirements. The European Union's Common Agricultural Policy includes provisions that affect barley supply and malt production costs, with forecasts for 2025/26 indicating modest year-over-year production changes in certain regions. These policy-driven variables can create unpredictable shifts in availability and pricing, necessitating proactive supply chain alignment. Third, the market is navigating a divergence in demand quality. While traditional applications remain strong, there is increasing pressure to provide extracts that meet specific functional, flavor, or sustainability criteria, pushing manufacturers to move beyond commodity-grade offerings toward differentiated solutions.
Worldwide Wheat Malt Market
Key Drivers of Market Evolution
Innovation in Product Formulation and Sustainability
Technological and process innovations are becoming central to competitive differentiation. Leading companies are increasingly focusing on the sustainability profile of their products as a value proposition. For instance, Muntons introduced Climate Positive Malt, which offers up to 30% lower carbon emissions per tonne compared to the UK malt average, leveraging regenerative agriculture practices. This type of innovation addresses the growing demand for transparency and reduced environmental impact, allowing suppliers to command premium positioning and align with the sustainability goals of downstream buyers. Such advancements demonstrate that product development is no longer solely about functional performance but also about embedding environmental credentials into the core offering.
Chocolate Liquid Extract Market
Regulatory and Policy Shifts Influencing Supply Chains
The regulatory environment acts as a double-edged sword, influencing both costs and opportunities. Policy adjustments, such as those within the EU's agricultural framework, can alter the economics of barley production, affecting the baseline costs for malt extract manufacturers. Simultaneously, global cereal market dynamics show that barley prices are influenced by spillover effects from tighter maize and wheat markets, with overall cereal indices rising in recent months. These interconnected commodity markets mean that malt extract producers must monitor broader agricultural trends, not just barley-specific metrics. Regulatory compliance and the ability to adapt to shifting subsidy or production incentives can become a source of competitive advantage for firms that integrate policy analysis into their strategic planning.
Demand-Side Shifts in Brewing and Food Applications
Consumer and industrial behavior continues to reshape application landscapes. In brewing, the pursuit of consistent flavor profiles and efficient production processes sustains the reliance on liquid malt extracts. However, there is a growing emphasis on specialty and clean-label ingredients that cater to niche beer styles and health-conscious consumers. In the food sector, the use of malt extracts in bakery and confectionery applications is being driven by the desire for natural sweeteners and flavor enhancers that align with clean-label trends. This demand-side evolution encourages manufacturers to expand their portfolios beyond standard extracts, offering tailored solutions that address specific texture, taste, or nutritional requirements. The shift toward premiumization in certain segments creates opportunities for suppliers that can demonstrate technical expertise and flexibility.
Supply Chain Adaptation and Cost Management
The structure of the supply chain is undergoing recalibration in response to volatility and demand complexity. With US barley production forecasted at 154 million bushels for 2025/26, a slight decrease from the prior year, feedstock availability remains stable but requires vigilant monitoring. Manufacturers are increasingly focusing on supply chain resilience, exploring long-term contracts, geographic diversification, and vertical integration where feasible. Cost management strategies are evolving to mitigate the impact of input price swings, with some players investing in process efficiencies to reduce yield losses and energy consumption. The ability to balance cost control with reliable supply is becoming a critical competency, distinguishing operators that can maintain margin stability in a fluctuating environment.
Competitive Landscape and Leading Strategies
Profiles of Market Leaders and Strategic Positioning
The competitive arena features a mix of large-scale manufacturers and specialized producers, each pursuing distinct strategic angles. Muntons, headquartered in Suffolk, UK, stands as Europe's largest manufacturer of malt extracts and malted ingredients, producing a range of liquid malt extracts for brewing, baking, and food applications. Its scale allows for broad market coverage, while its recent initiatives in sustainability, such as retaining a Gold EcoVadis Sustainability Rating for the sixth consecutive year, position it as a leader in corporate responsibility, appealing to buyers prioritizing ethical sourcing. The Malt Company, based in the United States, specializes in liquid malt extract products for homebrew and commercial brewing, offering premium LME variants. Its focus on the brewing segment enables deep technical specialization and brand loyalty among brewers seeking high-quality, consistent inputs. Ireks, located in Kulmbach, Germany, produces malt extracts including liquid malt extracts and related cereal ingredients for baking and brewing, leveraging its European base to serve regional demand with strong technical support. Doehler, from Darmstadt, Germany, provides malt-based ingredients and extracts for beverage and food industries, benefiting from a diversified ingredient portfolio that can cross-sell and integrate solutions across multiple applications. Briess Malt & Ingredients, based in Stevens Point, Wisconsin, USA, offers organic liquid malt extracts and concentrated brewers wort from 100% pure malted barley, targeting the premium and organic segments where certification and purity are key differentiators. Maltexco, in Belgium, manufactures liquid malt extracts and malted ingredients, serving the European market with a focus on quality and reliability. Barmalt, operating in Europe, produces liquid malt extracts for brewing and food sectors, maintaining a presence in the regional supply network. Malt Products, in the United States, specializes in malt-based ingredients including liquid malt extracts, catering to domestic demand with a focused product range. PureMalt Products, also in the United States, supplies liquid malt extracts for brewing and food applications, competing on service and product consistency. These companies illustrate the breadth of strategies, from scale and sustainability to specialization and organic focus.
Differentiation and Competitive Advantage
Leading players are carving out advantage through multiple levers. Scale players like Muntons leverage production capacity and geographic reach to serve large-volume customers while using sustainability credentials to enhance brand equity and meet the ESG criteria of global buyers. Specialty firms like The Malt Company and Briess Malt & Ingredients target specific niches, such as premium brewing or organic ingredients, where technical knowledge and product purity justify price premiums. Cross-industry players like Doehler utilize diversified portfolios to capture value across beverage and food segments, offering integrated solutions that reduce the procurement complexity for customers. The differentiation is increasingly multidimensional, combining product quality, certification, sustainability performance, and technical service. Companies that can articulate a clear value proposition across these dimensions are better positioned to defend margins and secure long-term contracts.
Evolution of Market Structure
The market structure is likely to evolve through a combination of consolidation and fragmentation. On one hand, the moderate concentration among top players suggests potential for further integration, as larger firms seek to expand their footprint through acquisitions or capacity expansions to capture economies of scale. On the other hand, the presence of numerous specialized players indicates that fragmentation will persist in niches where customization, regional focus, or specific certifications create barriers to entry for generalist competitors. New entrants may emerge in segments aligned with emerging trends, such as organic or climate-positive extracts, challenging incumbents to continuously innovate. The net effect is a dynamic landscape where strategic positioning must be continually reassessed to respond to both competitive moves and shifting demand patterns.
Future Trends and Commercial Opportunities
Sustainability as a Commercial Imperative
Sustainability is transitioning from a compliance requirement to a core commercial driver. With initiatives like Climate Positive Malt and sustained high sustainability ratings, the market is moving toward greater scrutiny of carbon footprints and agricultural practices. Over the next three to five years, extracts with verified lower emissions, regenerative sourcing, or organic credentials are expected to gain share in segments where buyers face pressure to reduce Scope 3 emissions or meet consumer expectations. This trend opens opportunities for manufacturers to develop certified sustainable product lines and for buyers to integrate these options into their procurement strategies to enhance their own sustainability narratives. The risk lies in the potential for greenwashing accusations or the cost of certification, which requires genuine process changes and transparent reporting.
Regional Divergence and Localization
Demand patterns are likely to exhibit regional divergence, influenced by local brewing traditions, food preferences, and regulatory environments. Europe continues to represent a significant portion of market value, with strong industrial brewing and bakery sectors, while North America maintains a robust demand base supported by both commercial and craft brewing. Asia Pacific shows potential for growth as brewing and processed food industries expand, though infrastructure and taste preferences may shape the pace of adoption. Latin America and the Middle East and Africa represent smaller but potentially emerging markets where urbanization and changing consumption habits could drive incremental demand. Manufacturers that can localize products, adapt to regional application requirements, and navigate local regulatory nuances will be better equipped to capture growth in diverse geographies. The risk includes overgeneralization, where a one-size-fits-all approach fails to resonate with regional buyers.
Premiumization and Specialty Extracts
The push toward premiumization is expected to accelerate, with buyers seeking extracts that offer specific functional benefits, distinct flavor profiles, or certification advantages. Specialty malt extracts, encompassing niche varieties tailored for particular applications or consumer segments, represent a growth avenue that aligns with this trend. As the market matures, the share of standard commodity extracts may stabilize or grow more slowly, while specialty segments capture higher margins and foster loyalty through performance and differentiation. This shift encourages investment in R&D, process control, and application testing to meet the precise needs of brewers and food manufacturers. The uncertainty is that premiumization may be sensitive to economic cycles, and in downturns, buyers might trade down, pressuring premium positions unless the value proposition is robust and demonstrable.
Strategic Recommendations for Decision Makers
For Manufacturers and Producers
Manufacturers should prioritize building resilience and differentiation simultaneously. Diversifying barley sourcing and establishing hedging mechanisms can mitigate raw material volatility, protecting margins against sudden price swings. Investing in sustainability certifications and process innovations, such as reducing carbon intensity or adopting regenerative practices, can create a defensible competitive edge and open access to premium customer segments. Expanding technical service capabilities and application support can deepen customer relationships, particularly in brewing and food sectors where performance and consistency are paramount. Additionally, exploring strategic partnerships or selective acquisitions can strengthen market position, especially in regions or segments where scale or local presence offers advantages.
For Investors and Capital Allocators
Investors should focus on companies with clear strategic positioning and the ability to execute in a changing environment. Evaluate players that demonstrate strong sustainability credentials, as these are increasingly tied to customer selection and long-term contract viability. Assess the balance between scale and specialization; large, diversified firms may offer stability, while niche leaders with premium products can deliver margin resilience if they maintain technical leadership. Monitor regulatory developments and commodity trends that could impact cost structures, as these factors can alter profitability trajectories. Opportunities may exist in segments aligned with organic growth, specialty extracts, or regions with expanding brewing and food processing industries, provided the competitive dynamics and entry barriers are well understood.
For Procurement and Supply Chain Leaders
Procurement professionals should approach sourcing with a focus on risk mitigation and value creation. Diversifying the supplier base can reduce exposure to regional volatility and supply disruptions, ensuring continuity for critical applications. Engaging with suppliers that offer transparency on sustainability metrics and certifications can support internal ESG goals and enhance brand positioning downstream. Prioritizing long-term relationships with suppliers that demonstrate technical support and consistent quality can reduce total cost of ownership by minimizing variability and production issues. Evaluating specialty extract options for specific applications may yield functional benefits that justify cost premiums, particularly where product differentiation or clean-label attributes are strategic priorities. Staying informed about market trends and regulatory shifts enables proactive adjustments to sourcing strategies, ensuring alignment with evolving business needs.
The liquid malt extracts market offers a landscape of moderate growth underpinned by structural demand and evolving value drivers. Success in this environment requires a clear understanding of cost dynamics, sustainability imperatives, and the shifting priorities of brewing and food manufacturers. The depth of segmentation, regional nuances, and competitive benchmarks warrants continuous monitoring and detailed analysis to inform precise strategic moves. For decision makers seeking to navigate these complexities with confidence, comprehensive research that unpacks granular data, competitive profiling, and scenario-based insights can provide the foundation for informed action.
PW Consulting
For detailed analysis of this topic, please visit the official page: Liquid Malt Extracts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


