



Diesel Particulate Filter Market 2026: Beyond the 6.98% CAGR Growth

The Diesel Particulate Filter Market: Navigating Growth, Regulation, and Technological Shifts Through 2032
Market Evolution: Scale, Trajectory, and Structural Pressures
The global Diesel Particulate Filter market has undergone a period of measured expansion followed by a noticeable acceleration in recent years. From 2020 through 2025, revenue growth reflected the gradual integration of stricter emission standards, sustained commercial vehicle production, and steady aftermarket demand. The market crossed the twenty-billion-dollar threshold in 2025, establishing a new baseline for subsequent growth. Looking ahead through 2032, the sector is projected to expand at a compound annual growth rate of approximately 6.98 percent, with values climbing steadily each year as original equipment adoption and fleet compliance programs compound.
This trajectory is not merely a function of vehicle population growth. It represents a market responding to structural regulatory pressure, technological maturation, and shifting commercial operating models. Growth is increasingly distributed across mature compliance markets and emerging regions where emission control adoption is still catching up to established standards. The overall expansion reflects both incremental volume gains and unit price movements driven by more advanced substrate configurations, integrated thermal management systems, and software-enabled regeneration strategies.
Despite the positive outlook, the market faces several structural challenges that will shape competitive outcomes over the next several years. The first challenge lies in balancing emission performance with operational efficiency. Operators increasingly demand filters that maintain high particulate reduction without imposing excessive backpressure or fuel penalties during regeneration cycles. The second challenge stems from regulatory fragmentation. While certain jurisdictions have standardized verification and certification pathways, others maintain divergent testing protocols, sulfur limits, and retrofit approval processes. This creates uneven deployment timelines and complicates cross-regional supply strategies. The third challenge is material and manufacturing cost stability. Substrate selection, coating formulation, and thermal durability requirements continue to place pressure on production economics, particularly for smaller OEMs and aftermarket suppliers operating on tighter margins.
Engine Filter Market
Core Drivers Reshaping the Market Landscape
Several interconnected forces are accelerating change in the diesel emission control sector. Understanding how these drivers interact is essential for positioning products, sourcing strategies, and investment decisions.
Technological Innovation and Material Performance
Material science remains one of the most decisive differentiators in filter performance. Silicon carbide substrates, for example, provide higher filtration efficiency and superior thermal stability at elevated operating temperatures compared with traditional cordierite alternatives. This advantage translates into more consistent particle number reduction at lower backpressure, which is increasingly valued in applications where engine efficiency and regeneration reliability matter most. At the same time, catalyst formulations and coating technologies continue to evolve, enabling better soot oxidation, reduced dosing requirements, and more robust performance under varied duty cycles.
The significance of this innovation layer extends beyond peak performance metrics. Better substrate and catalyst combinations reduce the frequency of active regeneration events, improve cold-start behavior, and help systems remain within compliance thresholds across a wider range of operating conditions. As a result, OEMs and fleet operators are increasingly willing to pay a premium for solutions that lower total cost of ownership rather than focusing solely on upfront hardware cost.
Policy and Regulatory Momentum
Regulatory frameworks continue to act as the primary catalyst for market demand. Verified diesel particulate filter systems are being updated and reaffirmed in multiple jurisdictions, with certification programs regularly incorporating new retrofit and OEM configurations. In the United States, verification guidelines have reinforced requirements for ultra-low-sulfur diesel use and confirmed particulate reduction thresholds that systems must meet to remain approved for non-road and heavy-duty applications. These standards do more than constrain emissions; they shape procurement eligibility, fleet compliance roadmaps, and aftermarket replacement cycles.
In parallel, regional certification processes continue to govern which systems can be legally deployed in specific environments. California's verification and executive order processes, for instance, illustrate how marine and off-road applications must meet distinct certification expectations even within the same broader regulatory ecosystem. This layered approval landscape encourages manufacturers to design products that can satisfy multiple verification pathways while still providing application-specific tuning for thermal load, exhaust flow, and particulate loading profiles.
Demand-Side Shifts in Commercial and Off-Highway Segments
Demand patterns are shifting not only by geography but also by usage profile. Passenger vehicles and light commercial vehicles remain significant contributors to volume, but heavy-duty trucks and off-highway equipment are increasingly central to compliance-driven demand. Operators in logistics, construction, mining, and municipal services face mounting pressure to maintain older assets while meeting evolving emission expectations. That dynamic sustains retrofit and replacement demand even in markets where new vehicle sales fluctuate.
Fleet managers are also becoming more sophisticated buyers. Rather than treating emission control hardware as a standalone compliance purchase, they are evaluating how filters interact with engine calibration, fuel quality, maintenance intervals, and downtime risk. This shift benefits suppliers that can offer integrated system advice, service support, and performance guarantees rather than purely transactional hardware sales.
Supply Chain and Cost Structure Dynamics
The production economics of diesel particulate filters are influenced by raw material availability, substrate pricing, coating complexity, and manufacturing scale. As performance expectations rise, the cost gap between lower-efficiency and higher-efficiency substrate options becomes more consequential. Manufacturers must balance the performance advantages of advanced materials with the need to remain competitive in price-sensitive segments.
Supply chain resilience has also become a strategic consideration. Filters depend on specialized ceramic materials, precious metal components, and precision manufacturing processes. Disruptions in any of these layers can affect lead times and unit costs. Companies that diversify sourcing, secure long-term material agreements, and invest in process optimization are better positioned to protect margins during periods of volatility.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The diesel particulate filter market features a broad set of global and regional players, each anchored in different strengths across materials, catalytic chemistry, system integration, and application expertise. While no single company dominates the field outright, competitive advantage increasingly stems from how well manufacturers combine substrate performance, catalyst formulation, thermal management, and service capability.
Industrial and chemical specialists have strengthened their position by investing in catalyst research infrastructure and process technology. Recent moves such as the inauguration of a catalyst development and solids processing center reflect a continued focus on R&D capacity for emission control systems. These investments matter because they shorten the cycle from material experimentation to production-ready formulations, enabling faster response to evolving regulatory specifications and customer performance requests.
Materials and components leaders bring deep expertise in ceramic substrates and advanced filtration media. Their advantage lies in balancing filtration efficiency, thermal durability, and mechanical strength, particularly in demanding heavy-duty and off-highway environments. Companies with strong substrate capability can offer more consistent performance across a wider temperature and duty-cycle range, which supports both OEM integration and aftermarket replacement strategies.
System integrators and emission control specialists occupy another critical niche. Their value proposition often centers on combining filtration hardware with regeneration strategies, monitoring approaches, and application-specific tuning. By offering complete system perspectives, these players can address fleet compliance goals more comprehensively, particularly where retrofit certification and operational reliability must be proven simultaneously.
Automotive and thermal management suppliers contribute expertise in packaging, airflow control, and integration with broader vehicle or engine architectures. Their ability to fit emission systems into constrained spaces while maintaining heat management and regeneration reliability is especially important for light commercial and passenger vehicle applications. In parallel, catalyst and chemical suppliers play a supporting but vital role by enabling lower dosing, improved oxidation behavior, and longer service life through advanced additive and coating technologies.
The competitive landscape is evolving along several directions. Consolidation remains relevant where scale advantages in R&D, manufacturing, and certification create barriers for smaller players. At the same time, differentiation is intensifying through application specialization, with suppliers tailoring offerings for marine, off-road, heavy-duty, and urban fleet environments. New entrants and niche specialists continue to appear where they can address regional certification needs, retrofit compatibility, or specialized duty cycles that broader portfolios may not serve optimally. The result is a market that rewards both scale and specificity, depending on the segment and geography in question.
PW Consulting
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The next phase of market development will likely be defined by the interaction between regulatory enforcement, material performance, and commercial operating priorities. Three trends stand out as particularly influential.
Higher Performance Baselines Become the Norm
As verification standards remain stringent and operators become more familiar with emission control performance expectations, the acceptable baseline for filtration efficiency and thermal durability will continue to rise. Systems that merely meet minimum compliance thresholds will face growing pressure from solutions that reduce backpressure, improve regeneration stability, and extend service intervals. This trend creates opportunities for suppliers that can consistently deliver advanced substrate and catalyst combinations without sacrificing manufacturability or cost control.
The commercial opportunity here lies in moving the conversation from compliance to performance optimization. Suppliers that can quantify fuel impact, downtime reduction, and maintenance savings will be better positioned to capture premium demand in heavy-duty and off-highway applications where operational continuity is critical.
Retrofit and Aftermarket Demand Stays Resilient
Even as new vehicle emissions technologies advance, large installed bases of older diesel equipment will continue to require compliant retrofits and component replacements. Verification updates for active DPF retrofit systems in non-road and heavy-duty applications confirm that retrofit pathways remain relevant, particularly where fleets aim to extend asset life while maintaining operational eligibility. This creates a durable aftermarket demand stream that is less dependent on new vehicle production cycles.
For manufacturers and service providers, this trend suggests value in building retrofit-ready designs, clear verification alignment, and support models that simplify installation and compliance documentation. The opportunity is not only in selling filters but in helping operators navigate certification requirements and maintain performance over time.
Worldwide DPF (Digital Photo Frame) Market
Regional Divergence Creates Both Complexity and Opportunity
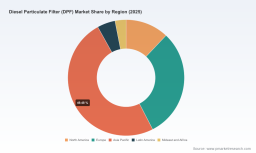
Different regions will continue to move at different speeds in terms of enforcement, certification, and adoption maturity. Mature markets may see more incremental growth driven by replacement demand and higher-performance upgrades, while developing markets may experience stronger volume expansion as emission control adoption broadens. At the same time, cross-border fleet operations and globally sourced equipment create pressure for products that can satisfy multiple regulatory expectations without excessive customization.
This divergence opens the door for regionally tailored strategies. Suppliers that can combine global technology platforms with local certification knowledge, application tuning, and service support will gain an advantage in navigating the gap between global scale and local compliance. The risk, however, is that companies without sufficient regional coordination may face delays, rework, or limited market access when verification requirements diverge more sharply than anticipated.
Actionable Priorities for Decision Makers
Strategic choices in this market should be guided by the intersection of performance expectations, compliance pathways, and total cost of ownership. Different stakeholders will benefit from emphasizing different priorities.
For Manufacturers and System Suppliers
- Prioritize substrate and catalyst development that improves filtration efficiency and thermal stability while managing backpressure and regeneration frequency.
- Align product roadmaps with verification criteria across key jurisdictions to reduce rework and accelerate time to market for new applications.
- Strengthen aftermarket and retrofit support, including documentation, service training, and compatibility guidance, to capture demand from existing fleets.
- Evaluate manufacturing and sourcing strategies for resilience, especially around specialized materials and coating processes that can affect lead times and cost consistency.
For Investors
- Look for companies with credible R&D infrastructure and the ability to move material and catalyst innovations into production efficiently.
- Assess exposure to retrofit and aftermarket demand, which can provide revenue stability independent of new vehicle cycles.
- Consider suppliers that demonstrate application-specific expertise in heavy-duty, off-highway, or marine segments where performance requirements and certification complexity create stronger competitive moats.
- Monitor material cost dynamics and regional regulatory fragmentation as key variables that can influence margins and market access.
For Procurement and Fleet Decision Makers
- Evaluate DPF solutions based on total operating impact rather than sticker price, including regeneration behavior, backpressure, maintenance frequency, and downtime risk.
- Confirm verification status and fuel requirements early in the procurement process to avoid compliance gaps or unexpected operating constraints.
- Consider service and support capability as part of the purchasing decision, especially for fleets operating in demanding duty cycles or across multiple regulatory environments.
- Plan for lifecycle management, including regeneration strategy, filter replacement timing, and compatibility with existing engine calibration and fuel quality.
Closing Perspective
The diesel particulate filter market is entering a period where compliance, performance, and commercial reliability increasingly converge. Growth is expected to continue at a steady pace, but the more important question for decision makers is not simply how large the market will become. It is which suppliers, technologies, and operating strategies will capture the most valuable segments as performance expectations rise and regulatory pathways remain complex. Companies that invest in material and catalyst capability, align closely with verification requirements, and address the practical needs of fleets and operators will be best positioned to turn market expansion into durable competitive advantage. For organizations seeking deeper segmentation data, regional deployment patterns, company-level positioning, and customized go-to-market guidance, the full PW Consulting research report provides the detailed breakdown needed to support more precise strategic planning.
For detailed analysis of this topic, please visit the official page: Diesel Particulate Filter (DPF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


