



LIDAR Market 2026: The 20.32% CAGR Surge and Strategic Shifts Redefining Global Competition

The Lidar Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
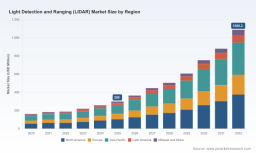
The Light Detection and Ranging market has moved well beyond its experimental phase. From a base of 299.0 million USD in 2025, the sector is projected to reach 1088.2 million USD by 2032, expanding at a compound annual growth rate of 20.32 percent. The trajectory from 2020 through 2025 tells a story of accelerating adoption rather than linear growth. Revenue climbed from 162.3 million USD in 2020 to 219.56 million USD in 2023, then accelerated sharply to 257.35 million USD in 2024 before crossing the 300 million threshold in 2025. That step-change in velocity matters. It signals that lidar is graduating from niche deployments into mainstream integration across mobility, infrastructure, and environmental monitoring.
What makes this growth cycle different from prior technology adoption curves is the breadth of pull. Automotive programs are scaling from prototype fleets to production intent. Mapping and smart infrastructure initiatives are institutionalizing three-dimensional elevation data as a public utility. Defense and industrial applications are demanding higher reliability under constrained form factors. Yet the market is not simply riding a single wave. It is navigating a set of structural tensions that will separate durable operators from those chasing short-term hype.
Wind Lidar Market
For executives evaluating their posture in this space, the question is no longer whether lidar matters. It is how to position for a market that is simultaneously fragmenting by application, consolidating by capability, and being reshaped by policy and supply constraints. The following analysis maps the forces at work, the competitive logics emerging among leading firms, and the strategic moves that will determine who captures value over the next three to five years.
Market Reality and the Core Tensions Defining the Next Phase
From Proof-of-Concept to Production Pressure
The market has cleared the proof-of-concept hurdle. The rapid expansion between 2023 and 2025 reflects programs moving from validation to pilot and early production. That transition is unforgiving. Sensors that work in controlled demonstrations must now survive automotive-grade thermal cycles, vibration profiles, and cost targets that leave little margin for optical complexity or software rework. The same pressure applies to smart infrastructure and environmental monitoring, where instruments must operate continuously across seasons and integrate with legacy data pipelines. The market’s growth is therefore not a simple function of demand; it is a function of how quickly suppliers can convert capability into manufacturable, serviceable, and cost-defensible products.
Operationalizing production at scale introduces a different set of constraints than developing a working sensor. Yield consistency, thermal management, calibration throughput, and software validation all become revenue gates. Companies that treat these as engineering afterthoughts find their growth throttled by quality escapes and program delays. Those that design manufacturability into the architecture early can convert market momentum into booked revenue and, eventually, operating leverage.
The Supply Chain Bottleneck as a Strategic Variable
Hardware scarcity is not a transient procurement issue; it is a structural filter. Shortages of semiconductors, optical lenses, and high-precision MEMS chips have emerged as the primary bottleneck limiting lidar production scale-up. This constraint reshapes commercial logic in several ways. First, it elevates the value of vertical integration and supplier relationships that can guarantee allocation. Second, it forces design teams to make trade-offs between performance, bill-of-materials cost, and component availability that no single engineering discipline can resolve in isolation. Third, it rewards firms that can offer modular architectures, allowing customers to adapt to component substitutions without redesigning entire perception stacks.
The implication for operators is that supply resilience is a competitive capability, not a back-office function. Companies that treat component strategy as a first-class design input can maintain program continuity when others face allocation risk. They can also shape customer conversations around total cost of deployment rather than headline sensor price, which is where durable differentiation often lives.
Regulatory and Standards Divergence as a Market Shape
Policy and standardization activity is no longer a peripheral concern. In December 2025, the SAFE LiDAR Act was introduced in the 119th Congress to restrict the use of foreign adversary lidar in the United States. That legislative direction introduces a geopolitical filter into procurement decisions that previously focused on performance and cost alone. At the same time, regulatory clarity is uneven. A Federal Register notice issued on January 16, 2025 reaffirmed that lidar hardware is excluded from supply-chain review under the Connected Vehicles framework. The coexistence of targeted restrictions and carve-outs creates a compliance environment where buyers must navigate sector-specific rules, origin requirements, and validation expectations that vary by application and geography.
Standards work is compounding this complexity. Hesai is co-leading the Automotive LiDAR Working Group at the International Standards Organization, developing test methods for lidar performance and safety. The latest Lidar Base Specification, LBS 2025 rev. A, was released by the U.S. Geological Survey in June 2025 for the 3D Elevation Program. These developments point to a market where interoperability, testability, and data formatting are becoming gateways to adoption, particularly in government and infrastructure programs. Suppliers that help their customers satisfy these expectations gain a defensible path to recurring engagement.
PW Consulting Information & Electronics Research Center
Key Drivers Shaping the Lidar Market Trajectory
Technology Innovation as a Rewriting of the Form-Factor Equation
The most consequential engineering shift in the market is the re-architecture of lidar around smaller, more integrated, and software-defined systems. Solid-state approaches are gaining share relative to mechanical designs because they reduce moving parts, improve robustness, and simplify packaging. The split between mechanical and solid-state revenue in 2025 reflects this migration, with solid-state reaching meaningful scale while mechanical platforms maintain a substantial base in applications that still value mature scanning patterns and high dynamic range. The strategic point is not that one architecture wins universally. It is that customers are increasingly selecting platforms based on fit-for-purpose trade-offs among range, resolution, module thickness, and serviceability.
Product introductions in early 2026 illustrate how these trade-offs are being translated into commercial solutions. Hesai introduced the ET25 ultra-thin sensor at 25 millimeters thickness for behind-windshield mounting, alongside the PandarXT 32-channel mid-range lidar with zero minimum range and self-developed ASICs. The behind-windshield form factor matters because it lowers integration friction for automotive programs that want lidar without external housings or prominent bump placements. The zero minimum range and custom silicon point to a broader industry move toward tailored silicon that can optimize power, latency, and cost for specific use cases rather than relying on general-purpose components.
For manufacturers and integrators, the opportunity is to align platform selection with deployment realities rather than laboratory benchmarks. A sensor that excels in open-road long-range detection may be structurally awkward for compact urban vehicles, robotics, or retrofit infrastructure. A sensor optimized for short-to-mid range perception may unlock new placement options and cost envelopes. The winners will be those who can articulate where each architecture adds the most value and how to scale the corresponding supply chain.
Policy, Procurement, and the Rise of Institutional Demand
Government and institutional procurement is becoming a powerful demand engine, and it operates under rules that differ from consumer or commercial automotive buying. The U.S. Geological Survey’s FY25 3DEP Data Collaboration Announcement selected projects including newly acquired QL1 lidar for Palm Beach County to support a new 3DHP pilot project. The relevance extends beyond one county. It reflects a broader institutional embrace of high-quality elevation data as a foundation for planning, resilience, and digital twin infrastructure. When public agencies standardize on lidar-based data collection and release specifications such as LBS 2025 rev. A, they create repeatable procurement patterns that suppliers can design for.
Standards and conferences are reinforcing this institutional pull. The 5th edition of the European Lidar Conference was held in September 2025 in Warsaw, Poland, bringing together research, application, and supplier communities in a forum that accelerates the transfer of methods and expectations across sectors. Conferences of this kind matter commercially because they influence procurement norms, test expectations, and cross-industry best practices. They also create pathways for suppliers to demonstrate capability to informed buyers who increasingly compare offerings across domains.
For firms targeting public-sector and infrastructure work, the strategic task is to treat compliance and data interoperability as product attributes, not paperwork. Certification traceability, metadata discipline, and alignment with agency specifications can shorten sales cycles and reduce integration risk. In markets where procurement rules and data standards are hardening, the suppliers who build for those requirements first gain a structural advantage.
Demand-Side Behavior and the Shift to Scalable Perception
Demand is changing not only in volume but in shape. Automotive and ADAS applications remain the largest application segment in 2025, and the growth trend indicates that perception is moving from safety augmentation toward higher levels of automation where lidar complements camera and radar stacks. At the same time, demand is broadening across robotics, smart cities, industrial automation, and defense. This diversification matters because it changes what customers care about. An automotive program may prioritize long-range performance, safety validation, and cost per unit at volume. A robotics or smart-infrastructure program may prioritize compact volume, continuous operation, digital integration, and total cost of ownership across a deployed network.
MicroVision’s launch of its Global Partner and Reseller Program in April 2026 is a practical example of how suppliers are responding to distributed demand. Rather than relying solely on direct sales, the company is building channels to accelerate adoption of scalable lidar and perception technologies across industrial, defense, and real-world applications. This model reflects a market where reach and application expertise matter as much as sensor capability. Customers often buy through ecosystems that understand their specific operating conditions, and suppliers that enable those ecosystems can expand faster than those that try to cover every segment directly.
The commercial lesson is that lidar value is increasingly realized at the system and deployment level, not just at the component level. Suppliers that can package sensors with perception software, integration support, and channel expertise are better positioned to capture the economics of scale than those selling hardware in isolation.
Cost Structure and the Logic of Targeted Integration
Cost reduction is happening, but not through brute-force commoditization. Lidar pricing is being reshaped by a combination of architectural simplification, custom silicon, and selective integration. Self-developed ASICs, for example, can reduce dependency on generic components and improve performance-per-watt, but they also concentrate design risk and require volume commitment to justify the investment. Behind-windshield mounting and thin form factors reduce vehicle integration cost and design complexity, which can make lidar more palatable for mid-tier programs that would otherwise defer adoption.
The deeper strategic insight is that cost advantage in lidar is increasingly a function of integration intelligence. Customers do not just buy a sensor; they buy a path to a working perception system. The less friction there is in mounting, calibration, software integration, and supply continuity, the lower the effective cost of adoption. Suppliers that reduce these frictions can command more stable demand and better lifecycle economics, even if their headline hardware price is not the lowest in the market.
Competitive Landscape and the Emerging Strategies of Leaders
Positioning Through Form Factor, Range, and Application Fit
The competitive field is characterized by differentiated bets rather than a single race to the top. Hesai Technology, based in Shanghai, is emphasizing solid-state automotive lidar sensors with high-volume production and 3D perception solutions for autonomous mobility and robotics. Its recent manufacturing expansion in Thailand, expected to come online later in 2026 to supply sensors to non-Chinese companies, signals an intent to broaden geographic reach and serve customers outside China directly. This move reflects a strategic logic of diversifying supply footprint while maintaining scale economics in production.
Luminar Technologies, headquartered in Orlando, is focused on long-range pulsed lidar sensors and perception systems for Level 3+ autonomous vehicles and ADAS. Its differentiation is anchored in range and perception depth for higher automation levels, where detecting objects at distance and characterizing them reliably are central value propositions. The strategic implication is that Luminar is playing in a segment where performance credibility and validation rigor matter more than module thickness or price alone. Its customers are likely to be programs where safety case and long-range perception are non-negotiable.
Ouster, based in San Francisco, is building around digital lidar sensors optimized for scalability in autonomous vehicles, robotics, and smart infrastructure. Its emphasis on scalability suggests a platform mindset: design a digital architecture that can be adapted across form factors and applications with minimal rework. That approach is attractive in markets where demand is fragmented and customers want a common technology base that can be configured rather than entirely custom-built.
Worldwide 3D Scanning Wind Lidar Market
Innoviz Technologies, in Rosh Ha’ayin, is concentrating on automotive-grade lidar platforms with high-resolution 3D perception for consumer vehicles and commercial applications. Its positioning targets the intersection of consumer-facing vehicle programs and commercial deployments, where resolution and automotive qualification must coexist with cost discipline. LeddarTech, in Québec, is pursuing a complementary path through solid-state lidar sensors and LeddarVision software for ADAS and autonomous driving perception, emphasizing the software layer that turns raw detections into usable driving decisions. The strategic point is that competition is not only about the hardware envelope; it is also about who can deliver a usable perception pipeline that customers can integrate with confidence.
MicroVision, in Redmond, is advancing MEMS-based lidar 2.0 sensors and perception solutions for industrial, defense, and autonomous applications. Its MEMS foundation positions it for scenarios that demand compact volume, durability, and tailored performance across non-automotive domains. Cepton Technologies, in San Jose, is leaning into lidar-based solutions for automotive ADAS, smart cities, and industrial automation, which suggests a multi-domain strategy that leverages common optical and processing building blocks across sectors.
How the Market Is Evolving: Consolidation Pressure Meets Application Fragmentation
The market structure is best understood as simultaneous consolidation and fragmentation. On the consolidation side, three-firm concentration stands at 35.0 percent and five-firm concentration at 52.0 percent, indicating that a meaningful share of revenue is already concentrated among a set of scaled players. As programs move to production and compliance requirements tighten, there is natural pressure toward fewer, more capable suppliers that can meet automotive-grade, government, or infrastructure expectations. Consolidation is also driven by the cost of maintaining multiple qualified architectures, test suites, and supply relationships.
At the same time, application fragmentation is intensifying. Automotive and ADAS demand is distinct from aerospace and defense, which is distinct from smart infrastructure and mapping, which is distinct from environment and forestry. Each segment has its own performance priorities, procurement rhythms, and validation regimes. This fragmentation creates room for specialized players and channel models, but it also raises the bar for suppliers that must support multiple domains without diluting focus. The most resilient strategies are those that combine a coherent core technology with the ability to configure it for different application requirements.
New entrants will continue to appear, particularly around niche form factors, custom silicon, and vertical software. However, the practical hurdle is not just technical differentiation. It is the ability to survive the transition from excellent prototype to repeatable production while managing component scarcity, qualification cycles, and geography-specific policy constraints. Entrants that underestimate the operational weight of scaling tend to stall after initial interest. Entrants that plan for manufacturability, compliance, and channel reach from the start have a realistic path to carve out defensible positions.
Forward Trends and the Commercial Opportunities They Create
Trend One: Standardization and Compliance Will Become Purchase Criteria
Over the next three to five years, lidar purchasing will increasingly be shaped by testability, safety validation, data formatting, and geopolitical compliance. The SAFE LiDAR Act trajectory, ongoing ISO working group activity, and USGS data specifications all point toward an environment where buyers compare offerings not only on performance but on traceability and conformity. Suppliers that can document test methods, align with recognized specifications, and simplify compliance for customers will reduce friction in the sales process and gain preference in regulated programs.
The commercial opportunity here is to treat standards readiness as a product capability. Firms that publish clear performance methodologies, support agency data specifications, and offer origin and sourcing clarity can differentiate in segments where procurement teams are under pressure to demonstrate due diligence. This is especially relevant for infrastructure, mapping, and government-adjacent applications, where data quality and program continuity are valued alongside sensor specifications.
Trend Two: Scale Will Favor Modular, Software-Enabled Architectures
The next growth phase will reward architectures that scale across applications without requiring full redesign. Modular sensor platforms, configurable channel counts, and perception software that can be tuned to different operating conditions will be more valuable than highly specialized one-off designs. This is because demand is spreading across automotive, robotics, smart infrastructure, and defense, and customers in each segment want a credible base platform that can be adapted efficiently.
For suppliers, the opportunity is to build a technology core that can be reused while differentiating through integration, software, and channel support. For customers, the opportunity is to select platforms that reduce long-term integration risk and enable incremental expansion. The strategic risk is over-customization: tailoring too narrowly to a single program or geography can leave suppliers exposed if that program slips, the policy environment changes, or component allocations shift.
Trend Three: Geographic Realignment and Supply Footprint Strategy
Lidar is likely to become more geographically deliberate. Buyers will increasingly weigh origin, local supply continuity, and regulatory exposure when selecting sources. Hesai’s Thailand manufacturing expansion to serve non-Chinese companies is an early signal that suppliers are building regionally balanced footprints to meet customer demands for proximity, allocation security, and compliance comfort. This does not mean every supplier must build everywhere. It does mean that footprint strategy will matter more explicitly in winning programs that span multiple markets.
The opportunity is for suppliers to design supply footprints that match the geography of their strongest demand and the expectations of their most demanding customers. The risk is to assume a single manufacturing base can satisfy all customers indefinitely, especially as policy and procurement preferences become more varied. Firms that can demonstrate credible regional options without fracturing their engineering core will have an advantage in multi-market deployments.
Strategic Moves for Decision-Makers
For Lidar and Component Manufacturers
Design for manufacturability and supply resilience as core capabilities, not secondary concerns. Treat custom silicon, modular architecture, and thermal and calibration throughput as revenue enablers. Build compliance and standards alignment into the product narrative early, especially if you intend to serve automotive, government, or infrastructure programs. Consider geographic supply options that reflect where your customers face the most procurement and continuity pressure, and ensure that any expansion does not dilute engineering focus.
For Investors
Evaluate companies on the basis of production readiness, channel strategy, and standards posture in addition to sensor performance. The market is moving toward repeatable deployment, which means yield, allocation, software integration, and compliance capability will increasingly determine who scales. Assess whether a company’s differentiation is durable across multiple applications or dependent on a single program narrative. Pay attention to the interplay between architectural bets and supply-chain exposure, because component scarcity and regulatory filters can change the economics of a strategy quickly.
For Procurement and Integration Leaders
Choose lidar platforms based on total deployment fit rather than peak performance in a narrow test. Prioritize architectures that match your mounting constraints, data formatting needs, and validation expectations, and that can be supported by credible channels or integration partners. For public-sector and infrastructure work, confirm alignment with current data specifications and procurement expectations before committing to a supplier relationship. For automotive and ADAS programs, weigh long-range perception requirements against integration complexity and cost trajectory, recognizing that the best sensor on a bench is not always the best sensor in a production vehicle.
A market growing at this pace will not leave much room for passive positioning. The firms and buyers that succeed will be those who treat lidar as a systems challenge, plan for manufacturability and compliance as first-class concerns, and select architectures that can adapt as applications and policies evolve. For decision-makers who need granular segmentation, supplier-by-supplier capability mapping, and scenario-based guidance tailored to a specific product plan or investment thesis, the full PW Consulting report provides the detailed breakdown and customized recommendations that underpin these strategic conclusions.
For detailed analysis of this topic, please visit the official page: Light Detection and Ranging (LIDAR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


