



Ultra Fine Aluminium Hydroxide Market: Why 6.5% CAGR Bets on Flame Retardant Demand

The Strategic Shift: Navigating the Ultra Fine Aluminium Hydroxide Market Through 2032
The global market for ultra fine aluminium hydroxide has reached a critical inflection point. With a projected market value approaching 407.5 million USD by 2032 and a compound annual growth rate of 6.5 percent over the forecast period, the industry is transitioning from a mature specialty chemicals segment into a strategically vital enabler of next-generation materials safety, energy storage, and polymer performance. Between 2020 and 2025, the market expanded from 212.0 million USD to 278.8 million USD, reflecting steady underlying demand that has now accelerated into a multi-year growth trajectory. This expansion is not uniform across all value drivers; it is being reshaped by regulatory urgency, technological refinement in particle engineering, and a supply base that is simultaneously consolidating and regionalizing. For executives, investors, and procurement leaders, understanding the structural forces behind this trajectory is essential to positioning portfolios, pricing strategies, and long-term sourcing commitments.
Mapping the Market Trajectory
The revenue curve across 2020 through 2032 reveals a market that has moved past cyclical volatility and is now anchored by structural demand shifts. Growth from 2023 to 2025 alone added roughly 33.6 million USD in incremental revenue, signaling that end-use adoption is no longer limited to legacy flame retardant applications. The forecast period through 2032 projects continued expansion, with the steepest absolute gains expected between 2028 and 2032, when annual revenue additions will be driven by manufacturing scale-up, cross-sector substitution, and the commercialization of ultra-fine grades in higher-value performance matrices. This trajectory suggests that the market is entering a phase where capacity investments, rather than short-term pricing cycles, will define competitive positioning.
Concentration Dynamics and Strategic Implications
Market concentration remains a defining characteristic of the industry. The top three participants collectively command approximately 65 percent of revenue, while the top five account for around 82 percent. This concentration does not indicate a stagnant oligopoly; rather, it reflects a landscape where incumbents have built deep technical credibility in particle size control, surface treatment, and application-specific formulation support. Yet concentration also masks underlying fragmentation in sub-segments, particularly where regional producers are closing the quality gap and capturing localized demand without competing directly on global scale. The implication for buyers is a dual-layer marketplace: global specialists offer consistency, technical service, and regulatory documentation, while regional facilities increasingly provide cost-competitive access for standard-grade requirements.
Ultra Fine Copper Powder Market
Current Structural Challenges
Three interlocking challenges are forcing the industry to recalibrate its operating assumptions. First, the physical and regulatory constraints around transporting fine powdered chemicals are raising logistics costs. Containment protocols for powdered material have increased per-ton transport expenses by an average of 18 percent, compressing trade flexibility and making proximity to end-use clusters a more decisive competitive factor. Second, raw material inputs are undergoing both volume and price shifts. Bauxite consumption estimates for 2025 reached approximately 1.7 million tons, a 4 percent increase over the prior year, while the landed value of imported crude dry bauxite and metallurgical-grade alumina for U.S. consumption rose by 4 percent and 9 percent respectively in the first eight months of 2025 compared with the same period in 2024. Even with absolute dollar values in the tens of millions, these movements signal tightening upstream economics that will eventually transmit into ultra-fine production margins. Third, the demand environment is shifting from generic filler substitution toward specification-driven performance requirements. Buyers are no longer purchasing by bulk weight alone; they are demanding tight particle size distributions, consistent surface reactivity, and documented safety performance, which raises the barrier to entry for undifferentiated capacity.
PW Consulting
Key Drivers Reshaping the Landscape
Regulatory Substitution as a Demand Anchor
The most durable demand catalyst is the regulatory displacement of halogenated flame retardants. As of 2023, more than 53 countries had enforced restrictions on halogenated formulations, creating a structural pull toward halogen-free alternatives in sectors where safety certification, lifecycle compliance, and public acceptance are non-negotiable. Public transport, building interiors, and consumer electronics have become priority adoption zones, where ultra fine aluminium hydroxide serves not merely as a filler but as an active smoke suppressant and intumescent co-agent. This regulatory environment transforms the product from a commodity additive into a compliance-critical input, lengthening qualification cycles but also increasing switching costs once a grade is approved. The commercial consequence is a demand base that grows through specification lock-in rather than spot purchasing, rewarding suppliers who can support audit-ready documentation, consistent lot-to-lot performance, and application engineering.
Particle Engineering and Performance Differentiation
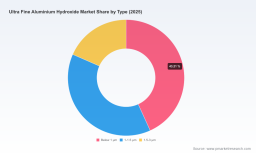
Technological progress in precipitation control, micronization, and surface modification is redefining what buyers consider a premium grade. The market now segments around particle size thresholds that directly influence dispersion quality, polymer clarity, rheological behavior, and flame retardant efficiency. Below-1-micron grades are increasingly favored where투명성, low haze, and high surface area reactivity are required, while 1-to-1.5-micron ranges remain strong in applications balancing reinforcement and processability. The competitive advantage has shifted from volume production alone to the ability to hold narrow size distributions at scale, manage agglomeration, and tailor surface chemistry for specific resin systems. Facilities investing in automated micronization and closed-loop precipitation are reporting meaningful capacity leverage; certain producers have expanded sub-1.5-micron output with double-digit percentage capacity increases to serve coatings, paints, and flame retardant blends. This technical layer raises the value of process IP and operational discipline, making consistent quality a more powerful moat than route selection alone.
Downstream Demand Shifts Toward Safety and Energy Applications
Demand-side behavior is moving beyond traditional polymer compounding toward applications where thermal safety, electrical insulation, and weight efficiency intersect. Automotive interiors and component housings are increasingly specified with halogen-free systems to align with regional safety expectations and OEM sustainability targets. Electronics enclosures and battery-adjacent components are driving interest in grades that combine filler functionality with smoke reduction and thermal stability. At the same time, higher-purity ultra-fine grades are finding roles in advanced ceramics and technical coatings, where trace impurities and particle morphology directly affect final performance. These shifts expand the addressable market beyond volume-driven filler substitution and create pricing resilience for grades that are certified and engineered for specific end-use environments.
Cost Structure and Upstream Realities
The cost equation is being reshaped on two fronts. On the raw material side, the reported increase in bauxite consumption and the higher import benchmarks for alumina point to an environment where input economics are less predictable than in prior years. Even when absolute commodity values remain modest, percentage movements in traded benchmarks affect planning assumptions for integrated and non-integrated producers alike. On the operating side, the logistics cost premium for powdered chemical transport is now a structural component of delivered pricing, especially for long-haul movements across regulatory jurisdictions. This dynamic is pushing regionalization of supply, localized blending and packaging, and greater emphasis on total landed cost rather than ex-works price. Manufacturers that can align capacity with demand clusters, or that offer stable formulation support to reduce re-qualification, are better positioned to manage these cost layers than suppliers competing solely on headline pricing.
Competitive Landscape and Strategic Positioning
Differentiated Advantage Among Leading Participants
The competitive field shows a clear divide between global specialists with deep application portfolios and regional operators focused on scale and cost efficiency. German and U.S. headquartered producers have built recognition around sub-micron particle engineering, flame-retardant efficacy, and smoke suppression in polymers and coatings. Their portfolios emphasize grades optimized for specific resin systems and regulatory environments, supported by technical service and consistent documentation. Japanese manufacturers have extended their relevance through high-performance polymer compatibility and water-based system formulations, where dispersion stability and purity profiles matter. Another German specialist has carved a distinct position in high-purity grades for advanced ceramics and technical applications, trading volume for specification precision. On the regional side, Chinese producers have been expanding automated micronization capacity and targeting paints, coatings, rubber, and plastics grades with sub-1.5-micron outputs and higher content formulations. A U.S. diversified chemical company has signaled a broader push into ultra-fine grades for automotive and electronics, paired with announced capacity expansion to meet rising demand in automotive, electronics, and energy storage sectors. Together, these participants illustrate a market where differentiation comes from either application engineering, purity control, or regional cost positioning.
Recent Moves That Signal Strategic Intent
Recent corporate activity clarifies how incumbents are shaping the next phase of competition. One major diversified producer announced a significant expansion of ultra-fine production facilities to meet rising demand across automotive, electronics, and energy storage applications, indicating a bet that downstream specification requirements will sustain volume growth beyond legacy uses. Around the same period, another leading manufacturer acquired assets tied to ultra-fine grades to strengthen its flame retardant and smoke suppressant portfolio, consolidating technical capability and market access in a segment where qualification inertia favors integrated offerings. These moves point to two converging strategies: capacity build-out where demand visibility is strong, and portfolio consolidation where application breadth and regulatory support create stickier customer relationships.
Market Evolution: Consolidation, Regionalization, and Selective Entry
The market structure is evolving along three vectors. Consolidation is occurring where scale, technical documentation, and global service networks create advantages in qualification-heavy end markets. Regionalization is accelerating as logistics costs and proximity requirements reward suppliers located near major polymer, coatings, and automotive clusters. Selective entry remains possible, but the barrier is rising: new capacity must demonstrate particle size control, surface consistency, and application support rather than competing purely on throughput. The likely outcome is a layered competitive map. Global specialists retain leadership in high-specification, certification-sensitive applications. Regional producers gain share in standard and semi-specification grades where logistics and price sensitivity dominate. In between, a small set of agile operators capture opportunities by offering targeted grades for coatings, rubber, and plastics with reliable consistency and responsive service. For buyers, this means the optimal sourcing strategy is increasingly hybrid, balancing specification assurance with regional cost dynamics.
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend One: Specification-Led Demand as the Growth Engine
The next growth cycle will be defined less by raw volume expansion than by specification adoption across new end-use environments. As safety regulations continue to favor halogen-free systems and as OEMs embed thermal and smoke performance requirements deeper into component design, ultra fine aluminium hydroxide will move from a supporting additive to a defined performance parameter in material specifications. The commercial opportunity lies in grades that can be pre-qualified for multiple resin systems and that carry documented performance data across smoke suppression, thermal stability, and dispersion behavior. Suppliers that invest in application test matrices, regulatory dossiers, and customer co-development will capture longer qualification cycles and lower churn, translating into more stable revenue streams even as input costs fluctuate.
High Purity Boehmite Market
Trend Two: Capacity Realignment Around Demand Clusters
Production geography will increasingly align with demand concentration. The logistics cost premium for powdered transport makes long-distance shipments less attractive for price-sensitive grades, encouraging regional capacity, localized packaging, and regional blending operations. At the same time, higher-specification grades will remain globally traded where technical service and certification support justify the logistics burden. This bifurcation suggests that the market will develop distinct regional price equilibria, with nominal premiums for proximity and service, and narrower spreads for commodity-style grades where logistics and input volatility dominate. Investors and manufacturers evaluating expansion should prioritize demand adjacency, regulatory documentation capability, and the ability to serve multiple downstream formats over pure scale alone.
Trend Three: Purity, Morphology, and Cross-Sector Portability
A third trend is the growing relevance of purity and particle morphology across sectors that historically had limited overlap. High-purity ultra-fine grades are gaining traction in technical coatings and advanced ceramics, while consistent sub-micron distributions are becoming valuable in electronics-adjacent applications where dispersion and surface effects influence final properties. The opportunity is portability: grades engineered with controlled impurity profiles and repeatable morphology can be positioned across multiple segments, reducing the need for highly fragmented product lines. The risk is that purity and morphology targets are demanding and unforgiving, requiring disciplined process control and analytical support. Producers that treat these attributes as core capabilities, rather than niche features, will be better positioned to defend margins when volume growth moderates in any single segment.
Implications and Actions for Decision Makers
For Manufacturers and Material Formulation Teams
Lead with specification support and total cost management rather than volume pricing alone. As logistics costs and input benchmarks become more variable, competitiveness will depend on demonstrating consistent particle performance, reducing re-qualification friction, and aligning capacity with regional demand clusters. Invest in application data that connects particle size, surface behavior, and dispersion outcomes to end-use safety and processing metrics. Where possible, structure supply relationships to include documentation readiness and lot traceability, since these attributes increasingly influence retention in certified programs.
For Investors and Portfolio Strategists
Prioritize assets and operators that combine process control with application-facing capability. Capacity expansion is meaningful only when it is matched to demand visibility in safety-driven and performance-driven segments. Look for evidence of technological discipline in micronization and precipitation, stable customer relationships supported by technical service, and exposure to multiple downstream formats that reduce dependence on any single cycle. Regional cost advantages are valuable, but they are most durable when paired with consistent quality and the ability to serve specification-led demand without heavy re-qualification overhead.
For Procurement and Sourcing Leaders
Move from transactional price comparison to a total landed cost and qualification-cost framework. The logistics premium for powdered transport, the variability in upstream benchmarks, and the hidden cost of re-qualification all argue for a sourcing model that balances specification assurance with regional availability. Where standard grades are sufficient, regional suppliers can improve cost predictability; where certification and performance consistency matter, global specialists with documented application support reduce downstream risk. Build flexibility into contracts to accommodate input and logistics shifts without triggering costly requalification cycles.
Closing Perspective
The ultra fine aluminium hydroxide market is entering a period where technical consistency, regulatory alignment, and regional supply logic will matter more than headline volume alone. Growth through 2032 is anchored by halogen-free substitution, specification-driven adoption, and expanding relevance in automotive, electronics, and technical coatings, while cost realities in logistics and raw materials are reshaping where and how capacity is most effective. For organizations operating in or adjacent to this market, the strategic question is no longer whether demand will grow, but how to position grades, supply relationships, and portfolio exposure to capture value from specification lock-in and regional demand clustering. Detailed segmentation data, regional demand breakdowns, and customized scenario modeling can sharpen these decisions further, and PW Consulting’s full research report provides the granular visibility required to translate these trends into concrete sourcing, investment, and product strategy choices.
For detailed analysis of this topic, please visit the official page: Ultra Fine Aluminium Hydroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


