



Hexanoic Acid Market: How a 6.5% CAGR Trajectory and Fragmented Supply Chain Redefine Growth

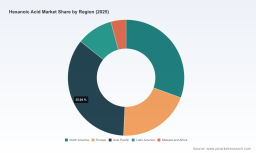
Strategic Trends and Commercial Opportunities in the Hexanoic Acid Market
The hexanoic acid market is navigating a phase of steady expansion amid shifting regulatory expectations and evolving supply chain priorities. Valued at 255.0 million USD in 2025, the market has grown from 200.0 million USD in 2020, reflecting a compound annual growth rate of approximately 6.5 percent through the forecast period extending to 2032. Projections indicate revenue will reach 396.32 million USD by the end of the forecast horizon, with 2031 and 2032 marking particularly notable steps upward. This trajectory signals more than incremental growth; it reflects structural changes in how manufacturers source feedstocks, design formulations, and align production with regional compliance frameworks.
Yet the expansion path is not uniformly smooth. Three cross-cutting challenges define the current inflection point. First, feedstock dependency on palm kernel oil and coconut oil creates cost volatility that directly pressures operating margins, given that these raw materials typically account for a substantial share of total production expenses. Second, regulatory divergence across key markets is reshaping purity expectations and documentation requirements, which in turn influences which product grades can be commercialized where. Third, capacity and specification alignment are becoming strategic differentiators as downstream industries demand more consistent quality for pharmaceutical, food, and personal care applications. These factors collectively separate suppliers that treat hexanoic acid as a commodity from those that position it as a specification-driven specialty chemical.
For executives and investors, the implication is straightforward: top-line growth is real, but margin resilience and market access will be determined by how well organizations manage feedstock exposure, regulatory compliance, and application-specific quality requirements.
Key Drivers Reshaping Market Dynamics
Feedstock Economics and Cost Structure Sensitivity
The production of hexanoic acid remains closely tied to bio-derived feedstocks, particularly palm kernel oil and coconut oil. This linkage is not merely a sourcing preference; it is a structural cost driver that shapes pricing behavior, regional competitiveness, and margin sensitivity. When feedstock prices move, operating expenses follow quickly, which explains why price adjustments in oxo-chemical portfolios often coincide with broader raw material cycles. The sensitivity is especially pronounced for manufacturers that rely heavily on these oil-based inputs without diversified supply options or hedging mechanisms.
The commercial consequence is twofold. Suppliers that can secure stable feedstock access, negotiate long-term contracts, or incorporate regional sourcing flexibility gain a meaningful cost advantage. At the same time, downstream buyers are increasingly attentive to origin documentation and purity certification, particularly when sourcing for food-grade or pharmaceutical-grade applications. This creates a dual pressure: cost management must be paired with traceability and specification integrity. In practice, the manufacturers most likely to sustain margins are those that treat feedstock procurement as a strategic function rather than a transactional purchase.
Regulatory Frameworks and Purity Differentiation
Regulatory conditions are actively influencing which grades of hexanoic acid gain traction in specific markets. In Europe, stringent REACH and CLP requirements have encouraged broader adoption of higher-purity grades, reinforcing a market environment where specification consistency is a competitive asset. This regulatory backdrop does not simply raise compliance costs; it redirects demand toward products that can demonstrate reliable purity profiles and robust documentation. For European customers, the choice of supplier is increasingly tied to the ability to meet these expectations without supply disruption.
Meanwhile, in the United States, hexanoic acid holds GRAS designation under FDA 21 CFR 172.515 for use as a flavoring agent and adjuvant, which supports its continued presence in food and beverage formulations. In parallel, EU Regulation 1334/2008 recognizes hexanoic acid as a flavoring agent with approved Codex Alimentarius standards, further reinforcing its role in flavor and fragrance applications. These regulatory anchors provide market stability, but they also raise the bar for suppliers that must maintain compliance across multiple jurisdictions. Bio-based variants derived from palm kernel oil have also gained food-grade certifications and are shipped to EU markets under strict purity and origin documentation requirements. The net effect is a market where regulatory acceptance supports demand, but regulatory complexity rewards suppliers with strong quality systems and transparent supply chains.
Application-Side Demand and Formulation Preferences
Demand for hexanoic acid is not growing uniformly across end-use segments. Food and beverage applications continue to represent a significant share of market activity, supported by the compound's role in flavor profiles and its regulatory acceptance in key jurisdictions. Personal care formulations also contribute meaningfully, where the acid's functional properties and compatibility with specialty product development make it relevant for niche but value-conscious applications. Pharmaceutical use cases further reinforce demand for higher-purity grades, particularly where consistency and documentation are non-negotiable. Industrial chemical applications add additional volume, though they often emphasize cost efficiency and broader specification tolerances.
What matters for strategy is the direction of travel within these segments. In food and personal care, buyers increasingly favor suppliers that can provide stable purity, reliable availability, and clear origin documentation. In pharmaceutical and premium applications, the emphasis shifts toward specification control and audit-ready supply chains. This divergence is creating a market in which application-specific value propositions matter more than generic volume positioning. Companies that align their product grades, technical support, and compliance documentation with the expectations of specific end-use sectors are better placed to capture premium demand and reduce exposure to price-based competition.
Supply Chain Reconfiguration and Regional Capacity Responses
Supply chain dynamics are increasingly shaped by localized capacity decisions and regional sourcing strategies. Recent announcements indicate that some producers are expanding specialty carboxylic acid capacity in locations designed to serve pharmaceutical and premium personal care segments more directly. Such moves reflect a broader industry trend: rather than treating hexanoic acid as a globally interchangeable bulk chemical, suppliers are building or adjusting capacity to better match application requirements, reduce lead-time risk, and strengthen regional service levels.
At the same time, price actions across oxo-chemical portfolios have underscored the importance of cost-feedstock alignment. When producers implement price increases for derivatives and related products, downstream customers reassess sourcing alternatives, inventory strategies, and specification trade-offs. This environment favors suppliers that can justify pricing through consistent quality, regulatory readiness, and reliable delivery, rather than competing purely on cost. For buyers, the practical response is to evaluate total cost of ownership, including compliance risk, specification fit, and supply continuity, instead of focusing narrowly on unit price.
Competitive Landscape and Leadership Strategies
Differentiated Positioning Among Leading Suppliers
The competitive field includes a mix of integrated chemical producers, oxo-chemical specialists, and oleochemical manufacturers. Perstorp Holding AB stands out as a leading producer of oxo-chemicals and specialty carboxylic acids, with hexanoic acid serving pharmaceutical, food, personal care, and industrial applications. Its profile suggests a strategy centered on specialty positioning rather than commodity volume, reinforced by recent capacity expansion targeting pharmaceutical and premium personal care segments, as well as periodic price adjustments across oxo-chemical portfolios. This combination indicates a focus on margin quality, specification control, and application-aligned service.
Eastman Chemical Company operates as a major manufacturer of carboxylic acids and oxo derivatives, with hexanoic acid included in its food additives, flavors, and industrial uses portfolio. Its scale and application breadth provide a broad market reach, which can be advantageous where customers value integrated supply and multi-segment capability. OXEA GmbH specializes in oxo-chemicals and produces n-hexanoic acid for European industrial chemicals, food ingredients, and pharmaceutical-grade markets. Its European orientation and grade-specific focus align well with regional regulatory expectations and purity demands.
BASF SE contributes through an integrated production approach, supplying hexanoic acid and caproic acid via its Verbund network for flavor esters, polyamides, and other chemical applications. That integrated structure can support cost efficiency and supply reliability for customers embedded in broader chemical value chains. Tokyo Chemical Industry Co., Ltd. serves research, flavor, and fragrance markets with high-purity organic chemicals, positioning itself where specification precision and product variety matter more than bulk volume. In the oleochemical segment, KLK OLEO and IOI OLEO produce palm kernel-derived caproic acid and hexanoic acid for food-grade, cosmetic, and lubricant applications, highlighting the importance of bio-based feedstock expertise and food-grade certification pathways.
Strategic Themes Across the Competitive Set
Several strategic patterns emerge when these players are viewed together. One is the tension between scale and specialization. Larger integrated producers can leverage broad networks and multi-product portfolios, while specialists can compete by offering grade precision, regional compliance readiness, and targeted application support. Another theme is the growing importance of documentation and certification. In markets where purity expectations and origin requirements are rising, suppliers with established quality systems and clear traceability gain an advantage in securing premium segments. A third theme is capacity alignment. Recent expansion moves suggest that producers are investing where demand is expected to be most specification-sensitive, especially in pharmaceutical and premium personal care applications.
The market is not necessarily moving toward full consolidation. Instead, it appears to be reorganizing around differentiated value propositions. Some customers will continue to prioritize broad availability and price competitiveness, while others will pay for consistency, certification, and technical support. This creates room for multiple business models to coexist, provided each is clearly aligned with a defined customer base and application profile.
Forward-Looking Trends and Strategic Risks
Trend One: Purity and Specification as Commercial Currency
Over the next three to five years, higher-purity grades are likely to capture disproportionate attention in markets where regulatory expectations and downstream formulation requirements are most demanding. The trend is already visible in European markets, where strict regulatory frameworks have strengthened adoption of 0.99 purity grades. As pharmaceutical and personal care formulations become more exacting, specification reliability will increasingly influence supplier selection. For commercial strategy, this suggests that investments in quality control, analytical consistency, and documentation rigor can translate directly into market access and pricing resilience.
Trend Two: Feedstock-Linked Cost Cycles Will Keep Shaping Pricing Power
Because production depends heavily on palm kernel oil and coconut oil, the market will remain sensitive to feedstock cost cycles. This does not mean prices will move in lockstep with raw materials at all times, but it does mean that margin management will continue to hinge on procurement strategy, product mix, and the ability to pass through cost changes with credible value justification. Suppliers with diversified sourcing options or stronger application-based differentiation are better positioned to manage these cycles. Buyers, in turn, will need to balance cost optimization against supply continuity and specification security.
Isononanoic Acid Market
Trend Three: Regional Compliance Will Drive Sourcing Configuration
As regulatory and documentation requirements diverge across regions, sourcing configurations are likely to become more regionally attuned. Food-grade certifications, origin documentation, and purity standards can determine whether a product is acceptable in a given market. This favors suppliers that can provide market-specific assurance and buyers that avoid over-reliance on a single supply route for specification-sensitive applications. The commercial opportunity lies in matching supply to regulatory context, rather than assuming global interchangeability.
Risks and Uncertainties
Several risks merit attention. Feedstock price volatility can compress margins quickly if not managed through contract structure, product mix, or pass-through mechanisms. Regulatory shifts, while currently supportive in many respects, could raise compliance burdens or change documentation expectations, especially for cross-border trade. Competition from alternative ingredients or substitute formulation approaches may pressure demand in particular applications, especially where cost sensitivity is high. Finally, capacity expansions that are well-aligned with premium segments may still face execution risk if demand timing, feedstock availability, or regional acceptance does not evolve as expected.
Actionable Guidance for Decision Makers
For Manufacturers and Producers
Position product portfolios around specification differentiation rather than volume alone. Higher-purity grades, robust documentation, and application-specific technical support can support stronger margin profiles, especially in pharmaceutical and premium personal care segments. Feedstock strategy should be treated as a core competitive lever, with emphasis on supply continuity, cost visibility, and flexibility across oil-based inputs. Where possible, align capacity and service models with the regions and applications most likely to value consistency and compliance.
PW Consulting
For Investors and Strategic Planners
Evaluate exposure to feedstock-linked cost cycles when assessing business models in this market. Companies with strong specialty positioning, clear regulatory readiness, and the ability to serve specification-sensitive segments may offer more resilient value creation paths than pure volume players. When comparing opportunities, consider how well a company's product grades, certifications, and regional reach match the markets where purity and documentation requirements are tightening. Also monitor capacity announcements and price actions as indicators of where suppliers expect margin and demand to be strongest.
2-Ethylhexanoic Acid Market
For Procurement and Sourcing Leaders
Expand evaluation criteria beyond unit price. Total cost of ownership should include purity consistency, regulatory documentation, origin traceability, and delivery reliability, especially for food, pharmaceutical, and personal care applications. Diversifying sourcing options can reduce exposure to feedstock-driven price swings and regional compliance interruptions. Where formulations allow, establish clear specification thresholds and audit expectations so that suppliers understand the quality and compliance standards required for ongoing supply.
The hexanoic acid market is entering a period in which growth is increasingly tied to how well participants manage feedstock economics, regulatory expectations, and application-specific specification demands. Organizations that can combine cost discipline with quality assurance and regional compliance readiness are best positioned to convert market expansion into durable commercial advantage.
Detailed segmentation data, company-level estimates, and region-specific demand profiles can help refine these strategic choices further. For decision makers seeking deeper granularity on grade-level dynamics, application trends, and competitive positioning across key markets, PW Consulting's full research report provides the additional detail needed to support tailored planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Hexanoic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


