



Liquid Biopsy Products Market: Why 14.85% CAGR and NGS Shift Rules Everything

The Liquid Biopsy Products Market: Strategic Trends and Commercial Opportunities in a Rapidly Maturing Landscape
The liquid biopsy products market has transitioned from a promising diagnostic niche to a central pillar of modern oncology and precision medicine. Valued at approximately $3.3 billion in 2025, the market has expanded at a compound annual growth rate of 14.85% through 2032, reaching an estimated $8.6 billion by the end of the forecast period. This trajectory reflects more than incremental adoption; it signals a structural shift in how clinicians detect, monitor, and select therapies for cancer and other complex diseases. The commercial environment is no longer defined by proof-of-concept studies and pilot programs. Instead, it is shaped by regulatory momentum, platform consolidation, and a growing expectation that blood-based molecular testing will integrate seamlessly into routine care pathways.
Despite the clear growth trajectory, the market sits at a critical inflection point. Early-stage enthusiasm has given way to operational realities, reimbursement negotiations, and the need to demonstrate consistent clinical utility across diverse patient populations. Companies that navigate this phase successfully will be those that can balance technological ambition with commercial discipline, transforming scientific capability into reproducible, scalable, and economically viable offerings.
Market Snapshot: Scale, Structure, and the Cost of Momentum
The market’s expansion has been broad-based, but growth is not uniform across product categories or end-use needs. Kits and reagents continue to represent the dominant revenue share, reflecting the recurring demand for consumable-based workflows that support circulating tumor DNA and other biomarker analyses. Instruments, while smaller in absolute terms, remain strategically important as enabling platforms that anchor laboratory workflows and create binding relationships with downstream testing ecosystems.
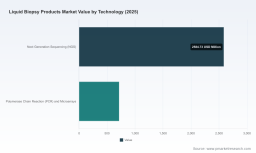
Technology-wise, next-generation sequencing has established itself as the leading modality, driven by its ability to capture broader mutational landscapes and support increasingly complex clinical questions. PCR-based approaches and microarray platforms continue to command a meaningful share, particularly where speed, cost constraints, or targeted detection priorities favor simpler workflows. This dual-technology structure matters commercially because it creates parallel adoption curves: NGS-led environments tend to favor higher-content, information-rich applications, while PCR-oriented settings often prioritize throughput, turnaround time, and incremental integration into existing diagnostic routines.
From a concentration standpoint, the market remains moderately consolidated. The top three participants account for roughly 55% of total revenue, and the top five hold about 62%. That level of concentration suggests an industry where scale, regulatory maturity, installed-base advantage, and multi-product ecosystems increasingly separate leaders from followers. At the same time, it leaves room for specialized entrants and platform-oriented innovators that can compete on workflow efficiency, bioinformatics, or distinctive clinical claims rather than broad brand recognition alone.
Key Challenges and Turning Points
The most pressing challenge is no longer technical feasibility; it is clinical and economic validation at scale. Liquid biopsy products must increasingly prove that they improve decision-making, reduce unnecessary procedures, support faster treatment adjustments, or enable earlier intervention in ways that payers and health systems are willing to reward. Without that proof, adoption can stall even when the underlying science is strong.
A second challenge lies in standardization and workflow fragmentation. Different sample types, extraction methods, sequencing depths, bioinformatic pipelines, and reporting formats can complicate comparability across sites and studies. For purchasers and laboratory operators, this variability raises integration risk and can slow procurement decisions. For manufacturers, it creates a strategic choice: compete on proprietary performance or invest in interoperable, easier-to-adopt solutions that reduce friction for the customer.
PW Consulting
A third turning point is regulatory and reimbursement maturation. As more assays move toward formal approval pathways and as payers become more selective, the market is shifting from broad experimentation toward a smaller set of well-supported indications and claims. That transition can compress early uncontested opportunities, but it also rewards companies with durable clinical evidence packages and clear value narratives.
Core Growth Drivers: Why the Market Is Accelerating
Several structural forces underpin the current expansion, and they reinforce one another rather than acting in isolation.
Technology Innovation and Platform Convergence
Liquid biopsy development is increasingly defined by platform convergence rather than standalone assay novelty. Companies are building workflows that combine sample preparation, detection chemistry, sequencing or amplification, and interpretation layers into more complete solutions. This matters because end users value not only accuracy, but also operational simplicity, reproducible reporting, and the ability to scale across multiple clinical questions.
Recent product launches illustrate this shift toward richer, more actionable information. For example, new add-on applications for liquid biopsy platforms have extended beyond foundational mutation detection to include pharmacokinetic insights and clonal hematopoiesis analysis, enhancing therapy selection and differential interpretation. These developments signal a move from single-purpose detection toward multi-dimensional profiling that can better inform treatment decisions and reduce ambiguity in result interpretation.
Regulatory Activity and the Push for Formal Validation
Regulatory momentum is reshaping the competitive landscape. As developers advance premarket submissions for high-impact multi-cancer and targeted oncology tests, the market is moving closer to a environment where approved claims, standardized evidence expectations, and clearer regulatory status become differentiators. A recent major regulatory submission for a multi-cancer early detection test marks an important step in that direction, reinforcing the idea that the most visible commercial opportunities will increasingly belong to products with credible regulatory traction and well-defined intended use.
This dynamic has strategic implications. Regulatory progress can unlock broader adoption, but it also raises the bar for evidence generation, quality systems, and post-market performance monitoring. Companies that treat regulatory alignment as an afterthought risk being outpaced by competitors who design their development programs around approval requirements from the outset.
Demand-Side Shifts in Oncology and Beyond
The demand environment is changing on multiple fronts. In oncology, there is growing interest in using liquid biopsy not only for advanced disease monitoring, but also for earlier detection, therapy selection, resistance surveillance, and minimal residual disease assessment. Clinicians and health systems are looking for tools that can reduce invasive procedures, shorten time to actionable results, and support more adaptive treatment strategies.
Outside oncology, non-cancer applications are expanding the addressable market, though from a smaller base. The broader appeal of blood-based molecular testing lies in its potential to provide repeatable, less invasive insights across a range of conditions where longitudinal monitoring or early signal detection offers clinical value. This diversification does not diminish the dominance of cancer-related use cases, but it does suggest that long-term growth may increasingly depend on broadening the clinical narrative beyond a single disease category.
Blood Products Market
Partnerships, Service Models, and Geographic Reach
Commercial models are evolving as well. Rather than relying solely on kit and instrument sales, some organizations are extending into on-site testing services, localized collaborations, and public-private partnerships that bring testing closer to the patient and reduce logistical barriers. A recent expansion of an in-house liquid biopsy service through a partnership with a major clinical institution in Europe illustrates how service-oriented approaches can deepen market penetration, accelerate adoption in specific regions, and create reputational anchoring within established care networks.
For manufacturers and service providers, this trend highlights a broader commercial truth: distribution advantage often comes from reducing friction at the point of care. Where testing can be embedded into existing clinical workflows, supported by local expertise, and aligned with institutional priorities, adoption tends to be more durable than in settings where products must constantly justify themselves as standalone additions.
Competitive Landscape: Strategy, Positioning, and Market Evolution
The competitive field is shaped by a mix of established diagnostics and life sciences players, sequencing specialists, and companies built around particular assay philosophies or software-driven interpretation layers. Rather than competing on a single dimension, leading organizations typically combine technological capability with ecosystem advantages such as installed bases, regulatory positioning, companion workflows, or bioinformatics differentiation.
Differentiated Strategic Positions
Several competitive profiles stand out. Companies focused on comprehensive liquid biopsy testing for cancer detection, monitoring, and therapy selection are positioning around breadth of clinical content and the ability to support complex treatment decisions. Their value proposition often centers on making blood-based testing a practical alternative or complement to tissue-based approaches in specific oncology workflows.
Sequencing-oriented providers contribute a different advantage: scalable platforms that can support circulating tumor DNA analysis across multiple applications and laboratory settings. Their commercial leverage frequently comes from combining instrument ecosystems with compatible reagent and assay portfolios, creating continuity across the workflow.
Large diagnostics and life sciences companies bring breadth across kits, reagents, and instruments, along with established quality systems and global commercial infrastructure. In liquid biopsy, this cantranslate into strong positioning in sample preparation, NGS-enabled workflows, and supporting consumables that anchor laboratory operations.
Other players compete through targeted assay designs, digital PCR capabilities, or software-powered interpretation platforms that emphasize decentralized or AI-assisted diagnostics. These approaches can be especially attractive where speed, accessibility, or standardized analysis are primary concerns.
Market Evolution: Consolidation, Specialization, and New Entrants
The market is likely to continue evolving along two parallel paths. One is consolidation around platforms and multi-product portfolios, where buyers prefer fewer vendors that can address multiple testing needs, simplify procurement, and reduce training burden. The other is continued specialization, where focused companies compete by solving narrow but high-value problems exceptionally well, such as improving sensitivity in low-frequency variant detection, streamlining interpretation, or building a differentiated evidence base for a specific clinical use.
New entrants can still gain traction, but the path is becoming more demanding. Success increasingly depends on more than technical performance; it requires a credible route to adoption, evidence generation, regulatory alignment, and some form of workflow or economic advantage that makes the offering easier to justify in real-world settings. In that environment, purely incremental improvements are less likely to reshape the market than approaches that meaningfully change how results are generated, interpreted, or delivered.
Prostate Biopsy Devices Market
Outlook: Three Trends Shaping the Next Three to Five Years
From Detection to Decision Support
One of the most important trends is the shift from simply detecting biomarkers toward supporting clinical decisions more comprehensively. Liquid biopsy products are increasingly expected to help answer not only whether a marker is present, but what it means for therapy selection, resistance risk, disease trajectory, and follow-up intensity. That evolution favors workflows that integrate broader molecular insight with clearer interpretive framing and, where possible, actionable reporting formats.
The commercial opportunity here is substantial for companies that can pair analytical performance with usability. Decision support value can improve adoption by reducing ambiguity for clinicians, supporting more confident treatment adjustments, and strengthening the case for reimbursement when results are tied to measurable care improvements.
Growing Importance of Evidence, Standardization, and Reimbursement Alignment
A second trend is the rising premium on evidence quality and standardization. As the market matures, purchasers and regulators are likely to place greater weight on reproducibility, cross-site comparability, and well-characterized performance across populations and sample conditions. Products that can demonstrate consistent behavior in real-world workflows will have an advantage over those that rely primarily on controlled or narrowly defined validation contexts.
This trend also creates a risk for players that underestimate the commercial burden of evidence generation. Strong assay performance alone may not be enough if the surrounding clinical narrative, health economic argument, or reimbursement pathway remains weak. Companies that invest early in rigorous clinical studies, real-world data collection, and payer-relevant value framing will be better positioned to convert regulatory success into sustained commercial growth.
Expansion of Multi-Cancer and Broader Molecular Testing Narratives
A third trend is the broadening of the testing narrative itself. Multi-cancer early detection and related broad molecular screening concepts have attracted significant attention, and the regulatory progress of high-profile programs suggests that large-scale diagnostic concepts are moving closer to formal commercialization in some form. Even if the ultimate adoption path is incremental and indication-specific, the broader implication is clear: liquid biopsy is increasingly discussed not just as a tool for known cancers, but as part of a longer-term shift toward earlier, more systematic molecular screening and monitoring.
The associated opportunity lies in building platforms and evidence packages that can support multiple indications over time rather than a single static use case. The risk is that ambitious screening narratives may face scrutiny around false positives, follow-up burden, cost-effectiveness, and clinical outcome proof. Companies and investors should therefore treat expanded indication claims as long-term value drivers that still require disciplined validation, not as immediate commercial certainty.
Strategic Implications for Decision Makers
The market’s trajectory creates different priorities depending on a company’s role in the value chain.
For Manufacturers and Platform Developers
Focus on workflow completeness and evidence durability rather than isolated technical claims. Products that reduce integration friction, support reproducible interpretation, and align with regulatory and reimbursement expectations are more likely to secure lasting adoption. Consider whether the commercial advantage comes from proprietary depth, platform scale, service enablement, or software-led differentiation, and build the evidence strategy around that choice.
In addition, evaluate whether the business model should extend beyond consumables and instruments into services, localized partnerships, or interpretation tools that increase customer stickiness. Where testing can be made easier to deploy and easier to trust, the path to scale shortens.
For Investors
Assess companies on the strength of their regulatory trajectory, evidentiary roadmap, and commercial execution rather than on technology novelty alone. The market rewards products that can demonstrate clinical utility in ways that matter to payers and providers, and it penalizes those that depend on undifferentiated feature competition. Pay close attention to whether a company’s pipeline is anchored by clear intended use, realistic adoption mechanics, and a credible plan for post-market performance and real-world data generation.
It is also prudent to distinguish between near-term revenue drivers and longer-term optionality. Some assets may offer immediate commercial momentum through targeted oncology applications, while others may carry higher future value tied to broader screening or multi-indication expansion, but with greater evidentiary and reimbursement uncertainty.
For Procurement and Health System Leaders
Prioritize total workflow impact over headline assay performance. Evaluate how a liquid biopsy solution will fit into existing laboratory operations, what training and bioinformatics support are required, how results will be reported and acted upon, and whether the offering can support multiple clinical questions over time. Standardization, service reliability, and clinical interpretation support may matter as much as analytical sensitivity in day-to-day use.
Request evidence that is relevant to the intended population and setting, and clarify the reimbursement and follow-up pathways associated with test results. A strong test that cannot be operationally sustained or economically justified will underdeliver relative to its technical promise.
Closing Perspective
The liquid biopsy products market is entering a phase where growth will be determined less by whether the technology works in principle and more by whether it can be proven, standardized, reimbursed, and embedded into real clinical workflows. The companies and institutions that thrive will be those that treat liquid biopsy as a commercial system rather than a laboratory product: one that connects analytical performance with clinical relevance, operational practicality, and evidentiary credibility.
For organizations seeking a more detailed view of segment-level dynamics, regional variation, competitive benchmarking, and scenario-based growth paths, a fuller research report can provide the supporting structure needed for planning and investment decisions. The broader strategic message, however, is already clear: the next stage of market leadership will belong to players who can convert scientific promise into dependable, scalable, and economically sustainable diagnostic value.
For detailed analysis of this topic, please visit the official page: Liquid Biopsy Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


