



Optical Distribution Frame Market: Why 9.5% CAGR and Telecom Shift Change Everything

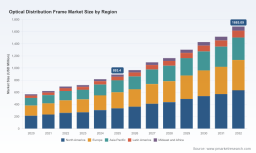
The Optical Distribution Frame Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The optical distribution frame market has transitioned from a steady infrastructure component to a critical enabler of next-generation connectivity. Total market revenue is projected to expand from approximately 893 million USD in 2025 to roughly 1,685 million USD by 2032, reflecting a compound annual growth rate of 9.5 percent over the forecast period. Historical momentum through 2025 illustrates a market that accelerated meaningfully after 2023, with revenue climbing at a pace that outpaced broader telecom infrastructure spending in several regions. The trajectory signals a structural shift rather than a cyclical uptick, driven by capacity demands that older distribution architectures were never designed to accommodate.
Despite the favorable top-line outlook, the market faces several inflection points that will separate adaptable players from those locked into legacy configurations. First, the definition of density is changing. Traditional frame designs optimized for incremental port additions are now encountering physical and thermal constraints as single racks and enclosures must support thousands of splice points without compromising maintainability. Second, deployment speed has become a competitive differentiator. Operators and data center developers are no longer willing to accept multi-day commissioning cycles for optical distribution layers, yet many existing product lines still rely on field-terminated assemblies and manual circuit labeling. Third, the supply chain environment continues to reward manufacturers that can balance standardized modularity with rapid customization, while penalizing those exposed to volatile component costs and fragmented logistics networks.
These challenges converge on a single strategic question: how to deliver higher connectivity density, faster time-to-service, and reliable operational performance without inflating total cost of ownership. The market is not simply asking for more ports; it is asking for smarter distribution architectures that integrate identification, validation, and scalability at the point of installation.
Key Drivers Shaping the Market
Technology Innovation and Architectural Breakthroughs
Innovation in optical distribution is increasingly centered on hyperscale density, single-fiber handling, and pre-integrated deployment models. Recent product introductions demonstrate how frame architecture is being re-engineered to support rapid mesh connectivity in AI-driven data center environments. One notable example is a hyperscale optical distribution frame capable of supporting up to 5,760 splices per frame, incorporating single-fiber splicing, tracer fiber circuit identification, and pre-assembled deployment features. This level of integration reduces on-site assembly complexity and improves circuit traceability, both of which are becoming essential as rack-level fiber counts multiply.
Beyond raw port counts, design innovation is shifting toward tool-less installation, full front access, and modular scalability. These attributes matter because they reduce skilled labor dependency and enable repeatable deployment patterns across multiple sites. In practical terms, improved mechanical design and pre-configured connectivity options can compress installation timelines while lowering the risk of human error during splicing and labeling. For operators, that translates into faster service readiness and more predictable operational overhead.
Policy and Regulatory Environment
Policy momentum continues to reinforce fiber-based connectivity as a foundational utility rather than an optional premium service. Government-backed broadband expansion programs, rural connectivity initiatives, and regulatory pressure to close digital access gaps are expanding the addressable base for optical distribution infrastructure. At the same time, data center build-out is being shaped by broader digital policy priorities, including cloud sovereignty, enterprise digitization, and the need for resilient interfacility links.
This environment creates a dual effect. Public-sector and regulated networks often require proven interoperability, long-term supply reliability, and documented maintainability, which favors established platforms and disciplined manufacturing practices. Meanwhile, commercial data center projects prioritize speed and density, pushing vendors to deliver flexible architectures that can be adapted across diverse cabinet form factors and site constraints. The regulatory tailwind is therefore not uniform; it amplifies demand across segments while simultaneously raising the bar for reliability and serviceability.
Demand-Side Shifts in Telecom and Data Centers
Demand is being reshaped by two powerful forces: the relentless scale-up of data center interconnectivity and the continuing evolution of telecom access networks. Data centers are no longer passive consumers of connectivity; they are active fabric nodes that require dense, manageable, and quickly reconfigurable optical distribution layers. The rise of distributed compute, higher rack power densities, and mesh-style network designs is increasing the number of fiber terminations that must be organized, identified, and maintained within compact enclosures.
On the telecom side, fiber deepening into metro and access networks is supporting higher-capacity service offerings and more granular network segmentation. Operators are seeking distribution solutions that can accommodate both traditional indoor termination needs and higher-density configurations aligned with 19-inch or 21-inch cabinet standards. The practical outcome is a market in which demand is broadening across legacy service upgrades and new high-density deployments, but the requirements within each application are becoming more specific and performance-sensitive.
Supply Chain and Cost Structure Dynamics
Cost structure is increasingly determined by design efficiency and deployment simplification rather than component price alone. Pre-assembled configurations, standardized module footprints, and improved fiber management can reduce field labor time and mitigate installation variability. In contrast, solutions that require extensive on-site termination or manual tracing often carry hidden operational costs that emerge during maintenance and reconfiguration.
Supply chain resilience also matters more than ever. Manufacturers that can maintain consistent quality, support multiple cabinet formats, and deliver predictable lead times are gaining an advantage in competitive bid processes. The broader dynamic is a shift in value capture from pure volume production toward integrated solutions that lower total deployment and operating costs. In this environment, pricing power is increasingly tied to demonstrated efficiency gains rather than commodity positioning.
PW Consulting Automotive & Machinery Research Center
Competitive Landscape and Leading Strategies
The market is shaped by a concentrated group of manufacturers with distinct strategic postures. One leading player has positioned itself around hyperscale data center performance, emphasizing extreme splice capacity, single-fiber handling, tracer fiber circuit identification, and pre-assembled deployment for rapid rollout in AI-driven mesh networks. This product direction reflects a clear bet on density and speed as primary purchasing criteria in large-scale facility builds.
Another major provider focuses on indoor fiber termination and splicing across standardized cabinet configurations, offering 48- and 96-core variants designed for 19-inch or 21-inch enclosures. This approach underscores the continued importance of reliable, form-factor-aligned solutions for telecom and enterprise indoor networks, where compatibility, serviceability, and proven performance remain central buying considerations.
A third active manufacturer emphasizes flexible access architectures and modular scalability, with platforms that support full front access, tool-less installation, and ultra-high density connectivity for telecom and data center use. The emphasis here is on adaptability and installation efficiency, targeting buyers who need to balance density with maintainability across diverse deployment contexts.
Together, these positions highlight a market in which differentiation is increasingly defined by how well a product reduces deployment friction while meeting application-specific density and access requirements. The competitive landscape is evolving along several lines:
- Consolidation is likely to continue as larger players pursue cross-platform integration and broader fiber management portfolios, especially where data center and telecom requirements increasingly overlap.
- At the same time, differentiation will create pockets of specialization, with some vendors concentrating on hyperscale high-density frames while others retain strength in indoor termination, modular scalability, or service-friendly access designs.
- New entrants and technology-driven challengers may gain traction by targeting specific pain points such as circuit identification, pre-integration, and faster commissioning, particularly if they can demonstrate measurable reductions in deployment time or maintenance effort.
For incumbents, the strategic imperative is to avoid competing solely on port count or price. The more durable advantages are likely to come from repeatable deployment models, clear serviceability benefits, and the ability to scale across both telecom and data center environments without forcing customers into a single cabinet philosophy.
Future Trends and Strategic Implications
Density Will Become a Design Philosophy, Not Just a Spec Sheet Number
Over the next three to five years, optical distribution frames will be evaluated less by simple port counts and more by how effectively they manage extreme fiber densities in real operating conditions. Expect continued pressure toward higher splices per frame, improved airflow and thermal behavior around dense closures, and more advanced circuit identification methods that reduce troubleshooting time. The commercial opportunity lies in offering architectures that make high density operationally manageable, not merely physically possible. Manufacturers and system integrators that can prove lower error rates, faster reconfiguration, and smoother maintenance at high densities will be well positioned.
Pre-Integration and Rapid Deployment Will Redefine Procurement Value
The trend toward pre-assembled, ready-to-deploy distribution platforms is likely to accelerate as operators and data center developers seek to compress project schedules. Solutions that combine validated fiber paths, pre-labeled or light-guided identification, and tool-less installation will become more attractive in competitive bids, especially where labor availability or on-site expertise is constrained. The strategic implication is that procurement decisions will increasingly weigh installation efficiency and commissioning certainty alongside hardware cost. This creates opportunities for vendors that can standardize high-density modules while still accommodating site-specific configurations.
Segment Blurring Between Telecom and Data Center Requirements
The boundary between telecom access networks and data center interconnect environments is becoming less rigid. Both domains are pushing for higher density, cleaner fiber management, and faster deployment, even if they emphasize different cabinet sizes, access styles, and operational priorities. As a result, product platforms that can flex across these environments without sacrificing reliability or serviceability will capture broader demand. The risk is that manufacturers may over-index on one segment and miss the growing overlap in deployment needs. Buyers, in turn, will benefit from more consistent architectures, but they will also need to assess whether a given platform can scale across future site designs rather than only fitting a current project.
Risks and Uncertainties to Monitor
Several uncertainties could reshape the market’s trajectory. A slowdown in data center expansion, or a shift toward more distributed and less fiber-intensive compute models, could temper the most aggressive density assumptions in certain regions. Regulatory or procurement changes could also influence the balance between standardized platforms and customized solutions, especially if public funding programs impose stricter interoperability or lifecycle requirements. In addition, if labor markets remain tight, the value of tool-less and pre-integrated designs will rise, but any manufacturing bottlenecks that delay complex pre-assembled products could undermine that advantage.
Worldwide Optical Networking IC Market
Actionable Guidance for Decision-Makers
For manufacturers and product strategists, the priority is to align innovation with operational outcomes rather than density alone. Develop platforms that make high-density deployment repeatable, traceable, and service-friendly. Where possible, invest in pre-integrated configurations and modular scalability so that customers can standardize where it matters and adapt where they need to. Differentiation should be anchored in measurable deployment benefits, such as reduced installation time, easier circuit identification, and lower maintenance complexity.
Optical Transceivers Market
For investors, the most compelling exposure is likely to be in capabilities that reduce total cost of ownership across the deployment lifecycle. Evaluate companies not only by revenue momentum, but by the extent to which their product architecture addresses installation speed, density manageability, and cross-application flexibility. Businesses that can serve both telecom and data center demand with coherent platforms may enjoy broader growth optionality, while those overly dependent on a single form factor or application may face more volatile demand patterns.
For procurement and network planning teams, the practical focus should be on future-proofing fiber distribution decisions. Favor solutions that can accommodate rising densities without forcing premature replacement cycles, and evaluate total deployment and maintenance effort rather than hardware price in isolation. Pay close attention to compatibility with cabinet standards, access preferences, and anticipated reconfiguration needs. In high-density environments, circuit identification, splice management, and modular scalability can have as much operational impact as raw port count.
Given the pace of change in product architecture, deployment expectations, and application overlap, detailed segment-level intelligence is increasingly valuable for shaping product roadmaps, investment theses, and purchasing strategies. Comprehensive research can help clarify how demand is shifting across regions, applications, and mounting styles, and where competitive differentiation is likely to be earned or lost. For organizations that need sharper visibility into segment dynamics, forecast ranges, and vendor-specific positioning, the full market study provides a deeper basis for decision-making.
For detailed analysis of this topic, please visit the official page: Optical Distribution Frame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


