



Polyurea Coatings Market: 6.3% CAGR & What’s Really Fueling Growth

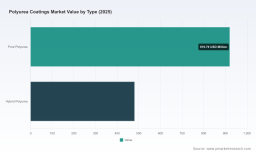
Beyond the Coating: Strategic Shifts Shaping the Polyurea Market Through 2032
The global polyurea coatings market has entered a phase of structural expansion, underpinned by a compound annual growth rate of 6.33 percent across the historical and forecast horizon. Revenue has climbed from approximately 874 million USD in 2020 to a base-year estimate near 1.4 billion USD in 2025, with forward trajectories pointing toward 2.15 billion USD by 2032. This growth is not merely a continuation of past momentum; it reflects a convergence of material science advancement, stricter environmental mandates, and infrastructure renewal cycles that are reshaping how protective and structural liners are specified. For executives, investors, and procurement leaders, the question has shifted from whether polyurea will gain share to how the value chain will reorganize around performance, sustainability, and regional demand concentration.
1. Market Landscape and Core Challenges
The market is building on a clear upward trajectory, with revenue stepping up consistently from the early 2020s through the current base year. Forecasts indicate continued expansion through the end of the decade, though the pace will be shaped by regional demand concentration, raw material exposure, and the pace of adoption in construction and industrial sectors. The construction segment remains a central demand anchor, while industrial and transportation applications contribute meaningful incremental growth. Geographically, Asia Pacific and Europe together account for a substantial portion of near-term activity, with North America maintaining a steady, mature presence.
Against this backdrop, three challenges are emerging as inflection points that will separate outperforming players from the rest of the field.
Raw material volatility and margin pressure. Isocyanates and amine resins sit at the core of polyurea chemistry, and their price swings carry a high probability of disrupting cost structures. When input costs move abruptly, formulators and end-users face compressed margins or delayed specifications, particularly in price-sensitive segments where switching to alternatives is easy. Companies that lack hedging mechanisms, long-term supply agreements, or formulation flexibility will find it harder to maintain price competitiveness while protecting performance standards.
Regulatory and environmental compliance as a gatekeeper. Projects subject to strict environmental compliance increasingly favor coatings that minimize or eliminate volatile organic compounds. Because polyurea formulations are typically 100 percent solids and free from VOCs, they are positioned as an environmentally preferred choice. At the same time, manufacturers are accelerating development of low-VOC and solvent-free variants to align with tightening regulations and the broader demand for sustainable solutions. This creates a dual dynamic: compliance is accelerating adoption, but it also raises the bar for R&D, testing, and documentation, especially in regions where specifications are evolving rapidly.
Performance requirements and application complexity. Demand is no longer limited to basic waterproofing or protective linings. End-users are specifying materials that must handle blast mitigation, chemical resistance, rapid cure, and long service life in harsh conditions. This shifts competition away from price alone and toward technical validation, installation reliability, and lifecycle performance. Suppliers that can demonstrate consistent results across varied substrates, climates, and duty cycles are better positioned to capture high-value contracts, while those dependent on commoditized offerings face growing pressure.
2. Key Drivers of Market Change
Several forces are interacting to accelerate adoption and reshape value capture across the polyurea coatings market. Understanding how these drivers reinforce one another provides a clearer view of where opportunities will materialize.
Technology innovation and material performance breakthroughs. Advances in polymer architecture and formulation are expanding the range of conditions that polyurea can address. Recent product introductions illustrate this trajectory: one manufacturer launched an intumescent technology that delivered roughly a 10 percent improvement in polymer performance, signaling that incremental formulation gains can translate into tangible protective and fire-related benefits. In parallel, development efforts continue around durability, cure speed, and chemical resistance, enabling faster installation and longer maintenance intervals. For buyers, these gains reduce total cost of ownership even when upfront material costs are higher.
Policy and regulatory environment favoring low-emission, durable solutions. Environmental regulations are increasingly shaping procurement criteria. Because polyurea is commonly formulated as a 100 percent solids coating without VOCs, it aligns well with projects that must meet strict environmental compliance targets. Industry activity also reflects a broader shift toward sustainable chemistry platforms that reduce emissions while improving longevity and performance. This alignment helps polyurea compete not only on protection, but also on regulatory fit, especially in public infrastructure, industrial containment, and building envelope applications where compliance documentation carries significant weight.
Demand-side shifts in construction, infrastructure, and industrial asset protection. Renewal cycles for aging infrastructure and growing needs for durable building envelopes are expanding the use case set. Demand is reinforced by specifications that call for rapid cure, high elongation, and resistance to abrasion or chemical exposure, characteristics that align with polyurea's strengths. In industrial settings, containment and corrosion protection remain priorities, while transportation and specialized structural programs add further pull. The more demanding the environment, the stronger the case for high-performance coatings over conventional alternatives.
Supply chain and cost structure dynamics. Cost structures are being shaped by both raw material exposure and regional capacity decisions. Volatility in key inputs can tighten margins and alter price competitiveness, which has prompted some companies to pursue capacity expansion in strategic markets to better serve regional demand and reduce logistics friction. Capacity additions in key manufacturing hubs are intended to support faster response times and lower lead times for high-volume programs, helping to stabilize availability for large-scale projects.
3. Competitive Landscape and Leading Strategies
The competitive environment reflects a mix of large multinational resin and coatings producers and specialized formulators that focus on application-specific polyurea systems. This structure creates differentiation across product range, technical depth, and end-market focus.
Large producers bring scale, broad resin portfolios, and the ability to serve multiple downstream industries from a single platform. Their strength often lies in integrated chemistry, global distribution, and the capacity to align polyurea with broader portfolio offerings in protective and architectural coatings. Specialized manufacturers, by contrast, frequently compete on tailored formulations, spray-applied elastomer systems, and direct engagement with demanding end-use cases such as blast mitigation, heavy industrial containment, and high-durability flooring.
Recent activity highlights how these players are positioning themselves.
Capacity and regional demand alignment. One global producer expanded production capacity for polyester and polyurethane resins at a plant in Shanghai to support automotive and Asia Pacific demand. This move reflects a broader pattern of aligning manufacturing footprint with regional growth centers, improving responsiveness, and reducing exposure to cross-market logistics constraints.
Product leadership and performance differentiation. Another major coatings player introduced a new intumescent technology that improved polymer performance by roughly 10 percent, reinforcing the importance of formulation innovation as a competitive lever. Performance gains of this kind can influence specification decisions in fire protection and high-risk environments where incremental improvements carry outsized commercial value.
Program-focused expansion into specialized applications. A leading pure polyurea manufacturer announced more than a dozen blast mitigation contracts spanning eight countries, involving Gulf region government ministries and global hardened shelter programs. This signals a growing stake in highly specialized, performance-critical applications and illustrates how reputational credibility in extreme-condition use can open doors to large, multi-country procurement programs.
Worldwide Polyurea Waterproof Material Market
The market concentration profile suggests that a relatively small group of firms holds a substantial share of total activity, while a longer tail of formulators and regional specialists competes on customization, service, and niche technical strengths. Over the next several years, the balance is likely to tilt toward further differentiation rather than undifferentiated consolidation. Leading players will compete on technical validation, application engineering, regional capacity, and sustainability credentials, while new entrants and smaller specialists continue to find room in specialized flooring, containment, waterproofing, and protective systems. Vertical integration, joint development with specifiers, and stronger field service capabilities are likely to become more valuable as end-users increasingly demand documented performance and consistent install quality.
4. Future Trends and Commercial Implications
Looking ahead across the next three to five years, several trends are likely to determine where growth concentrates and how value is captured.
Sustainability and low-emission formulations become default selection criteria. As environmental compliance tightens and project owners place greater emphasis on long-life, low-emission materials, polyurea is poised to benefit from its solid, solvent-free profile. The trend will likely accelerate specification in building envelopes, infrastructure, and industrial asset protection. The commercial implication is clear: companies that can document environmental performance, offer solvent-free or low-VOC options, and support compliance paperwork will have an advantage in bids and repeat programs. The risk is that specification requirements become fragmented across regions, forcing suppliers to manage multiple formulation and certification pathways.
Specialized, performance-critical applications expand faster than commoditized segments. Blast mitigation, chemical containment, and extreme-condition protection are driving demand for coatings that deliver predictable behavior under stress. This favors suppliers with strong technical credibility, validated field performance, and the ability to support complex installations. Growth in these segments can be more profitable than volume-driven price competition, but it also requires higher levels of testing, documentation, and application support. The uncertainty lies in how quickly standards, codes, and procurement cycles adapt to new formulations and performance claims.
Regional capacity and supply resilience become strategic differentiators. Raw material volatility will continue to challenge cost planning, particularly for isocyanates and amine-based inputs. In response, some manufacturers will pursue regional capacity expansion and closer alignment with local demand centers to improve availability and reduce lead times. For buyers, supply resilience and stable lead times may increasingly matter as much as unit price, especially for time-sensitive infrastructure and industrial programs. The risk is that localized capacity adds require significant investment and take time to translate into consistent market-wide availability, particularly if demand accelerates beyond planned output.
PW Consulting
Tie these trends together and a commercial picture emerges. The strongest opportunities will likely belong to organizations that can combine performance, compliance readiness, and reliable supply in markets where durability and speed of installation matter. For investors and corporate strategists, the signal is to look beyond headline growth and assess which segments, regions, and capabilities will generate defensible margins in a more demanding environment.
5. Strategic Actions for Decision-Makers
Different roles in the value chain can take distinct but complementary steps to build advantage as the market evolves.
For manufacturers and formulators. Differentiate through validated performance rather than broad coverage alone. Invest in formulation lines that reduce VOC exposure and improve durability or cure behavior, and align capacity decisions with regional demand centers that offer the strongest growth signals. Strengthen technical sales and field support so that specification confidence and install consistency become part of the value proposition. Where raw material exposure is significant, build hedging, supplier diversification, or long-term agreements that protect margin stability without compromising quality.
For investors and corporate strategy teams. Evaluate opportunities based on segment defensibility, regional demand durability, and the ability to support high-performance applications with documentation and service. Favor business models that combine material advantage with application engineering and compliance readiness, because those attributes will increasingly influence winning positions. Monitor capacity announcements and regional expansion closely, as they can indicate where supply will tighten or loosen and where future pricing power may shift. Avoid assuming uniform growth across regions, applications, and product types, since value creation will be uneven.
For procurement and specification teams. Treat total cost of ownership as the core decision frame. A coating that cures faster, lasts longer, and reduces maintenance can outperform a lower-cost alternative over the asset's life, especially in demanding environments. Prioritize suppliers that can provide clear compliance documentation, consistent application support, and predictable availability. Build multi-supplier or qualified-product strategies where possible, so that raw material volatility or single-source risk does not stall critical projects.
Powder Coatings Market
The market's trajectory will be shaped by how quickly organizations can align product capabilities with the environments where polyurea creates the most value. Detailed segmentation, regional demand breakdowns, competitive positioning, and scenario-based forecasts can sharpen these decisions and reduce the risk of acting on assumptions rather than evidence. More granular data and customized analysis are available through PW Consulting's complete market research report, which extends this overview into segment-level structures, regional dynamics, and actionable strategic recommendations tailored to specific business objectives.
For detailed analysis of this topic, please visit the official page: Polyurea Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


