



Sport Bottle Market: Why 3.4% CAGR Trajectory Masks Material Shifts

The Sport Bottle Market: Strategic Trends and Commercial Opportunities Through 2032
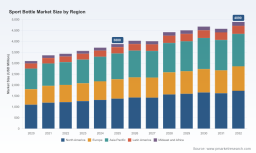
The sport bottle market is entering a phase of structural transformation where long-standing growth patterns are being reshaped by regulatory pressure, material innovation, and shifting hydration habits across both consumer and performance segments. From a base of roughly 3.88 billion USD in 2025, the market is projected to expand toward approximately 4.89 billion USD by 2032, reflecting a compound annual growth rate of about 3.4 percent. This trajectory is not simply a story of incremental volume growth. The period between 2020 and 2025 already showed how recovery from pandemic-era disruptions, the return of organized sports, and the normalization of active lifestyles supported steady expansion, but the years ahead will be defined by tougher questions around material compliance, thermal performance, and how brands translate hydration products into identity-driven accessories.
One of the most important aspects of this landscape is the way value is distributed across regions, materials, and use cases. North America and Asia Pacific remain central engines of demand, while Europe continues to exert disproportionate influence through regulatory frameworks that shape formulation, labeling, and recyclability expectations. On the material side, stainless steel and plastic continue to anchor large portions of revenue, but the balance between them is shifting as insulation capabilities, weight considerations, and recycled content mandates create new trade-offs. The application side further illustrates the breadth of the category, spanning fitness training, outdoor sports, and cycling and running activities, each with distinct performance requirements and purchasing logics. In a market where the top three competitors account for roughly 21.5 percent of revenue and the top five reach about 27.8 percent, the category is broad enough to invite segmentation but concentrated enough that scale, distribution, and brand credibility still matter enormously.
Beyond Volume Growth: The Structural Inflection Points
Three challenges are redefining how companies compete in this space. First, regulatory requirements are moving from background compliance issues to active design constraints. In the United States, multiple states have moved toward post-consumer recycled content requirements for plastic beverage containers, with Washington state setting a 25 percent recycled content standard that begins in 2026. California has advanced extended producer responsibility obligations for single-use packaging and introduced plastic reduction targets that shape portfolio decisions far beyond individual SKUs. In Europe, the Single-Use Plastics Directive has set recycled plastic content expectations for PET beverage bottles and separate collection targets that influence how bottlers and drinkware manufacturers think about feedstock, traceability, and end-of-life performance. These rules are not static. The European Commission’s public consultation in late 2025 on the impacts of the directive signals that expectations around beverage bottles may continue to evolve, keeping compliance a moving target rather than a fixed checklist.
Second, the category is being pulled between durability and sustainability in ways that directly affect product architecture. Stainless steel continues to command a strong position because it supports temperature retention and a premium feel, but it also introduces cost, weight, and manufacturing complexity. Plastic remains highly relevant for portability, shatter resistance, and cost efficiency, particularly in active and promotional use cases, but its value proposition increasingly depends on resin innovation and recycled content credibility. Silicone and glass address specific niches, yet each must justify its place in a crowded field where consumers and procurement teams alike are scrutinizing material claims more carefully. The result is that material choice is no longer just a sourcing decision; it is a positioning decision that affects perceived quality, user experience, and regulatory exposure simultaneously.
Third, the market is facing a quiet but meaningful pressure to turn utility into distinction. Many sport bottles solve the same basic problem, yet the difference between a commodity transaction and a durable brand relationship often comes down to lid design, insulation performance, leak resistance, ergonomic comfort, and visual identity. As more manufacturers enter the space and as private-label and OEM/ODM capabilities expand, the risk of margin compression rises for players that cannot articulate a clear functional or emotional advantage. At the same time, the growth of customization in handles, caps, and branding options indicates that differentiation is increasingly achieved through system-level design rather than the bottle body alone.
Key Drivers Reshaping the Category
Technology and Design Innovation
Innovation in this market is not only about launching new bottles; it is about improving how people drink during movement, how bottles survive harsh conditions, and how products balance thermal retention with weight and convenience. Vacuum-insulated stainless steel remains a critical platform because athletes, outdoor users, and everyday active consumers value beverages that stay cold or hot for longer periods. At the same time, lid engineering is becoming a strategic battleground. Leak-proof systems, easier assembly, and more effortless sipping are being refined to reduce friction during workouts, commutes, and travel. Insulated and leak-proof collections continue to expand as manufacturers respond to demand for reliability in fitness, outdoor, and performance environments.
Material technology is also becoming more nuanced. Tritan-based plastics and Tritan Renew variants have gained attention for durable, BPA-free construction that supports lifestyle and outdoor use while offering a pathway toward recycled content integration. For manufacturers serving both retail and promotional clients, the ability to combine durability with custom drinkware design has become a practical competitive edge. In parallel, automated production lines and ISO certifications are increasingly important for suppliers that need to deliver consistent quality at scale, especially for aluminum and stainless steel options. The broader trend is clear: the product is becoming more modular in the eyes of both engineers and buyers, with the cap, insulation layer, body material, and surface finish all functioning as levers for performance and positioning.
Policy and Regulatory Environment
The regulatory environment is one of the strongest forces shaping category economics. Requirements for post-consumer recycled content in plastic beverage containers are no longer isolated initiatives; they are accumulating across multiple U.S. states, including California, New Jersey, and Maine, and are being reinforced by European directives with concrete recycled content and collection targets. Extended producer responsibility frameworks add another layer of accountability, encouraging manufacturers and brand owners to think beyond the point of sale and consider collection, recyclability, and material reduction. For sport bottle producers, these pressures create two simultaneous imperatives: redesign products and packaging with compliance in mind, and communicate material choices with greater precision to avoid ambiguity.
This is especially relevant because the sport bottle category spans both reusable drinkware and single-use-adjacent formats. Even when the end product is reusable, upstream packaging, resin sourcing, and manufacturing footprints are increasingly examined. Companies that can align product design with evolving content standards, and that can demonstrate credible sourcing and recycling pathways, are better positioned to reduce compliance risk and to use sustainability as a trust signal rather than a marketing overlay. The broader implication is that regulatory preparedness is becoming a form of strategic insulation. Firms that treat compliance as a design constraint now will have more flexibility when standards tighten further or when public consultations lead to revised expectations.
Demand-Side Shifts in Consumer and Business Behavior
On the demand side, hydration is increasingly treated as part of a broader active lifestyle identity rather than a purely functional purchase. Fitness training remains the largest application context, reflecting the scale of gym-based, group, and individual exercise habits, while outdoor sports and cycling and running segments continue to reinforce demand for portable, durable, and temperature-controlling bottles. Consumers in these segments often evaluate products through a blend of performance, aesthetics, and durability, which means a sport bottle can function as both a tool and a visible accessory.
For businesses, the demand picture includes both branded retail and institutional or promotional procurement. Retail consumers look for leak resistance, insulation, ease of cleaning, and a design that fits daily use. Corporate buyers, event organizers, and brand marketers, by contrast, often prioritize customization, branding consistency, and the perceived professionalism of the product in hand. This dual demand base creates an opportunity for manufacturers that can serve both ends without losing focus. The rise of private-label and custom drinkware capabilities reflects the reality that many buyers want hydration products to carry their own identity while still meeting functional expectations. A bottle that performs well but feels generic is increasingly vulnerable; a bottle that performs well and signals something specific about the user or the sponsoring organization has a stronger commercial path.
Supply Chain and Cost Structure Dynamics
Cost structure and supply chain resilience are becoming more strategic as material volatility, compliance costs, and production complexity interact. Plastic pricing, resin availability, recycled feedstock access, and stainless steel processing costs all influence margins, but they also influence design choices. Manufacturers that rely on a single material or a narrow supplier base can find themselves exposed when rules change or when feedstock expectations shift. In response, many companies are diversifying the materials they produce and the end markets they serve, or they are building stronger capabilities in customization and contract manufacturing to capture value across different customer types.
Geographically, the market reflects a mix of established branded players and highly capable manufacturing ecosystems. Some companies compete through brand equity, insulation performance, and lifestyle positioning, while others compete through scale, OEM/ODM breadth, and the ability to deliver multiple materials and configurations efficiently. This divergence matters because it shapes pricing power, margin structure, and the speed at which new product variants can be brought to market. Companies that can combine reliable production with agile customization are better placed to meet the growing demand for tailored hydration solutions without sacrificing consistency. At the same time, businesses that depend too heavily on commodity-style volume without a clear performance or brand story may face more intense pressure as the category matures.
Water Bottles Market
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The competitive field in the sport bottle market is characterized by a blend of brand-centric specialists, performance-focused manufacturers, and large-scale production capabilities. Several companies have built their identities around specific material advantages or use-case specialization. Aluminum beverage bottlers have emphasized shock resistance and style for active consumers and events. Insulated stainless steel brands have leaned on temperature retention and durable construction for long-duration outdoor and athletic use. Tritan-based plastic producers have highlighted durable, BPA-free construction for hiking, cycling, and outdoor activities. Leak-proof lid systems and sustainable bottle offerings have gained attention among buyers who want convenient hydration without sacrificing environmental credibility.
These different strategic postures matter because they shape how each player handles the core trade-offs of the category. A company anchored in insulation performance can justify a premium by emphasizing temperature control and durability. A company rooted in flexible plastic or promotional drinkware can compete on weight, cost, and customization variety. A manufacturer with strong OEM/ODM credentials can win by offering speed, breadth, and private-label capability. Neither approach is inherently superior, but each requires disciplined execution. The more differentiated the positioning, the more important it becomes to protect the associated claims through product quality, consistent user experience, and credible communication.
Recent Product and Portfolio Moves
Recent activity in early 2026 illustrates how companies are sharpening their market position through product and catalog updates. One brand reintroduced a redesigned sport lid intended to make sipping easier and assembly more straightforward for active use. Another manufacturer released an updated custom drinkware catalog with vacuum-insulated sport bottle options marketed for enhanced thermal retention. A third company introduced a new sports water bottle collection featuring handles and multiple lid options to expand customization choices. These moves may appear incremental, but they reflect a larger pattern: companies are investing in the details that determine daily satisfaction, such as lid usability, thermal performance, handle ergonomics, and options for branding or personalization. In a mature category, improvements in these areas can be the difference between a product that is merely functional and one that earns repeat use and recommendation.
How the Market Structure Is Evolving
The market is not moving toward a single dominant structure. Instead, it is showing signs of both consolidation and fragmentation at different levels. On one hand, established brands with strong distribution, recognizable design language, and clear performance positioning continue to capture meaningful share. On the other, the availability of OEM/ODM and custom manufacturing capacity allows new and existing players to enter with tailored SKUs, private-label programs, and niche material or lid solutions. This creates a layered landscape where scale, brand, and specialization can all win in the right context.
What is likely to intensify is the importance of portfolio architecture. Companies that can manage multiple materials, lid systems, insulation classes, and branding options will have more flexibility to serve both consumer and business demand. Those that remain narrowly focused may still succeed, but they will need a very clear reason to exist, whether that is superior thermal retention, a distinctive design identity, a cost advantage, or a specialized manufacturing capability. The growing emphasis on recycled content, durability, and lid performance suggests that the market will increasingly reward players who can integrate compliance, engineering, and user experience rather than treat them as separate functions.
Future Trends and Commercial Opportunities Over the Next 3 to 5 Years
Trend One: Regulatory-Aligned Material Design as a Default Expectation
Over the next few years, recycled content requirements, extended producer responsibility considerations, and collection targets will increasingly influence how sport bottles are specified and purchased. This will create opportunity for manufacturers and brand owners that can design for compliance without sacrificing usability. The commercial advantage will likely go to those who can offer credible material stories, provide transparent sourcing and content information, and adapt product lines quickly when standards evolve. Buyers in retail and procurement will probably place more weight on verifiable compliance and material accountability, especially in markets where rules are becoming standardized or more strictly enforced.
The risk here is that compliance becomes a fragmented burden if expectations diverge significantly across regions or if verification requirements become more demanding. Companies that depend on a single material path or on suppliers without strong documentation and change-management capabilities may face higher adaptation costs. The opportunity is to treat regulatory alignment as part of product architecture, not as a late-stage adjustment.
Trend Two: Performance, Convenience, and Visual Identity Converge
A second trend is the continued blending of functional performance and lifestyle appeal. Insulated stainless steel products will remain important for users who need reliable temperature retention, but the competitive edge will increasingly come from the full system: lid usability, leak resistance, cleaning convenience, weight, grip, and appearance. Plastic-based and hybrid solutions will continue to serve portability and cost-sensitive segments, especially where shatter resistance and lightweight handling matter. Meanwhile, brand-led and private-label offerings will depend more heavily on customization, because a sport bottle that can be adapted to a user group, team, corporate program, or event can serve both practical and symbolic purposes.
The commercial implication is that value creation will shift further toward design coherence and repeatability across a portfolio. A strong bottle body is necessary but not sufficient. Lid systems that are easier to use and harder to leak, finishes that withstand regular handling, and customization options that support branding without compromising function will be central to differentiation. The risk is that too many products converge on similar exterior styling without meaningful performance differences, making it harder to justify premium pricing or customer loyalty.
Trend Three: A More Layered Competitive Map Open to Specialists
The third trend is structural: the market is likely to remain broad and multi-speed. Branded players with strong consumer equity will continue to compete on design, trust, and perceived quality. Manufacturing-focused players will continue to win on cost, scale, flexibility, and OEM/ODM breadth. Between these poles, there is room for specialists who can combine a clear performance claim with efficient production and credible sustainability positioning. New entrants may not need to dominate the whole category; they can succeed by owning a specific material niche, a particular use case, or a distinctive lid and cap system.
For investors and executives, this layered structure means that the value of a given business depends heavily on how it is positioned within the ecosystem. A high-volume generic supplier faces a different outlook than a premium insulated brand or a flexible custom drinkware manufacturer. The same market can therefore produce very different strategic priorities depending on where a company sits. The uncertainty is that regulation, raw material dynamics, and consumer taste can shift the relative attractiveness of each path, so portfolio assumptions need to be revisited regularly rather than treated as durable for long periods.
Actionable Implications for Decision Makers
For Manufacturers
Companies producing sport bottles should evaluate their portfolios against three questions: can the product line adapt quickly to recycled content and packaging requirements, can the lid and insulation system deliver a genuinely better user experience, and can the business support customization without losing manufacturing discipline. Where a manufacturer relies heavily on one material or one customer type, it may be worth building additional route-to-market flexibility, whether through additional material options, more lid variants, or stronger private-label capabilities. At the same time, quality consistency, documentation for compliance, and clear product claims should be treated as strategic assets, not administrative burdens, because they increasingly influence both risk and commercial positioning.
For Investors
Investors evaluating opportunities in this market should focus less on headline category growth and more on the business model behind each opportunity. Insulated premium brands, flexible customization manufacturers, and suppliers with strong compliance readiness will have different margin structures, growth levers, and risk profiles. Due diligence should examine material exposure, lid and cap engineering capability, geographic and regulatory exposure, and the ability to move quickly when packaging or content requirements change. It is also worth assessing whether a company’s growth depends on genuine differentiation or on volume in a segment that may face price pressure as more competitors gain access to similar manufacturing capabilities.
PW Consulting
For Procurement and Brand Buyers
Buyers selecting sport bottles for retail programs, corporate use, or promotional campaigns should look beyond unit price and assess the total ownership picture: material compliance readiness, durability in the intended use environment, lid reliability, and the ease of cleaning and refilling. For branded or private-label programs, customization capability matters, but it should be paired with validation that the customized version still meets functional expectations. Buyers that treat hydration products as part of a longer-term user experience, rather than as one-off items, are more likely to choose suppliers that can support consistent quality, future material adjustments, and credible sustainability claims.
Getting Ahead in a Market That Rewards Precision
The sport bottle market is not heading toward a simple boom or bust. It is moving toward a more demanding environment in which growth depends on navigating regulation, delivering reliable performance, and differentiating through details that matter in daily use. The revenue path from 2025 toward 2032 suggests continued expansion, but the more important question for individual companies is whether they are positioned to capture value in the segments, materials, and use cases that matter most to their strategy. Companies that align product design with evolving content expectations, invest in lid and insulation performance, and build credible customization capability will have more options as the category matures.
Hydration Bottle Market
For decision makers who need a sharper look at regional dynamics, material-specific revenue patterns, application-level demand splits, concentration metrics, and the competitive tactics shaping each sub-segment, the full PW Consulting research report provides a more detailed breakdown and tailored guidance. It offers a closer view of where value is accumulating, where compliance pressure is likely to reshape sourcing and product design, and how manufacturers, investors, and buyers can prioritize their next moves with more confidence.
For detailed analysis of this topic, please visit the official page: Sport Bottle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


