



Airbag Market to Hit $29.79B by 2032: Decoding the 7.25% CAGR Growth and Asia Pacific's Dominance Shift

Navigating the Airbag Market: Strategic Trends and Commercial Opportunities (2026–2032)
The global airbag market has entered a maturation phase characterized by steady expansion, technological diversification, and shifting regulatory pressures. Valued at approximately $18.28 billion in 2025, the sector has grown consistently from $12.93 billion in 2020, reflecting a compound annual growth rate of 7.25 percent through 2032. This trajectory is not merely a function of rising vehicle production; it signals a structural realignment in how occupant and external safety are engineered, regulated, and commercialized. For executives, investors, and procurement leaders, the next seven years will reward those who align product strategy with evolving safety expectations, supply chain resilience, and regional regulatory divergence.
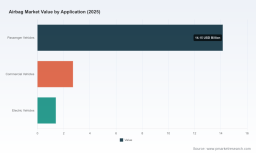
Beneath the headline growth figures lies a market exhibiting pronounced concentration and regional asymmetries. The top three suppliers capture roughly 62.8 percent of revenue, while the top five account for 74.5 percent, indicating an environment where scale, established automaker relationships, and integrated component capabilities create durable moats. At the same time, the market’s composition reveals where value creation is accelerating: frontal systems remain the largest category, side airbags command significant share, and knee/curtain configurations are expanding as vehicle architectures grow more complex. On the application side, passenger vehicles dominate revenue generation, commercial vehicles represent a stable but slower-growing segment, and electric vehicles are carving out a distinct growth corridor as platform designs and battery-related safety considerations reshape module requirements. Understanding these structural patterns is essential before evaluating the forces that will shape competitive positioning through the end of the decade.
Market Landscape and Core Challenges
The airbag market’s expansion is anchored in a multi-year upward trajectory, but growth alone does not guarantee profitability or strategic advantage. Several structural frictions are forcing suppliers and automakers to recalibrate how they design, source, and deploy safety systems.
Regulatory Fragmentation and Compliance Complexity
Safety regulations are no longer converging globally; they are diverging in ways that complicate platform standardization. In the United States, the Department of Commerce’s January 2025 final rule on connected-vehicle information and communications technology supply chains has introduced new compliance pathways for components tied to vehicle electronics and embedded safety systems. While the rule targets ICTS sourcing, its ripple effects extend to airbag control units, sensing integration, and supplier qualification processes, particularly for companies with cross-border manufacturing footprints. This regulatory layer adds cost and timeline uncertainty, especially for suppliers navigating dual requirements across North American, European, and Asian markets.
Raw Material Volatility and Cost Structure Pressures
Airbag manufacturing remains sensitive to polymer and chemical input pricing. Nylon 6,6, a critical material for airbag fabric and structural components, experiences periodic price fluctuations driven by production capacity shifts and downstream demand dynamics. Ascend Performance Materials’ ongoing support of nylon 6,6 production for airbag applications underscores how tightly woven the material supply chain is. When feedstock costs move, suppliers must decide whether to absorb margin compression, renegotiate tier agreements, or accelerate material substitution programs. The companies that treat material strategy as a continuous optimization exercise rather than a periodic sourcing task will preserve competitiveness during cyclical price swings.
Waste Management and Recall-Related Liability
End-of-life handling and recall scenarios introduce operational and reputational risk that is often underestimated in top-line planning. Hazardous airbag waste falls under RCRA hazardous waste regulations, and the U.S. EPA’s October 2025 interim final rule on safe management of recalled airbags adds conditional exemptions and procedural requirements that affect how manufacturers, dealers, and recyclers manage inventory and field returns. For suppliers, this means that compliance does not end at the point of sale; it extends into reverse logistics, documentation, and cooperative recall response. Firms that build these processes into their operating models reduce exposure to regulatory friction and strengthen customer trust during safety interventions.
Taken together, these challenges point to a market where scale alone is insufficient. Growth will increasingly be captured by organizations that can manage regulatory complexity, stabilize input costs, and integrate safety with broader mobility ecosystems rather than treating airbags as isolated passive components.
Key Drivers Shaping Market Dynamics
The market’s forward trajectory is being pulled by three interconnected forces: technology innovation that expands the definition of protection, regulatory and policy shifts that raise baseline expectations, and demand-side behavior that blends occupant safety with external collision mitigation. A fourth driver, supply chain restructuring around cost and resilience, is determining who can profitably scale new configurations.
Technology Innovation and the Expansion of Protection Boundaries
Airbag technology is moving beyond traditional occupant compartments into external protection, specialty applications, and smarter deployment logic. Autoliv’s April 2026 launch of a second-generation cyclist-pedestrian protection airbag illustrates this shift. By covering a larger area to improve head protection during external collisions, the product reorients airbag value propositions around vulnerable road users and vehicle-to-environment interactions. Similarly, Daicel’s May 2026 wearable airbag, developed with NIIST and the Sony Acceleration Platform, extends automotive safety technology into elderly fall mitigation. These launches are not isolated product news; they signal that safety technology portfolios are becoming more modular and application-agnostic, creating pathways to non-automotive revenue streams and cross-market brand leverage.
Policy and Regulatory Pressure Raising Baseline Safety Expectations
Regulators continue to tighten occupant protection expectations, and vehicle safety ratings increasingly influence purchase decisions. The introduction of Volvo Trucks’ industry-first standard integrated side curtain airbag in February 2026, recognized as a HDT 2025 Top 20 Product, demonstrates how regulatory and rating-driven pressure can push advanced configurations from optional features to standard equipment in commercial segments. When flagship players normalize a technology, the threshold for competitor adoption rises, and procurement teams must plan for broader specification coverage across fleets. Policy momentum therefore operates as both a compliance requirement and a competitive cascade, accelerating adoption curves that might otherwise lag behind passenger-car segments.
Demand-Side Shifts in Consumer and Fleet Behavior
Buyers are increasingly treating safety as a differentiated purchase criterion rather than a standardized expectation. In passenger vehicles, this translates into demand for more comprehensive curtain, knee, and side configurations as cabin layouts evolve and seating positions change. In commercial vehicles, fleet operators are prioritizing driver protection and total cost of ownership, which makes standard safety packages more attractive when they reduce incident-related downtime and insurance exposure. Electric vehicles add another layer: platform architectures, battery placement, and weight distributions alter deployment zones and module placement logic, prompting suppliers to adapt designs to EV-specific packaging constraints. As a result, demand is no longer uniform across vehicle types; it is fragmenting by use case, platform, and operational profile.
Worldwide Belt Type Fall Protection Airbag Market
Supply Chain and Cost Structure Realignment
The supply base is responding to material volatility, geographic sourcing constraints, and the need for faster engineering feedback loops. Suppliers that integrate inflator technology, fabric engineering, and module assembly under coordinated development cycles can reduce lead-time variability and better manage cost transitions. At the same time, regulatory actions around ICTS and connected systems are encouraging regionalization and dual-sourcing strategies, particularly for electronics-adjacent safety components. The practical implication is that cost leadership is increasingly derived from integration, regional presence, and engineering responsiveness rather than sheer procurement volume alone.
These drivers converge on a single insight: the airbag market is expanding not just because more vehicles are being sold, but because protection is becoming broader in scope, more standardized at higher performance levels, and more dependent on integrated engineering capability.
Competitive Landscape and Strategic Positioning
The market’s concentration profile favors incumbent suppliers with global footprints, established automaker partnerships, and multi-product capabilities across inflators, modules, and complementary restraint systems. A review of the leading players shows how different strategic postures are being used to defend share and capture growth.
Incumbent Scale and Integrated Capabilities
Autoliv’s positioning as the world’s largest automotive safety supplier gives it broad exposure across airbags, seatbelts, and passive safety systems, enabling coordinated engineering across restraint categories. This scale supports platform sharing, global volume leverage, and the ability to introduce advanced external-protection concepts such as the cyclist-pedestrian airbag. Joyson Safety Systems occupies a similarly broad mobility safety position, extending beyond automotive into non-automotive markets, which diversifies revenue and creates cross-application learning loops. ARC Automotive focuses more narrowly on inflators for a wide range of airbag types, a specialization that makes it a critical component partner and allows it to influence deployment performance at a foundational level. Daicel brings chemical and plastics expertise to inflators, pyro-fuses, and related safety technologies, positioning it at the intersection of material science and safety performance.
Regional and Ecosystem-Embedded Players
Toyota Boshoku and Hyundai Mobis illustrate how supplier strength can be amplified by close ties to vehicle platforms. Toyota Boshoku’s interior systems capabilities and Hyundai Mobis’s module and safety technology portfolio benefit from group-aligned development cycles, which can shorten validation timelines and improve packaging fit. Nihon Plast and Toyoda Gosei add depth in safety components and interior/safety integration, while ZF Friedrichshafen and Continental contribute broader automotive technology portfolios that include occupant protection systems alongside seating and chassis-related competencies. These players demonstrate that differentiation is not limited to volume; it can also come from platform alignment, component specialization, and technology adjacency.
Strategic Differentiation and Competitive Evolution
The competitive evolution in this market is moving along two tracks. On one track, consolidation and partnership activity reinforce the advantages of scale, global service networks, and multi-component integration. On the other, differentiation is increasingly found in application expansion, such as external protection and wearable safety concepts, and in the ability to adapt to commercial vehicle standardization and EV packaging requirements. New entrants face a steep climb unless they bring a defensible technology niche, a distinctive material or inflator advantage, or a strong regional relationship model. The more probable competitive dynamic is continued concentration at the top, layered with selective specialization where performance, application scope, or regional compliance create meaningful separation.
For decision-makers, the practical takeaway is that supplier selection and partnership strategy should account for more than unit price. Engineering collaboration, regional compliance readiness, inflator and module integration depth, and the ability to support nonstandard configurations are becoming decisive factors in long-term value capture.
Forward Outlook: Trends and Commercial Implications
Looking ahead three to five years, three trends are likely to shape where value is created and where risk accumulates.
Trend One: External and Vulnerable-Road-User Protection Becomes a Commercial Priority
External protection concepts are moving from experimental to productized, as evidenced by cyclist-pedestrian airbag developments and broader attention to vehicle-to-environment interactions. This trend opens opportunities in advanced module designs, sensing-adjacent integration, and region-specific safety packaging. The commercial upside lies in differentiated safety claims, rating advantages, and potential regulatory alignment in markets that increasingly weigh external impact performance. The uncertainty is execution: external protection requires careful validation, packaging trade-offs, and cost discipline to avoid becoming a low-volume niche.
Trend Two: Standard Safety Packages Expand in Commercial and Specialty Segments
Commercial vehicle adoption of integrated side curtain airbags as standard equipment suggests a broader shift toward baseline protection in segments historically treated as optional. This creates demand visibility and volume stability for suppliers that can meet durability, service, and fleet-level specification requirements. The opportunity is in scalable module architectures, simplified service interfaces, and fleet-oriented documentation and support. The risk is margin pressure if standardization triggers price competition without accompanying engineering or service differentiation.
Automotive Airbags Market
Trend Three: EV- and Platform-Specific Safety Architectures Drive Customization Demands
Electric vehicle platforms continue to alter interior packaging, weight distribution, and component placement, which in turn affects airbag deployment zones and module form factors. Suppliers that can adapt quickly to platform-specific constraints will capture premium positioning and repeat business across model cycles. The upside is a shift from commoditized replacement logic to engineered safety integration, where value is tied to packaging efficiency and validation speed. The uncertainty is platform volatility: rapid EV redesign cycles can compress supplier development windows and increase engineering cost if not managed with early engagement and flexible module strategies.
Across these trends, the consistent commercial thread is that airbag value will increasingly be defined by integration, application breadth, and responsiveness to vehicle architecture changes rather than by component volume alone. Organizations that treat safety systems as part of a broader vehicle architecture and mobility-solution context will be better positioned to convert growth into durable margin.
Actionable Implications for Decision-Makers
-
For manufacturers and suppliers: Prioritize integration across inflators, fabrics, and module engineering to reduce lead-time variability and improve cost control during material price swings. Invest in external-protection and specialty application capabilities where validation pathways are achievable and regional demand signals are strengthening. Build reverse-logistics and recall-readiness processes into the operating model to manage waste regulation exposure and maintain customer confidence during field actions.
-
For investors: Focus on suppliers with durable automaker relationships, multi-product restraint exposure, and the ability to extend safety technology into adjacent applications. Evaluate exposure to regulatory-driven standardization in commercial vehicles and to EV-specific packaging adaptation, as these can shape volume visibility and engineering intensity. Monitor concentration dynamics and regional compliance readiness, since ICTS-related rules and material sourcing constraints can influence margin stability and geographic mix.
-
For procurement teams and fleet operators: Treat safety specifications as strategic levers rather than fixed checkboxes. Standard packages can improve fleet safety profiles and reduce incident-related operational friction, but they should be weighed alongside service support, regional compliance alignment, and supplier capability to handle nonstandard configurations. Engage early with suppliers on EV and commercial-platform requirements to secure packaging feasibility and validation timelines before specification lock-in.
The strategic value of these decisions depends on the granularity of the underlying data. Regional revenue distribution, type-level growth differentials, application-specific penetration patterns, and competitive share movements can materially change sourcing, investment, and product-planning choices. Detailed segmentation, forward volume assumptions, and company-level positioning are most useful when aligned to specific vehicle programs, geographic commitments, and margin targets. For teams that require that level of precision, a full research report can provide the supporting breakdowns and scenario detail needed to translate these market-level insights into operational planning.
The airbag market is not simply growing; it is being redefined by broader protection concepts, standardization pressure in commercial segments, and platform-specific adaptation in electric vehicles. Participants that align engineering, compliance, and application strategy with these shifts will be better positioned to convert market expansion into sustained competitive advantage.
PW Consulting
For detailed analysis of this topic, please visit the official page: Airbag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


