



Jet Engines Market: Why 6.5% CAGR and Civil Aviation’s 53% Share Redefine Growth

Strategic Fronts in the Jet Engines Market: Navigating Growth, Technology, and Geopolitical Complexity
The global jet engines market is entering a phase defined by the intersection of sustained demand recovery, accelerating technological evolution, and heightened geopolitical friction. Revenue for the segment reached USD 78.9 billion in 2025 and is projected to expand to USD 122.34 billion by 2032, translating to a compound annual growth rate of approximately 6.5% across the 2026–2032 forecast window. These figures reflect a market that has moved past the immediate disruptions of the early 2020s and is now being shaped by long-cycle fleet investment, regulatory pressure on emissions, and shifting supply-chain configurations. For executives and capital allocators, understanding where value will concentrate requires looking beyond headline growth and examining the structural forces that are redefining competitive advantage in propulsion.
Trajectory and Structural Dynamics
The market’s expansion over the 2020–2025 period was uneven but steadily positive, moving from roughly USD 64.78 billion in 2020 to the current 2025 baseline. Growth is now supported by a broad backlog of commercial aircraft deliveries, renewed military modernization programs, and the gradual replacement of aging powerplants with higher-thrust, more fuel-efficient configurations. The market remains moderately fragmented at the top, with the top three firms accounting for about 24.6% of revenue and the top five reaching approximately 26.2%. This concentration level indicates that durable pricing power and aftermarket control are still influenced by a small set of incumbents, even as specialized suppliers and regional players gain relevance in components, accessories, and dedicated platform programs.
Key Challenges and Inflection Points
Three structural challenges are redefining how value is captured across the jet engines market. First, the tension between near-term cost pressures and long-cycle innovation is intensifying. Engine development requires multi-year investment with uncertain returns, while operators and airlines are simultaneously sensitive to fuel costs and total operating expense. This creates a delicate balance where manufacturers must deliver measurable efficiency gains without destabilizing unit economics or delivery timelines. Second, the regulatory and trade environment is becoming more fragmented. Export-control measures now extend to certain civil aircraft parts when there is a risk of military end-use, and tariff frameworks have introduced new complexity for engine and aircraft trade flows. Supply commitments increasingly need to account for jurisdictional restrictions, license requirements, and sourcing adjustments. Third, the aftermarket is becoming a strategic battleground. As new engine families enter service, the long-term service, repair, and overhaul ecosystem will determine a meaningful share of lifecycle profitability, particularly for narrow-body and regional platforms that operate in high-cycle environments.
Core Drivers Reshaping Demand and Value Creation
The market’s direction is being shaped by forces that cut across technology, regulation, demand behavior, and cost architecture. Each driver interacts with the others, creating opportunities for firms that can align product strategy with changing operating realities.
Technology Innovation as a Competitive Lever
Efficiency and emissions performance are no longer secondary attributes; they are central to platform selection and long-term fleet economics. Next-generation engine programs are increasingly built around higher bypass ratios, advanced materials, and architectures that reduce fuel burn and carbon intensity. CFM International’s RISE program, for example, has matured technologies aimed at reducing net carbon emissions by up to 20% for the next-generation CFM engine targeted for mid-2030s entry. This kind of forward-looking development matters because it signals a shift from incremental upgrades to platform-level architectural change. For manufacturers, the implication is clear: differentiation will depend on the ability to demonstrate credible performance improvements that reduce operating costs while meeting evolving environmental expectations. For buyers, the practical question is whether near-term configuration choices will hold up under future regulatory and fuel-price scenarios.
Policy, Regulatory and Trade Dynamics
Policy is becoming a more direct factor in engine market economics. In early 2026, U.S. export-control measures under the EAR began requiring licenses for certain civil aircraft parts and components destined for China when there is a risk of military end-use. Earlier, U.S. authorities paused certain exports of aircraft and semiconductor technology, including jet-engine components, to China in response to Beijing’s restrictions on critical minerals. At the same time, the Trump administration imposed new tariffs on aircraft and engines in 2025, with exemptions for USMCA-compliant aerospace components from Canada and targeted measures against selected Chinese end-users. These developments do not simply change trade flows; they reshape sourcing strategies, after service coverage, and the relative attractiveness of different manufacturing locations. Companies that can design flexible supply chains and maintain compliance assurance will have an advantage in preserving program continuity and customer confidence.
Demand-Side Shifts in Civil and Military Aviation
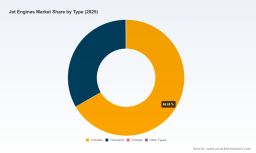
Demand is being driven by two reinforcing trends. In civil aviation, airline fleets are moving toward more efficient narrow-body and regional platforms, supported by sustained travel demand and a desire to reduce operating costs. In military aviation, modernization programs continue to require propulsion solutions that balance performance, survivability, and long-term sustainment. The market structure reflects this dual demand: civil aviation represents the majority of revenue, while military aviation remains a substantial and technologically demanding segment. For suppliers, this split suggests that growth is unlikely to come from a single path. Commercial programs reward scale, reliability, and low total cost of ownership, while defense and specialized platforms reward capability, customization, and secure production relationships. Firms that can manage both worlds without diluting execution quality are likely to maintain stronger strategic positioning.
Supply Chain and Cost Architecture
Cost dynamics remain a defining constraint. Global average jet fuel price fell 11.4% week-on-week to $141.64 per barrel, with U.S. Gulf Coast prices at $3.30 per gallon as of early June 2026. Even with this near-term relief, fuel continues to be a major operating expense, and volatility keeps efficiency on the agenda. At the same time, engine-makers are investing in site expansion and new manufacturing capacity to support output and complex part production. Safran, for example, expanded operations in Le Creusot to manufacture complex parts for Rafale engines, and Williams International began building a new $1 billion turbine engine factory in Florida. These investments suggest that capacity, precision manufacturing, and localized production are becoming as important as design leadership. For procurement teams and investors, the relevant insight is that the cost structure of propulsion is increasingly tied to manufacturing footprint, supply resilience, and the ability to manage long-lead inputs without sacrificing quality.
Competitive Landscape and Strategic Positioning
The market’s competitive structure is shaped by a small number of engine families, collaborative ventures, and a layered supplier base. Differences in platform focus, aftermarket control, and geopolitical exposure create distinct strategic positions rather than a single race to the bottom on price.
Leading Companies and Differentiated Advantages
GE Aerospace remains a central force in commercial turbofans, designing, manufacturing, and servicing a broad portfolio that includes CF34, CF6, the CFM LEAP family, CFM56, GEnx, and GE9X, alongside military engines for narrow-body, wide-body, and business aviation. Its breadth across multiple aircraft categories gives it scale and the ability to serve both high-volume and premium long-haul segments. Pratt & Whitney focuses on large commercial turbofans such as the GTF family, PW1000G, PW4000, and PW6000, powering platforms including the Airbus A320neo family, A220, and Embraer E-Jets. Its strategy is closely tied to narrow- and regional-jet adoption, making reliability and engine-family support important differentiators. Rolls-Royce positions itself strongly in wide-body propulsion through the Trent family, including Trent XWB, Trent 7000, Trent 900, Trent 500, and Trent 800 for aircraft such as the Boeing 787 and A350. This wide-body emphasis gives it a distinct role in long-haul operations where thrust requirements and mission profiles differ from single-aisle work.
Safran Aircraft Engines and CFM International illustrate the strategic value of joint-venture structures and platform concentration. CFM International, a 50/50 GE Aerospace–Safran JV, produces the LEAP and CFM56 narrow-body turbofans for the Airbus A320neo family and Boeing 737 MAX. Safran contributes the LEAP-1A/B/C single-aisle turbofans and brings additional reach into military programs. The JV model supports scale and resource sharing while concentrating risk and reward on dominant narrow-body platforms. MTU Aero Engines adds a complementary layer by focusing on component manufacturing and support for Pratt & Whitney GTF family engines and PW4000 engines, while also participating in next-generation fighter engine development. This positions MTU as a critical supplier and technology partner rather than a single-brand original equipment manufacturer. Tusaş Engine Industries supports indigenous jet engines and engine parts or modules for UAVs, commercial, and military aircraft, alongside assembly and component production for international programs. Its profile reflects a growing regional capability set that is especially relevant where sovereignty, defense readiness, and local content requirements shape procurement. Williams International rounds out the landscape with the FJ33/FJ44 business jet turbofan family, serving general aviation and business aircraft platforms. This specialization in business aviation creates a focused niche where product range, service responsiveness, and platform fit matter more than mass-market volume.
Recent Developments and Strategic Implications
Recent company actions show how the competitive field is shifting in practice. In May 2026, SSAMC became the first CFM LEAP Premier MRO Provider in China, and in April 2026, IAG and CFM signed a new LEAP Premier MRO license agreement. These moves underscore the importance of controlled aftermarket expansion and the strategic value of service authorizations in key geographies. In January 2026, Safran expanded operations in Le Creusot to manufacture complex parts for Rafale engines, reinforcing defense-oriented capacity. In February 2026, Safran launched the European Clean Aviation TAKE OFF project with partners, pointing toward collaborative decarbonization efforts that may influence future engine architectures and supporting ecosystems. Tusaş Engine Industries showcased national aviation engines at SAHA 2026 in May 2026, aligning with regional demand for sovereign propulsion capabilities. Williams International’s new $1 billion turbine engine factory in Florida, announced in April 2026, reflects continued investment in business aviation manufacturing capacity. Together, these developments highlight three recurring themes: the expanding importance of MRO ecosystems, the continued layering of defense and commercial production needs, and the strategic use of facility investment to support both volume and specialized output.
Emerging Structural Trends in Competition
The competitive landscape is not simply consolidating or fragmenting; it is becoming more layered. On one hand, integrated engine families and JV structures continue to concentrate value in capable incumbents with strong platform positions and aftermarket capability. On the other hand, specialized suppliers, regional manufacturers, and platform-specific entrants are gaining relevance in components, modules, UAVs, and defense programs. For the market as a whole, this means competition is increasingly multidimensional. Some firms will compete on scale, fuel efficiency, and global support networks. Others will compete on customization, regional access, and secure production relationships. New entrants are unlikely to displace the largest engine franchises quickly, but they can create meaningful influence in niches where local content, sovereign requirements, or specialized missions shape purchasing decisions. The strategic question for incumbents is whether they can preserve platform leadership while accommodating new suppliers and navigating trade-sensitive sourcing. For smaller players, the opportunity lies in demonstrating differentiated technical value and reliable execution in selected programs.
Diesel Engines Market
Forward Outlook: Where Value Is Likely to Concentrate
Looking across the 2026–2032 horizon, three trends are likely to shape commercial outcomes and define where strategic advantage can be built.
Efficiency as a Default Requirement, Not an Optional Upgrade
As next-generation engine technologies mature and environmental expectations tighten, efficiency will move from a competitive differentiator to a baseline requirement. CFM International’s RISE program is one example of how propulsion roadmaps are being structured around materially lower carbon emissions for mid-2030s entry. This matters commercially because efficiency improvements affect fuel costs, maintenance profiles, and fleet planning over long asset lives. For manufacturers, the opportunity is to turn technology roadmaps into credible product narratives and delivery commitments. For operators and financiers, the opportunity is to align platform selection with future operating conditions rather than only current economics. The uncertainty is timing: technology maturation, certification pathways, and airline fleet cycles do not always move in sync, and early positioning can carry commitment risk if deployment schedules shift.
Geopolitically Aware Supply Chains and Aftermarket Coverage
Trade policy, export controls, and tariff structures are now part of the market’s operating environment. License requirements for certain civil parts destined for China when military end-use risk exists, combined with broader export pauses and targeted tariffs, mean that engine supply and service coverage need to be mapped against jurisdictional rules. This creates a strategic premium for firms that can maintain resilient sourcing, qualify alternative supply paths, and offer customers predictable service continuity. Over the next few years, we can expect more attention to regional MRO capacity, localized production for sensitive platforms, and structured compliance management as part of customer value propositions. The risk is that overly rigid supply designs reduce flexibility, while overly simplified assumptions about trade rules create disruption when regulations change. The balance will favor companies that treat geopolitical exposure as a managed variable rather than a background condition.
Aftermarket Control as a Profitability Anchor
As new engine families accumulate service hours, the aftermarket will increasingly determine lifecycle economics. Service agreements, MRO provider designations, and license relationships are becoming more visible strategic tools. Recent MRO agreements involving CFM and regional providers show how engine-makers are building service presence in important markets. This trend is likely to continue because aftermarket revenue can be more stable and recurring than new-engine delivery cycles, especially for high-utilization narrow-body fleets and long-serving military platforms. For competitive positioning, the ability to provide reliable, authorized support can reinforce customer lock-in and improve total-value perception. The risk is that aftermarket expansion can become uneven if service capacity, parts availability, or regulatory access does not keep pace with engine placement, especially in complex or trade-sensitive regions.
Rocket Engine Market
Actionable Guidance for Decision-Makers
The jet engines market offers strong long-cycle growth, but capturing value requires decisions that reflect technology timing, trade complexity, and aftermarket strategy rather than relying on demand growth alone.
For Manufacturers, Program Leaders, and Suppliers
Align product roadmaps with the efficiency expectations that are now reshaping platform selection. This means investing not only in performance claims, but in certification progress, serviceability, and demonstrable operating-cost reduction. Build supply strategies that can tolerate export-control and tariff friction without disrupting core programs. Where possible, diversify critical component sources and maintain clear compliance pathways for cross-border movement of parts and technical data. For component suppliers and specialized manufacturers, identify niches where sovereign content, defense readiness, or dedicated platform support create structural demand, and focus on execution reliability and qualification speed.
For Investors and Corporate Strategy Teams
Evaluate propulsion exposure with a focus on lifecycle economics, not only unit sales. Engine programs with strong aftermarket potential, durable platform adoption, and manageable trade exposure are likely to offer more predictable value than those dependent on narrow delivery windows. Pay attention to where capacity investments are being made and how service coverage is expanding, because these signals often precede shifts in competitive strength. Be attentive to concentration risk and to the fact that market leadership may be unevenly distributed across civil and military segments, regions, and engine types. A portfolio view that distinguishes between high-volume narrow-body exposure, wide-body specialization, and defense-linked production can provide better clarity on where returns are most likely to materialize.
For Procurement, Fleet Planners, and Operating Companies
Treat propulsion selection as a multi-period decision. Engine efficiency, fuel-price exposure, support availability, and compliance complexity should all be weighed together, because a lower acquisition cost can be offset by higher operating expense or service constraints over time. When evaluating options, prioritize vendors that can demonstrate reliable local or regional support, clear licensing and trade readiness, and stable parts and MRO pathways. In trade-sensitive contexts, structure sourcing and service plans to reduce disruption risk, including contingency arrangements for spare parts, repair capacity, and technical support. Where specialized platforms or UAVs are involved, consider whether indigenous or regional capability offers strategic value beyond pure cost comparison.
PW Consulting
Why Deeper Intelligence Matters Now
The market is moving on several axes at once: technology roadmaps are advancing, trade and export conditions are shifting, and aftermarket relationships are becoming more strategically important. These changes alter which combinations of platform, geography, and supplier capability will generate the strongest returns. Broad market sizing and high-level segmentation can identify direction, but they do not show where specific opportunities are likely to open or where exposure may be concentrated. Detailed forecasts by engine family, application, region, pricing trajectory, and program-level service dynamics are needed to turn strategic themes into operational decisions. For that reason, teams evaluating investments, production plans, or procurement strategies should pair this high-level view with a more granular research asset that maps the segments, company developments, and regional dynamics in greater depth. A full research report can provide the decomposed data and customized assumptions required to test scenarios, prioritize initiatives, and compare competitive positioning across the most relevant segments.
For detailed analysis of this topic, please visit the official page: Jet Engines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


