



Industrial Refrigeration Equipment Market: Why Asia Pacific and Ammonia Redefine the 4.9% CAGR Outlook

The Industrial Refrigeration Equipment Market: Navigating the Next Wave of Growth and Transformation
The industrial refrigeration equipment market is entering a structurally distinct phase. Over the 2020 to 2025 period, the market expanded from approximately $17.87 billion to $22.70 billion, reflecting a compound trajectory that has outpaced many adjacent industrial segments. The forecast period through 2032 points to continued expansion, with revenue projected to reach roughly $31.73 billion, translating to a compound annual growth rate of 4.9 percent. These figures represent more than incremental capacity additions; they signal a market transitioning from steady replacement cycles to a demand profile shaped by regulatory mandates, refrigerant transitions, and capital expenditure patterns that favor higher-efficiency, lower-emission architectures.
Beneath the headline growth lies a landscape that is simultaneously fragmented in execution and increasingly concentrated in strategic influence. The market continues to operate with a moderate concentration profile, where the top three participants command roughly 38 percent of total revenue and the top five approach 46 percent. This structure suggests that while regional specialists, engineering firms, and component suppliers retain meaningful share, scale players and technology-focused incumbents are widening their influence through integrated system offerings, expanding service footprints, and partnerships that reduce project risk for end users. For executives and investors, the implication is clear: the market is large enough to sustain multiple business models, yet selective enough that differentiation in technology, compliance readiness, and service economics will increasingly determine who captures disproportionate value.
Market Context and Strategic Challenges
The current market environment is defined by a collision of long-cycle infrastructure demand and fast-moving regulatory and technological change. Three challenges stand out as particularly consequential for companies operating across the industrial refrigeration value chain.
First, the refrigerant transition has moved from a compliance topic to a design constraint that influences equipment architecture, component selection, and total cost of ownership. Natural refrigerant platforms, especially carbon dioxide and ammonia, are increasingly central to new installations and major retrofits. However, the shift is not uniform. Different applications impose different safety, efficiency, and operating-pressure requirements, and the pace of adoption varies by region, sector, and capital budget. Equipment manufacturers and system integrators are therefore being asked to support a broader portfolio of solutions while maintaining engineered reliability across diverse operating conditions.
Second, cost pressure on inputs is reshaping project economics. Tariff actions affecting steel and aluminum imports have pushed up the cost of compressors, condensers, and structural frameworks. In industrial refrigeration, where systems often represent large capital projects with long payback expectations, material cost volatility can alter bid dynamics, compress margins, and delay commitment cycles. The challenge is not simply higher input prices, but managing the ripple effects through supply agreements, lead-time planning, and value engineering without compromising durability or energy performance.
Third, the market is navigating a complex and evolving standards environment. Regulatory provisions targeting high-global-warming-potential refrigerants, combined with energy efficiency priorities and updated safety standards, are raising the bar for system design and operation. For operators, this means more scrutiny on refrigerant choice, maintenance practices, and lifecycle performance. For suppliers, it means that product differentiation is increasingly tied to compliance readiness, documentation, training, and the ability to support customers through transitions rather than simply shipping hardware.
These challenges should not be read only as headwinds. They are also reshaping the basis of competition. Companies that can offer lower-risk transitions, stronger energy performance, and more predictable project execution are finding greater leverage with customers who must balance operational continuity with regulatory and sustainability obligations.
Core Drivers Shaping the Market
Several forces are working in Concert to reshape demand, pricing, and competitive positioning across industrial refrigeration. The most consequential can be grouped into technology, policy, demand-side behavior, and supply-side cost structures.
Technology Innovation and the Rise of Natural Refrigerant Systems
The most visible technical shift is the acceleration of carbon dioxide and ammonia-based solutions in commercial and industrial applications. Recent industry activity highlights how rapidly these platforms are moving from specialized niches into broader mainstream consideration. At AHR Expo 2026, for example, the exhibition floor featured a strong showing of CO2-based products, including condensing units, transcritical and subcritical compressor technologies, and specialized valves and fittings designed for natural refrigerant systems. This level of visibility matters because it signals that suppliers are not only advancing individual components but also building out integrated ecosystems around refrigerants that require distinct engineering approaches.
For the market, the practical implication is that equipment roadmaps are increasingly aligned with refrigerant performance curves, system controls, and safety architecture. Companies that can combine compressors, heat exchangers, valves, and controls into coherent, application-specific solutions are better positioned to reduce integration risk and improve system reliability. At the same time, component-level innovation remains essential. Specialized fittings, check valves, and ball valves for high-pressure CO2 environments illustrate how seemingly narrow product categories can become critical enablers of broader adoption.
Policy and Regulatory Pressure as a Market Catalyst
Policy is no longer a peripheral factor. In the United States, EPA Technology Transitions provisions under the AIM Act have established a schedule that bans HFC refrigerants with a GWP above 700 in new industrial process refrigeration chillers starting January 1, 2026, with additional phased limits tightening to a GWP of 300 for certain cold storage applications. Broader EPA rules effective at the same date prohibit high-GWP refrigerants across new commercial and industrial refrigeration systems. These timelines create a concrete forcing function for equipment selection and replacement planning.
In parallel, energy efficiency is becoming a more prominent policy target. Industrial refrigeration compressors have been identified by the U.S. Department of Energy as a priority category for energy efficiency standards, reflecting the scale of energy consumption in food and pharmaceutical manufacturing. This matters because it links refrigerant policy with operational cost policy. Customers are increasingly asked to optimize for both environmental compliance and energy consumption, which elevates the strategic importance of high-efficiency compressors, improved heat exchange design, and controls that adapt to load variability. Updated industry standards, such as revised industrial refrigeration guidelines incorporating the latest ISO and safety requirements, further reinforce the direction of travel toward more formalized design and operational practices.
Demand-Side Change Across Food, Pharmaceutical, and Industrial End Markets
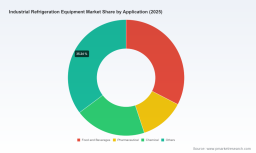
Demand is being reshaped by more than regulatory compliance. Cold chain reliability, production quality, and operational resilience have become priority concerns across multiple end-use sectors. In food and beverage operations, temperature control remains foundational to product quality and safety, but customers also care about throughput, redundancy, and energy intensity. In pharmaceutical applications, precision and reliability are paramount, and refrigeration systems are increasingly viewed as part of a broader quality and compliance infrastructure rather than isolated mechanical assets. Chemical processing and other industrial uses add further complexity, where refrigeration may be tied to process conditions, batch consistency, and facility-level efficiency goals.
Road Transport Refrigeration Equipment Market
A notable demand-side dynamic is the shift toward lifecycle thinking. Buyers are increasingly looking beyond first cost and considering the broader economics of refrigerant choice, maintenance requirements, service availability, and expected energy consumption over the life of the system. This does not eliminate price sensitivity, but it does change the criteria by which solutions are evaluated. Suppliers that can articulate and deliver on total cost of ownership, including compliance and service considerations, are better positioned to compete in capex-heavy and mission-critical environments.
Supply Chain Dynamics and Cost Structure Sensitivity
The cost environment remains an important driver of market behavior. Tariff-related increases on steel and aluminum have affected key structural and mechanical components, adding uncertainty to project planning and procurement. In an industry where lead times, sourcing reliability, and build quality all affect customer confidence, input cost volatility can have outsized effects on quoting, scheduling, and margin management.
At the same time, supply chain dynamics are encouraging greater attention to sourcing strategy and design flexibility. Some manufacturers are revisiting material specifications, supplier diversification, and inventory buffers to reduce exposure. Others are using system architecture choices to optimize cost and performance simultaneously, for example by balancing component consolidation against redundancy and serviceability. These adjustments are not merely defensive; they can become sources of advantage when executed with discipline and transparency.
Competitive Landscape and Leading Strategies
The competitive field in industrial refrigeration equipment is diverse, spanning commercial and industrial unit manufacturers, compressor specialists, component suppliers, and project-oriented system integrators. Rather than a single dominant model, the market rewards different forms of differentiation depending on the customer segment and application.
Several companies illustrate the range of strategic positions now in play. Heatcraft Refrigeration Products focuses on unit coolers, condensers, and evaporators for commercial and industrial refrigeration applications, positioning around core components that are widely specified across multiple system architectures. Magna Industrial Refrigeration provides industrial refrigeration equipment, components, and solutions, including unit coolers for commercial and industrial use, reflecting a strategy centered on breadth of product availability and application coverage. NDL Industries emphasizes high-pressure CO2 fittings, valves, check valves, and three-way valves for industrial refrigeration and natural refrigerant systems, illustrating how a component-focused specialist can play a vital role in enabling refrigerant transitions.
PW Consulting
On the compressor and system side, Danfoss, Copeland, and Bock GmbH represent technology-driven positions that emphasize solutions for low-temperature and transcritical CO2 applications, along with compressor platforms tailored to industrial cold storage and process cooling. These players are competing not just on hardware, but on the ability to offer engineered solutions that simplify adoption of natural refrigerants and support specific performance targets. Frigo Mekanik represents a complementary model, specializing in project design, manufacturing, and turnkey installation of industrial refrigeration cooling systems. This approach highlights the continuing importance of integration capability, especially where site-specific constraints, local service requirements, and project execution risk are significant.
Recent industry activity reinforces the direction of these strategies. The IIAR Natural Refrigeration Conference and Heavy Equipment Expo featured exhibitors such as Magna Industrial Refrigeration by Heatcraft, underscoring continued engagement with industrial refrigeration and natural refrigerant safety and equipment. Meanwhile, Frigo Mekanik’s participation in the HVACR Egypt Expo 2026 points to the regional expansion of project-oriented players seeking exposure to international demand and project pipelines. On the event calendar, RETA’s national conference continues to provide a focused forum for industrial refrigeration systems and components, reinforcing the importance of concentrated industry gatherings in shaping technology diffusion, standards awareness, and supply chain relationships.
Worldwide Compression Refrigeration Machine Market
The competitive trends that emerge from this landscape are best described as selective integration paired with targeted specialization. Larger players are broadening their offerings to reduce customer friction across specification, installation, and service, while specialized suppliers are deepening their role in critical subsystems that become differentiators in natural refrigerant applications. The market is not necessarily moving toward a single consolidated model; instead, it is evolving toward ecosystems in which components, compressors, controls, and project capabilities are combined in ways that reduce total risk for the buyer. In that environment, companies that can demonstrate compliance readiness, reliable performance under changing refrigerant regimes, and strong service economics are likely to capture a disproportionate share of high-value projects.
Forward Outlook: Trends and Opportunities for 2026 to 2030
Looking ahead, the market is likely to be shaped by a small number of reinforcing trends that translate into defensible commercial opportunities for well-positioned players.
One major trend is the continued mainstreaming of natural refrigerant solutions in new builds and retrofits. As regulatory deadlines take effect and customer expectations around environmental performance rise, CO2 and ammonia platforms will see increasing specification in a wider range of applications. The commercial opportunity lies not just in selling equipment, but in helping customers manage the engineering, safety, and operational implications of these systems. Suppliers that can standardize design approaches, simplify commissioning, and provide robust field support will be better positioned to scale adoption without eroding reliability.
A second trend is the tightening link between refrigerant policy and energy efficiency. As efficiency standards and compliance requirements reinforce one another, end users will increasingly look for solutions that reduce both emissions exposure and operating cost. This creates opportunities around high-efficiency compressors, improved heat transfer designs, advanced controls, and integrated monitoring that supports optimization over time. The upside is especially significant in sectors with high utilization and sensitive temperature requirements, where even modest efficiency improvements can translate into meaningful operational savings.
A third trend is the growing importance of service, lifecycle support, and standards-based execution. As systems become more specialized and regulations more detailed, the value of post-sale support rises. Customers will increasingly favor partners that can help with maintenance planning, technician training, spare parts availability, and compliance documentation. This shift favors companies that treat service not as an afterthought, but as a core part of the commercial proposition. It also raises the stakes for component and equipment suppliers to design for maintainability and to align their offerings with updated industry standards and safety practices.
These trends are not without risk. The pace of adoption may vary by region and application, and customers may delay capital decisions if cost pressures, interest rates, or project timelines become unfavorable. Material cost volatility can continue to complicate bidding and margin planning. In addition, technological transitions can create temporary friction, especially where engineering expertise, trained labor, or supply availability lag behind product availability. Companies should therefore treat natural refrigerant leadership as a long-term play that requires disciplined execution, not simply a product-line expansion.
Strategic Implications for Decision Makers
The most useful way to approach this market is to align strategy with the forces that are most likely to determine purchasing decisions and competitive outcomes over the next several years. The following recommendations are intended to separate signal from noise and focus action where it matters most.
For equipment manufacturers and system integrators, the priority is to reduce the friction of transition. This means developing and communicating clear pathways for natural refrigerant adoption, strengthening integration across components and controls, and reinforcing service and training capabilities that lower customer risk. Where material cost pressure is persistent, value engineering and supply chain resilience should be treated as strategic capabilities rather than transactional tasks. Differentiation will increasingly come from how well a company helps customers navigate compliance, efficiency, and reliability together.
For investors and strategic partners, the opportunity is to identify businesses whose value is tied to durable shifts rather than short-cycle demand. Indicators of resilience include exposure to applications with high uptime requirements, strong positions in components or subsystems essential to natural refrigerant systems, and service models that generate recurring value beyond initial equipment sales. It is also worth watching how companies adapt to cost volatility and whether they can convert regulatory pressure into differentiated offerings rather than treating it as a compliance burden.
For procurement leaders and end-user organizations, the focus should be on total cost and transition risk. Specifying equipment with an eye toward lifecycle energy performance, refrigerant compliance, service availability, and ease of maintenance can reduce exposure to future regulatory changes and operating cost escalation. Where capital projects are planned, early engagement with suppliers on system architecture, standards alignment, and local support can improve execution certainty and reduce the likelihood of costly rework or delayed commissioning.
For all of these audiences, timely access to detailed market data can sharpen decision-making. Segment-level dynamics, regional demand patterns, competitive moves, and regulatory timelines all influence how opportunities should be prioritized. A focused view of these variables helps turn broad market growth into a more actionable plan, especially when decisions involve capital intensity, long service life, and compliance-sensitive technologies.
Closing Perspective
The industrial refrigeration equipment market is large, expanding, and increasingly governed by structural forces that reward clarity of strategy. Growth to the mid-2030s is expected to remain steady, but the more important story is how that growth is being shaped by refrigerant transitions, efficiency priorities, input cost pressures, and the rising importance of service and integration. Companies that can combine technical strength with compliance readiness, project reliability, and lifecycle value will be best positioned to convert market expansion into durable advantage. For executives, investors, and procurement leaders, the practical task is to use these signals to prioritize where to invest, where to differentiate, and where to reduce risk before the next wave of regulatory and demand-side change fully settles in.
For detailed analysis of this topic, please visit the official page: Industrial Refrigeration Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


