



Electric Car Chargers: The 22.5% CAGR Reshaping the $143M Market

Electric Car Chargers Market: Strategic Trends and Commercial Opportunities
The electric vehicle charging infrastructure sector has shifted from a niche sustainability initiative to a core component of global transportation and energy systems. Over the past half-decade, the market has demonstrated consistent momentum, with revenue scaling from approximately 12.5 billion USD in 2020 to 34.8 billion USD by 2025. Projections through 2032 place the sector on a trajectory toward 143.1 billion USD, supported by a compound annual growth rate of roughly 22.5 percent. This expansion reflects more than incremental adoption; it signals a structural realignment in how electricity is distributed, consumed, and monetized across mobility networks.
USB Car Chargers Market
For executives and investors, the numbers themselves tell only part of the story. The real value lies in understanding what is accelerating deployment, what is constraining it, and where competitive advantages are being forged. The charging ecosystem no longer operates as a standalone hardware play. It intersects with grid capacity, fleet electrification timelines, consumer payment expectations, and increasingly stringent domestic sourcing rules. Companies that treat charging infrastructure as a systems integration challenge rather than a transactional equipment sale are beginning to capture disproportionate margins and market share.
Several inflection points are reshaping the landscape. First, the gap between residential and commercial deployment is widening in strategic importance. While home charging remains foundational for individual vehicle owners, commercial and public charging networks are becoming the primary battleground for scale, utilization rates, and recurring revenue models. Second, the technology mix is bifurcating between slower alternating current solutions and higher-power direct current systems, each serving distinct use cases and requiring different grid interconnections, permitting pathways, and maintenance frameworks. Third, market concentration remains moderate, with the top three players holding a combined share near 35 percent and the top five approaching 42 percent. This fragmentation suggests room for consolidation, but also indicates that regional specialization, software differentiation, and partnership ecosystems matter more than pure manufacturing volume.
Key Drivers Shaping Market Trajectory
Technology Innovation and Performance Thresholds
Charging hardware is evolving from a relatively static product category into a performance-optimized platform. Direct current fast charging continues to advance in power output and thermal management, enabling shorter dwell times for medium- and heavy-duty fleets, ride-hailing operations, and highway corridor deployments. At the same time, alternating current chargers are gaining intelligence through embedded load-balancing algorithms, energy monitoring, and integration with home energy management systems. The practical effect is a market where throughput, reliability, and software responsiveness increasingly determine utilization rather than mere charger availability.
Recent industry activity illustrates this shift. Tritium has been advancing its DC fast charging portfolio through modular platforms designed for ultra-fast public and fleet scenarios, emphasizing scalability and serviceability in high-traffic environments. ZEROVA has focused on high-power commercial and fleet applications, pushing hardware capable of delivering substantial charging capacity in constrained spaces. These developments reflect a broader industry realization that charger specifications must align with operational realities: fleet turnaround windows, peak demand pricing, and site electrical constraints. Companies that design for modular upgrades, remote diagnostics, and predictable uptime are reducing total cost of ownership for operators and improving session completion rates.
Policy and Regulatory Dynamics
Government procurement standards, utility make-ready programs, and domestic content rules are actively shaping where and how infrastructure gets deployed. In the United States, federal-aid projects face evolving Buy America requirements that have prompted discussions about raising domestic content thresholds for EV charger components. Proposed adjustments would increase the required share of domestic component costs, with comment periods and implementation guidance continuing to mature through early and mid-2026. For projects obligated after certain dates, charger compliance frameworks are aligning more closely with general manufactured products rules, which changes how suppliers structure supply chains and document sourcing.
At the state and utility level, interoperability and hardware conformance standards are gaining enforcement traction. Certain public service commission programs have begun requiring ISO 15118-3 hardware conformance for level 2 chargers, signaling a move toward standardized communication protocols that support smoother plug-and-charge experiences, billing transparency, and grid integration. These rules do more than set technical baselines; they influence which products can participate in subsidized programs, how quickly deployments can clear regulatory review, and which manufacturers have the compliance infrastructure to scale across jurisdictions.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user expectations are changing the economics of charging networks. Individual consumers increasingly prioritize ease of payment, session reliability, and predictable pricing over raw charger count. Fleet operators and commercial property managers, meanwhile, are evaluating charging infrastructure through the lens of operational continuity, energy cost management, and vehicle utilization schedules. This divergence is pushing vendors to offer more segmented solutions: residential and light commercial options that emphasize installation simplicity and smart energy features, versus high-throughput public and fleet systems built for repeated high-power cycles.
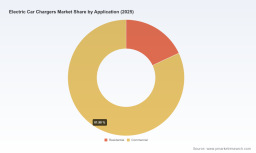
The commercial application segment has become particularly important in revenue terms, reflecting the growing role of workplace charging, retail destinations, logistics hubs, and fleet depots. As more organizations electrify portions of their vehicle assets, charging infrastructure is no longer a peripheral amenity; it is part of the operational backbone. That shift raises the stakes for uptime, remote monitoring, and service response times. It also encourages companies to bundle hardware with network services, energy management tools, and site-level load optimization, creating value beyond the initial equipment sale.
Supply Chain Structure and Cost Dynamics
Hardware manufacturing, component sourcing, and installation capacity remain central to market execution. Domestic content expectations, semiconductor and power electronics availability, and regional manufacturing footprints all influence lead times and pricing stability. Suppliers that can maintain consistent quality while navigating changing procurement rules are gaining an advantage in federally supported and utility-sponsored programs. At the same time, the cost structure of charging deployments is increasingly tied to electrical upgrades, civil works, and network connectivity rather than the charger unit alone. This reality rewards companies that offer streamlined installation pathways, interoperable components, and financing or turnkey models that reduce project friction.
Recent collaboration activity highlights how the industry is adapting to these supply-side realities. Nayax and Tritium announced a global partnership designed to simplify payment enablement for EV chargers. By connecting hardware providers with payment and transaction infrastructure, such arrangements aim to reduce one of the persistent operational pain points: fragmented payment experiences that complicate utilization and revenue reconciliation. In parallel, deployment partnerships are expanding physical networks in targeted corridors. Kempower and Blink Charging, for example, moved forward with a multi-site DC fast charging expansion along the U.S. East Coast, leveraging high-power hardware to strengthen coverage in high-traffic regions. These types of initiatives reflect a market that is increasingly comfortable combining hardware, software, and site development expertise rather than pursuing isolated product launches.
Competitive Landscape and Leading Strategies
The competitive field spans established network operators, hardware specialists, energy technology companies, and regional manufacturers. ChargePoint has built a presence around charging stations and network management solutions spanning home, commercial, and fleet applications, positioning itself around software-enabled session management and broader ecosystem connectivity. Enphase has moved into bidirectional charging, supporting vehicle-to-home and vehicle-to-grid integration that links electric vehicles more tightly with distributed energy resources. This direction points toward a future where chargers function not only as energy consumers but as controllable assets within broader home and grid energy flows.
Other manufacturers are differentiating through durability, compatibility, and targeted use cases. Grizzl-E has emphasized rugged level 2 chargers with multiple connector compatibilities and a domestic manufacturing footprint, participating actively in regional industry events to reinforce brand visibility and dealer relationships. Emporia Energy has focused on smart level 2 chargers with load-balancing and energy monitoring, appealing to users who want visibility into consumption and coordination with household electrical loads. EVOIQO and Apex Charger have concentrated on practical level 2 offerings with flexible installation options and connector-specific designs, addressing residential and light commercial buyers who value straightforward specifications and deployment simplicity.
In the higher-power segment, Tritium and ZEROVA illustrate distinct approaches to fast charging. Tritium’s platform orientation emphasizes modular DC fast charging for public and fleet contexts, while ZEROVA has targeted high-power commercial and fleet applications with substantial output capabilities. The strategic implication is that fast charging is not a single market but a set of segmented requirements: corridor hubs, fleet depots, retail fueling equivalents, and destination sites all place different demands on power delivery, canopy design, electrical service, and maintenance models.
The market structure is evolving through a mix of consolidation, partnership, and specialization. Moderate concentration at the top suggests that scale alone has not yet produced a dominant monopoly-style landscape. Instead, competitive advantage is being built through several overlapping strategies. One is ecosystem integration, where charging hardware is paired with network software, payment services, and energy management features. Another is regional proximity and supply chain resilience, which matters more as domestic content expectations and program eligibility rules tighten. A third is application-specific engineering, where winners design products for clearly defined operational profiles rather than attempting to serve every segment with a single platform.
Trade presence and targeted partnerships are also becoming more important as a signal of execution capability. Grizzl-E’s participation in major industry exhibitions, for instance, reflects the continued relevance of in-person demonstrations, dealer engagement, and hands-on product visibility in a market where installation partners and fleet buyers want to assess build quality, compatibility, and support structures directly. Meanwhile, payment enablement partnerships and multi-site deployment agreements indicate that the industry is moving toward integrated operating models, where hardware reliability, transactional smoothness, and geographic coverage are treated as interconnected commercial priorities.
Forward Outlook: Three Strategic Trends for the Next Three to Five Years
The next phase of market development will likely be defined by integration, standardization, and utilization economics rather than raw charger count alone.
The first trend is the rise of smarter, more interoperable charging networks. As hardware conformance expectations and communication protocols become more firmly embedded in program rules and consumer expectations, chargers that support smooth plug-and-charge interactions, reliable payment processing, and utility-readable data will gain preference. This creates opportunities for manufacturers and service providers that can deliver consistent interoperability across sites and reduce the operational friction that currently depresses utilization in some networks. The commercial opportunity lies in recurring software, maintenance, and energy-management revenue, not just hardware turnover.
The second trend is the continued divergence between residential and commercial deployment pathways. Home charging will remain essential for private vehicle owners, but commercial and public charging will drive a growing share of strategic investment, especially where fleets, high-traffic destinations, and corridor travel converge. Businesses that can optimize commercial sites for load management, peak demand avoidance, and high session throughput will be better positioned to convert infrastructure into dependable operating margins. For residential and light commercial players, the opportunity is in simplifying installation, expanding connector compatibility, and offering intelligent energy features that align with consumer interest in cost visibility and home energy coordination.
The third trend is supply chain and compliance reshaping procurement winners. As domestic content expectations evolve and manufactured product rules become more explicitly aligned with program requirements, suppliers with transparent sourcing, adaptable bill-of-materials strategies, and documentation readiness will face fewer deployment delays. This is especially relevant for federally supported and utility-sponsored programs, where eligibility can determine whether a project moves forward on schedule. Companies that treat compliance as a design and supply-chain function rather than a late-stage paperwork exercise will likely secure more consistent access to capital-intensive deployment pipelines.
PW Consulting
These trends carry risks that decision makers should monitor. Grid capacity and interconnection timelines can constrain site readiness, particularly in areas with rapid deployment interest. Utilization risk remains real in locations where traffic patterns, pricing structures, or payment friction limit session frequency. Regulatory timelines can shift as agencies refine content requirements and program guidance, altering project economics with limited lead time. Finally, hardware reliability and service response continue to influence customer experience and operator reputation; in a market where networks are compared session by session, uptime gaps can translate quickly into lost share.
Actionable Implications for Decision Makers
Different stakeholders face different priority sets, but several strategic moves are broadly relevant.
For hardware and network providers, the priority is to align product roadmaps with operational realities rather than aggregate specifications. That means designing for modular servicing, predictive diagnostics, connector compatibility, and payment interoperability, while also ensuring that supply chains can withstand evolving domestic content expectations. Companies should evaluate whether they compete primarily on hardware performance, network services, energy integration, or geographic coverage, and then build the partnerships necessary to reinforce that position. A clear application focus, supported by reliable installation and service pathways, tends to outperform broad but shallow product portfolios in a market where uptime and user experience drive repeat utilization.
Electric Vehicle Charging App Market
For investors, the opportunity lies in distinguishing between companies that are building durable operating models and those that are relying on short-term subsidy tailwinds or hardware-only economics. Favor businesses that demonstrate recurring revenue potential through software, maintenance, energy management, or transaction services, and that show evidence of compliance readiness and supply chain resilience. Pay attention to deployment partnerships and payment integrations, since these often signal a move toward integrated commercialization rather than standalone product sales. Also weigh regional exposure carefully; markets with strong utility programs, clear procurement rules, and established installation ecosystems will generally outpace fragmented environments where permitting and electrical upgrades slow project velocity.
For commercial buyers and fleet operators, the focus should be on total cost of ownership, session reliability, and site-level energy management rather than sticker price alone. Evaluate charger platforms based on expected utilization profiles, downtime history, remote monitoring capabilities, and the availability of service support in your operating region. Consider how load-balancing, scheduled charging, and potential bidirectional capabilities could reduce demand charges or improve energy flexibility. Engage early with electrical planners and installation partners, because site readiness and interconnection timelines often determine project success more than the choice of charger brand. Where possible, prefer solutions that simplify payment and reporting, since transaction friction frequently undermines utilization and complicates reconciliation across multiple sites.
Why Detailed Intelligence Matters Now
The charging market is moving from rapid qualitative expansion into a more demanding phase where execution quality, regulatory alignment, and utilization economics determine commercial outcomes. In that environment, broad headlines are helpful for orientation but insufficient for planning. Segment-level deployment patterns, regional program eligibility, compliance timelines, and competitor positioning all influence which strategies will hold up under scrutiny. Decision makers who need to prioritize regions, applications, technology paths, or partnership structures benefit from more granular data than a high-level market narrative can provide.
A deeper research resource can help translate these dynamics into specific choices: where to allocate capital, which product segments offer the strongest risk-adjusted opportunity, how regulatory shifts may alter project timelines, and which competitive moves are likely to reshape category leadership. For organizations already operating in the space, that level of detail supports pricing, capacity planning, and go-to-market execution. For those evaluating entry or expansion, it reduces the risk of committing to segments where utilization, compliance, or supply-chain friction is underpriced.
The market trajectory suggests continued scale, but scale alone does not guarantee profitable execution. The companies and investors that perform best over the next several years will be those that treat charging infrastructure as an integrated systems business, align their strategies with evolving rules and user expectations, and base their decisions on segment-level evidence rather than aggregate projections. Detailed research reports can provide the subcategory breakdowns, regional comparisons, and competitive tracking necessary to turn these strategic signals into concrete operational plans and investment committees’ decisions.
For detailed analysis of this topic, please visit the official page: Electric Car Chargers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


