



Particle Size Analyzers Market: Why 6.5% CAGR and Healthcare Demand Shift Strategy Through 2032

Strategic Trends and Commercial Opportunities in the Particle Size Analyzers Market: A PW Consulting Outlook
Market Landscape and Core Challenges
The particle size analyzers market has entered a phase of accelerated expansion, driven by tightening quality control requirements across regulated industries and the growing demand for precise material characterization in pharmaceutical, chemical, and advanced manufacturing applications. Measured in millions of USD, the sector moved from approximately 350.0 in 2020 to an estimated 512.0 in 2025, with a projected compound annual growth rate of 6.5 percent through 2032, when revenue is expected to approach 800. The trajectory reflects a market that has transitioned from steady instrumentation replacement cycles to a broader adoption environment shaped by regulatory scrutiny, miniaturization of analytical workflows, and cross-industry quality standards.
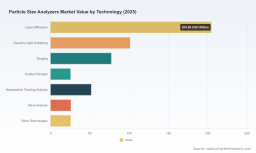
At the macro level, regional demand shows a clear concentration in established industrial and research hubs, with mature pharmaceutical and chemical markets driving consistent procurement volumes. Technology segments remain anchored by laser diffraction as the dominant measurement principle, while complementary methods such as dynamic light scattering, imaging, and nanoparticle tracking analysis continue to expand the addressable use cases in sub-micron and nano-range characterization. End-user demand is similarly structured around sectors where particle attributes directly influence product performance, stability, dissolution behavior, and process efficiency. Healthcare applications represent the largest share of demand, followed by academia, chemicals, and a diversified set of manufacturing sectors including food, cosmetics, and mining. The market remains moderately consolidated, with the top three players accounting for roughly 38 percent of revenue and the top five reaching about 42 percent, indicating that while scale and brand recognition matter, the competitive field still accommodates specialized and regional entrants.
Despite the favorable growth outlook, the market faces three structural challenges that are reshaping commercial strategies:
- Intense capital expenditure scrutiny in healthcare and public-sector laboratories: Particle size analyzers are treated as laboratory capital equipment rather than revenue-generating diagnostic tools. Hospitals and clinical laboratories operate under tight budget envelopes and reimbursement constraints, which prolong procurement cycles and increase competition for available CapEx. This dynamic places pressure on vendors to justify total cost of ownership, service reliability, and workflow integration rather than relying solely on technical performance.
- Standardization, compliance, and costly component requirements: Laser diffraction remains governed by established measurement standards that ensure traceable and repeatable results, but high-end instruments increasingly rely on precision optics and electronics that must meet certified, medical-grade component expectations in regulated pharma and clinical settings. Maintaining ISO certifications, CE marking, and audit-ready documentation adds operational complexity and restricts cost-down strategies, especially for manufacturers serving dual-use markets.
- Competition between performance differentiation and cost-efficient alternatives: The market is not homogeneous. While premium vendors compete on reproducibility, automation, and application-specific support, cost-effective alternatives have expanded reach in laboratory and industrial segments. Buyers in price-sensitive environments are increasingly weighing functional adequacy against brand prestige, forcing incumbents to demonstrate measurable advantages in throughput, operator ease, and integration with broader quality systems.
Key Drivers Shaping Market Dynamics
The growth of the particle size analyzers market is not simply a function of incremental instrument replacement. It is being reshaped by converging forces across technology, regulation, user behavior, and supply economics. Understanding these drivers is essential for assessing where demand will intensify and which commercial models will hold up under scrutiny.
Technology innovation and measurement versatility
Instrument development is moving beyond basic size distribution outputs toward integrated workflows that combine repeatability, automation, and easier interpretation for non-specialist operators. Laser diffraction systems continue to lead because they cover broad size ranges with fast measurement cycles, but the market is also expanding where sub-micron, nanoparticle, and morphological characterization matter. Dynamic light scattering and nanoparticle tracking analysis are gaining relevance for nanoformulations and dispersed systems, while imaging-based methods support morphology and shape factors that size-only outputs cannot capture. These capabilities matter because particle attributes increasingly affect formulation behavior, processing consistency, and downstream performance in complex materials.
PW Consulting
For vendors, the strategic implication is that performance leadership now depends on more than optical precision alone. Automation, sample handling flexibility, software usability, and seamless data traceability are becoming differentiators that influence purchasing decisions, especially where laboratory throughput and compliance documentation are critical. Instruments that reduce operator variability and simplify validation packages can command stronger adoption in regulated settings, even when upfront pricing is higher.
BET Surface Area Analyzer Market
Regulatory expectations and compliance-driven procurement
Regulatory and standardization dynamics play an outsized role in purchase timing, specification requirements, and vendor selection. Laser diffraction measurement practices are anchored by long-standing standards that support traceable and repeatable results, which makes them well suited to pharmaceutical and clinical applications where data integrity is essential. In parallel, major manufacturers maintain CE marking and relevant certifications for instruments used in regulated medical device and pharmaceutical particle characterization. This compliance posture is not a minor detail; it is a procurement prerequisite in many quality-sensitive environments.
At the same time, reimbursement and budgeting realities shape adoption. Particle size analyzers are capital equipment items without dedicated procedural billing codes, so purchasing decisions are strongly influenced by laboratory budget cycles and institutional cost control. The result is a dual dynamic: regulated applications can create durable demand because particle characterization supports quality and process validation, but procurement timing can be delayed or compressed depending on institutional CapEx availability. Vendors that can align their value proposition with audit readiness, documentation support, and predictable service coverage are better positioned to convert technical strength into commercial wins.
Demand-side shifts in formulation, manufacturing, and research
User demand is changing because the importance of particle attributes is rising across multiple end-use sectors. In healthcare and pharmaceutical environments, particle size and distribution can influence dissolution, bioavailability, and consistency of drug products, which reinforces the need for reliable characterization during development and quality control. Academic and research institutions continue to drive demand through fundamental material science, nanomaterial studies, and interdisciplinary programs that require precise sizing across different measurement ranges.
In industrial settings, the motivation is often operational rather than regulatory. Chemical, food, cosmetic, and mineral-processing operations use particle size data to optimize mixing, dispersion, reactivity, flow behavior, and end-product consistency. As manufacturers seek greater process control and reduced variability, the analyzer shifts from a periodic measurement device to a more integral quality assurance tool. This shift expands the value proposition beyond the instrument itself and toward workflow integration, repeat measurement confidence, and support for process decisions.
Supply-side and cost structure pressures
Cost structures in the high-end segment are increasingly shaped by component requirements. Precision optics and electronics in advanced laser diffraction systems often depend on certified, medical-grade components when instruments are deployed in pharma or clinical environments. These requirements constrain aggressive cost reduction and can affect lead times, sourcing flexibility, and service scalability. Meanwhile, in the broader market, regional manufacturers and cost-efficient models are expanding choice for laboratory and industrial users who prioritize functionality and price over premium brand positioning.
This divergence creates an important strategic tension. On one side, compliance and performance requirements support premium pricing and more defensible margins for vendors with strong documentation, service networks, and application support. On the other, price sensitivity in less regulated or more volume-driven segments pressures incumbents to compete on throughput, ease of use, and total cost of ownership. Supply-side strategy therefore matters as much as product performance: sourcing resilience, service coverage, and scalable calibration support can determine whether a product succeeds commercially across regions and customer segments.
Competitive Landscape and Leading Strategies
The market is led by a set of established multinational players with distinct technology portfolios, application focus areas, and geographic strengths. Their strategies reveal how vendors are navigating the tension between premium performance, compliance, and broader accessibility.
Amino Acid Analyzers Market
Malvern Panalytical remains a prominent force in laser diffraction, with a recognized presence in pharmaceutical applications where particle characterization supports drug dissolution and bioavailability studies. Its positioning reflects the broader value of strong brand recognition, application depth, and alignment with regulated workflows. Danaher, through its life sciences portfolio, combines Coulter Principle and laser diffraction systems that serve clinical laboratory and pharmaceutical particle characterization, giving it a strong fit in environments where clinical and quality control demands intersect. HORIBA Scientific offers laser diffraction systems covering sub-micron to larger particle ranges, emphasizing broad measurement versatility for laboratory and scientific use. Anton Paar focuses on laser diffraction analyzers with automation features designed to improve precision and repeatability, an approach that addresses the need for reduced operator variability in controlled environments.
A second layer of competitors illustrates the market's expanding accessibility. Bettersize Instruments, based in China, specializes in cost-effective laser diffraction and dynamic light scattering systems for laboratory and industrial applications, targeting users who require solid measurement capability without premium pricing. Microtrac provides laser diffraction, DLS, and image analysis options for fluid and dry materials, supporting customers who need multi-mode characterization flexibility. Sympatec develops laser diffraction systems oriented toward powders, granules, suspensions, and process monitoring, aligning closely with manufacturing and inline or process-adjacent use cases. Shimadzu supplies particle characterization instruments for laboratory powders and liquids, benefiting from broad scientific instrumentation credibility. Fritsch integrates particle sizing within a wider milling and sizing portfolio, which can be attractive for customers linking sample preparation and analysis. Mettler Toledo incorporates particle size analyzers into automated characterization offerings for laboratory and process use, reinforcing a workflow-oriented value proposition. Scitek Global, also from China, offers lab and medical equipment including particle size analyzers with ISO 13485 certification, a compliance signal that can matter in regulated procurement environments.
These profiles show a market where differentiation is no longer defined solely by measurement method. Leading positions are increasingly tied to application support, software usability, compliance documentation, service reach, and the ability to serve both development and quality control needs. Vendors that can bridge laboratory characterization and process-relevant insights gain an advantage in sectors where particle data must inform operational decisions, not just generate reports.
The competitive landscape is evolving along three trajectories:
- Consolidation pressure among mid-tier and regional players: As buyers demand broader support, calibration, and service coverage, smaller vendors face mounting pressure to scale service infrastructure or partner for distribution. This favors larger players with existing institutional relationships and multi-channel support, while creating opportunities for acquisitions that add geographic coverage or complementary technologies.
- Differentiation through workflow integration and software: Hardware performance remains essential, but commercial advantage is shifting toward automation, data handling, and traceability features that reduce burden in regulated environments. Systems that simplify validation, reporting, and multi-user operation are better positioned to withstand procurement scrutiny.
- New entry and niche expansion in specific measurement ranges and applications: Demand for nano-range characterization, dispersed systems, and specialized sample types continues to create openings for focused entrants. Rather than challenging leaders across the full instrument spectrum, new players often compete by targeting specific size ranges, sample formats, or regional price points with credible certification and application support.
Future Trends and Strategic Opportunities (2026–2032)
The next several years are likely to be shaped by how the market balances performance, compliance, cost, and workflow value. Three trends stand out as particularly consequential for commercial planning.
1. Wider adoption of automated, workflow-oriented analyzers in regulated environments
As laboratories face staffing constraints and greater documentation demands, instruments that reduce operator dependence and improve measurement repeatability will gain traction. Automation in sampling, cleaning, data export, and reporting can lower total cost of ownership by improving throughput and reducing error-related rework. This trend is especially relevant in pharmaceutical and clinical-adjacent settings, where compliance-ready documentation and consistent results support validation and audit processes. Commercial opportunity lies not only in instrument sales but in bundled offerings that include service, training, software updates, and compliance support. The risk is that automation claims must be backed by demonstrable reliability and service coverage; otherwise, perceived complexity can slow adoption.
2. Growing demand for multi-method and application-specific characterization solutions
Particle characterization needs are becoming more diverse as materials and formulations grow more complex. Some applications require broad dynamic range, others need nano-scale sensitivity, and still others benefit from shape or morphology information. This is likely to increase demand for vendors that can offer method flexibility or integrate complementary techniques within a coherent workflow. For end users, the appeal is faster method selection, fewer handoffs between instruments, and more interpretable results for specific applications. For vendors, the opportunity is to position instruments as part of an application solution rather than as standalone measurement boxes. The uncertainty is that cross-method integration can raise cost and support complexity, so success will depend on clear use-case targeting rather than broad but shallow capability claims.
3. Intensifying competition between premium performance and cost-efficient access
Market growth is likely to broaden access to particle characterization in emerging industrial and regional markets, where cost sensitivity and practical usability may outweigh premium brand value. At the same time, regulated and performance-critical applications will continue to reward vendors with strong compliance credentials, service depth, and demonstrated reproducibility. This bifurcation creates a strategic choice for companies: compete premium or compete broadly. The more profitable path may be a segmented strategy that protects high-margin regulated positions while using targeted cost-efficient models to capture volume in less regulated sectors. A key risk is brand erosion if premium positioning is diluted without clear differentiation, or if cost-focused models cannot sustain service and calibration quality over time.
Actionable Guidance for Decision-Makers
The commercial implications of these trends vary by role, but a common theme is that purchasing and competitive decisions increasingly hinge on total workflow value, compliance readiness, and service sustainability rather than on measurement capability alone.
For manufacturers and technology providers
- Prioritize differentiation through automation, software usability, and documentation support that reduces burden in regulated settings. Technical excellence matters, but repeatable workflows and audit-ready outputs often decide procurement outcomes.
- Segment the portfolio deliberately. Use premium, compliance-oriented offerings for pharmaceutical and clinical-adjacent demand, while developing credible cost-efficient options for broader laboratory and industrial segments without compromising support quality.
- Strengthen service, calibration, and regional coverage. In a market where CapEx approval is cyclical and compliance expectations are high, long-term customer value depends heavily on post-sale support and sourcing resilience for precision components.
For investors and strategic planners
- Focus on business models that combine instrument revenue with recurring service, software, and application support, since these elements can improve resilience through budget-constrained procurement cycles.
- Watch for consolidation signals among regional and mid-tier players, especially where scale in service distribution, certification coverage, or application breadth becomes a competitive requirement.
- Evaluate exposure to regulated end-use demand carefully. While pharmaceutical and healthcare applications can sustain premium positioning, purchasing timing may be sensitive to hospital and laboratory budget cycles, which can affect short-term revenue visibility even when long-term demand remains strong.
For procurement leaders and laboratory operators
- Evaluate total cost of ownership, not just purchase price. Consider measurement repeatability, operator training burden, service response time, and documentation support, especially where compliance and throughput matter.
- Define application requirements clearly before sourcing. The “best” instrument depends on sample type, size range, throughput needs, and regulatory context, and over-specifying or under-specifying can create unnecessary cost or performance gaps.
- Request evidence of workflow fit and support capability. References, validation support, and service coverage may be as important as performance specifications when procurement must justify capital allocation within institutional budget constraints.
The strategic picture is clear: the particle size analyzers market is expanding under the influence of regulatory expectations, workflow automation, and broader application demand, but it is also becoming more segmented and more service-dependent. Companies that understand where compliance, cost, and performance intersect will be best positioned to capture durable demand, while buyers who evaluate instruments as part of a broader quality workflow will make more resilient procurement decisions. For decision-makers seeking detailed segmentation data, regional demand patterns, and customized competitive scenarios across technologies and end users, a full research report can provide the deeper quantitative context needed to translate these trends into precise commercial planning.
For detailed analysis of this topic, please visit the official page: Particle Size Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


