



CVT Market 2026-2032: Decoding the 4.5% CAGR Surge and Key Segment Dynamics

Navigating the Continuously Variable Transmission Market: Strategic Shifts and Commercial Opportunities
The global automotive transmission landscape is undergoing a quiet but consequential transformation. Continuously Variable Transmissions (CVTs) have moved from a niche alternative to a mainstream powertrain choice, driven by endurance efficiency mandates, shifting consumer expectations, and relentless refinement in mechanical design. The market has steadily expanded from approximately $15.6 billion in 2020 to $18.65 billion in 2025, settling into a forecasted compound annual growth rate of 4.5 percent through 2032, when it is projected to reach $25.65 billion. This trajectory is not linear, nor is it guaranteed. It reflects a sector balancing mechanical optimization against electrochemical disruption, regulatory pressure against supply chain fragility, and established dominance against emerging competitive architectures. Understanding where the CVT market stands today, what forces are bending its trajectory, and how incumbents are positioning themselves offers practical guidance for executives, investors, and procurement leaders navigating the next cycle of powertrain strategy.
Worldwide Hydrostatic Transmission Market
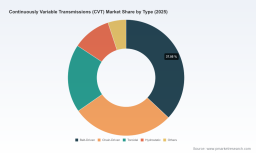
The current market structure reveals both maturity and vulnerability. CVT technology now accounts for a meaningful share of light vehicle powertrains, with belt-driven systems commanding the largest typology share, chain-driven variants holding a substantial secondary position, and toroidal and hydrostatic configurations serving specialized niches. Passenger cars remain the dominant application, while light and heavy commercial vehicles contribute incremental but strategically important volumes. Geographically, the market is distributed across mature and emerging regions, with North America and the Asia Pacific region anchoring the largest revenue pools, Europe maintaining steady demand, and Latin America and the Middle East and Africa representing smaller but growing footprints. This broad distribution masks a highly concentrated competitive environment. The top three players control more than half of market revenue, and the top five extend that share past sixty percent, underscoring the advantage of scale, proprietary manufacturing experience, and long-term procurement relationships. Concentration is not merely a statistical observation; it shapes pricing power, innovation pacing, and the barriers that new entrants must clear.
Concentrated Leadership and Structural Fragility
The market operates under a dual reality. On one side, scale players benefit from accumulated learning curves, volume-driven component sourcing, and deep integration with vehicle manufacturers who value predictable pricing and validated reliability. On the other side, the sector remains exposed to component-specific supply constraints, manufacturing cost sensitivity, and the ever-present question of whether internal combustion efficiency improvements will ultimately be overtaken by electrification trajectories. These forces do not cancel each other out; they interact. A firm that has mastered belt-pulley dynamics and launch-gear integration can extract better fuel economy and smoother acceleration, but if the global supply chain for specialized steel push-belts and precision-machined pulleys experiences disruption, production schedules slip and unit costs rise. The result is a market that rewards disciplined operational execution as much as mechanical ingenuity.
Key Challenges and Inflection Points
Three challenges dominate strategic discussions. The first is cost and reliability perception. While modern CVT designs have improved markedly, earlier generations left a residual impression among some consumers and fleet operators. Addressing that perception requires sustained refinement in durability, thermal management, and packaging efficiency, all of which translate directly into warranty exposure and brand trust. The second challenge is regulatory uncertainty intertwined with compliance economics. Regulatory bodies continue to model transmission cost and efficiency at a granular level, and CVT manufacturing cost estimates have been adjusted through learning curve factors in recent compliance demonstrations. Simultaneously, earlier planning scenarios projected minimal CVT penetration under certain compliance pathways, highlighting how regulatory modeling can influence OEM architecture choices. The third challenge is the tension between incremental internal combustion optimization and the broader shift toward electrification. CVTs can improve fuel economy and help automakers meet Corporate Average Fuel Economy standards and emissions targets, but their long-term role must be evaluated against hybrid, plug-in hybrid, and battery electric architectures. This tension is not a binary conflict; it is a strategic calibration problem that requires understanding where CVTs deliver the greatest marginal benefit and where alternative solutions will outcompete them.
The Resilience-And-Recalibration Paradox
The practical implication for decision makers is that the CVT market is not a single trend line but a portfolio of outcomes. Passenger car adoption continues to benefit from smoothness and fuel economy, commercial applications are expanding where torque delivery and efficiency matter, and specialty architectures remain important for specific duty cycles. Yet all of these segments must contend with component availability, cost discipline, and the credibility of the underlying mechanical design. Companies that manage these trade-offs well are not simply selling transmissions; they are selling validated reliability, predictable total cost of ownership, and regulatory alignment. That is the real competitive currency in this market.
Key Drivers Shaping Market Trajectory
Market growth is not speculative; it is being pulled by identifiable forces that interact across technology, regulation, demand, and supply. The strongest drivers are not isolated innovations but layered dynamics that reinforce one another, making the market more attractive to scale players while simultaneously raising the bar for new entrants.
Technical Refinement as a Competitive Multiplier
Continuous improvement in CVT architecture has shifted the conversation from basic functionality to refined performance. Launch gears, wider ratio ranges, reduced friction losses, and enhanced thermal durability have addressed historical concerns about acceleration response and reliability. These refinements matter because they convert a transmission technology into a brand-level asset. A CVT that delivers seamless operation and strong fuel efficiency becomes a selling point in passenger car lineups, while a robust, torque-tolerant design supports commercial vehicle applications where uptime and operating cost are paramount. The mechanical evolution also has a learning curve effect. As cumulative production volumes rise, manufacturing knowledge deepens, tolerances tighten, and unit economics improve. This is precisely why regulatory and industry analyses continue to apply learning curve factors to cost estimates; the trajectory of cost reduction is tied to output and experience, not to static assumptions. The strategic implication is clear: companies with sustained volume and disciplined process control can lower costs faster and pass through competitive pricing or reinvest in further refinement, creating a virtuous cycle that is difficult for low-volume players to replicate.
Regulatory Pressure and Emissions Strategy
Fuel economy standards and emissions targets remain a powerful structural driver. CVTs contribute directly to compliance strategies by enabling engines to operate closer to optimal efficiency across a wider range of vehicle speeds and loads. This makes them relevant not only for consumer perception but for fleet-average compliance economics. At the same time, regulatory documentation continues to provide granular insights into transmission cost, market penetration assumptions, and compliance scenarios. These documents are not mere paperwork; they influence how automakers model portfolio trade-offs, how suppliers anticipate volume commitments, and how investors assess the durability of transmission demand under different compliance regimes. A market participant that understands the interplay between efficiency mandates, compliance cost modeling, and vehicle architecture choices gains an early-warning advantage when regulatory expectations shift or when specific scenarios reweight the attractiveness of CVTs relative to alternative transmissions.
Demand-Side Behavior and Commercial Uptake
Consumer and commercial demand is moving along two tracks. In passenger vehicles, drivers value smoothness, quiet operation, and fuel economy, and manufacturers have leaned into these attributes in widely sold models. In commercial segments, the calculation is more functional: torque delivery, durability, serviceability, and total cost of ownership drive adoption. The commercial track is especially important because it tends to be less fashion-driven and more performance-driven, making it a stabilizing demand base when consumer taste cycles fluctuate. Additionally, commercial adoption often benefits from fleet-scale procurement and longer lifecycle evaluations, which means winners in this segment can secure recurring volume and deeper integration with operating economics. The broader demand signal is therefore dual-polarized: consumer-facing value propositions build volume and brand relevance, while commercial applications build revenue stability and engineering credibility.
Supply Chain Realities and Cost Structure
No discussion of demand and regulation is complete without addressing the physical supply chain. CVT systems depend on specialized global sourcing for steel push-belts, pulleys, and precision components. This dependence creates both leverage and vulnerability. When supply is stable and scale is high, manufacturers can achieve competitive pricing and dependable delivery. When disruptions occur, production schedules are affected and costs rise, sometimes with cascading effects on OEM build plans. Cost structure, therefore, is not just a function of design efficiency; it is also a function of supply continuity, logistics resilience, and multi-sourcing strategy. Companies that treat the supply chain as a strategic asset rather than a transactional input are better positioned to absorb shocks and preserve margin. This is a practical differentiator that often matters more in day-to-day competitiveness than marginal improvements in marketing position.
Competitive Landscape and Leader Strategies
The CVT market is defined by a concentration of capability among a small group of manufacturers and vehicle makers who have built long-standing technical and contractual relationships. The competitive story is less about scattered experimentation and more about deepening expertise, expanding application breadth, and defending reliability perceptions through sustained product refinement.
Japanese Leadership and Differentiated Positioning
Japanese firms continue to anchor the sector. One transmission specialist has built a leading global market share in CVT technology, with product lines such as CVT-X, CVT-XS, and CVT-S for front-wheel-drive vehicles, and a business model centered on design, development, manufacture, and sale of CVT systems. Its strategic advantage lies in vertical focus and a broad application portfolio that can serve multiple OEM platforms. Another major supplier develops and supplies advanced CVT systems for passenger cars, including models equipped with launch gear to improve fuel efficiency and acceleration response. Its differentiation is engineering integration, especially where launch performance and efficiency must coexist. On the automaker side, several large Japanese brands have embedded CVTs deeply into their lineups. One producer offers its Xtronic CVT across models such as Rogue, Sentra, and Altima, and has continued refining reliability and performance through successive generations. Another incorporates CVTs in widely recognized models for seamless operation and fuel efficiency. A third utilizes its Lineartronic CVT across models such as Forester, Crosstrek, and Outback for efficient power delivery and drivability. The common strategic thread is not mere adoption but sustained optimization: each brand uses the CVT as part of a broader value proposition that ties efficiency, ride quality, and model-specific tuning together.
Worldwide Hybrid Dual-Clutch Transmission Market
Evolution of the Field: Consolidation Depth and Niche Expansion
The competitive field is evolving along two tracks. The first is deepening consolidation among scale players who can amortize engineering, tooling, and supply chain commitments over large volumes. High market concentration means that incumbents already control much of the learning curve, supplier relationships, and customer qualification process. New entrants face not just a technical hurdle but an institutional one: OEMs prefer proven durability, predictable supply, and validated warranty performance. The second track is differentiation within specialized applications and architectures. Toroidal, hydrostatic, and other configurations remain smaller in volume, but they matter where specific torque, speed, or duty-cycle requirements make belt-driven or chain-driven designs less suitable. The opportunity here is not to challenge the dominant architectures head-on, but to own a credible position in segments where mechanical requirements or operating conditions reward alternative designs. This is a classic concentration-plus-niche dynamic: scale players defend the mainstream, while specialists preserve optionality and option value in targeted applications.
Recent Market Signal: Confidence Through Refined Reliability Messaging
A telling recent signal is the emphasis on decades of refinement and improved reliability in updated model-year content. In mid-2025, one major automaker released refreshed messaging highlighting twenty years of CVT improvements and the enhanced reliability of its CVT across 2025 and 2026 models such as the Rogue. This kind of communication is strategically meaningful. It does more than promote a product; it attempts to reset a reliability narrative that has lingered in consumer and fleet perception, and it ties mechanical refinement to model-year continuity. From a competitive standpoint, it signals that leading players understand the market is won as much on trust and durability as on efficiency claims. It also suggests that incumbents are actively managing the perception gap as a core part of their go-to-market strategy, not leaving it to dealer networks or word of mouth.
What This Means for Positioning and Entry
For existing leaders, the priority is to protect scale advantages while continuing to improve launch performance, thermal durability, and packaging flexibility. For suppliers, the priority is to integrate more tightly with OEM calibration and vehicle-level efficiency goals, because CVTs are increasingly evaluated within the full powertrain system rather than as standalone components. For potential new entrants, the realistic path is not to commoditize the mainstream but to address underserved niches, alternative architectures, or regional supply gaps where specificity and responsiveness can outweigh scale. The market does not reward generic entry; it rewards credible specialization backed by engineering discipline and supply reliability.
PW Consulting Automotive & Machinery Research Center
Future Trends and Commercial Opportunities
Predicting the next three to five years of the CVT market requires reading the interaction of technical momentum, regulatory direction, supply resilience, and the broader electrification debate. The trends that matter are not isolated forecasts; they are conditions that reshape where value is created.
Efficiency-as-Standard, Reliability-as-Differentiator
The first trend is the normalization of efficiency and the elevation of reliability into a competitive differentiator. As consumers and fleets become more familiar with CVTs, the baseline expectation will shift from novelty to dependability. Companies that can consistently deliver smooth operation, low noise, and durable performance will capture disproportionate trust and repeat adoption. This trend opens commercial opportunities in warranty-optimized design, improved thermal management, and better service diagnostics, all of which can reduce total cost of ownership and strengthen brand confidence. It also suggests that communications around reliability will remain a strategic lever, especially as new model years refresh the narrative and older concerns fade.
Commercial and Specialty Applications as Growth Anchors
The second trend is the incremental but strategically significant expansion of commercial and specialty applications. While passenger cars will continue to drive volume, commercial vehicles and niche architectures offer stability and higher willingness to pay for functional performance. This is where CVTs can build recurring demand that is less sensitive to consumer taste cycles and more aligned with operational economics. The opportunity lies in tailoring designs to specific duty cycles, improving torque handling and serviceability, and positioning CVTs as part of a broader commercial vehicle efficiency strategy. Companies that treat these applications as afterthoughts will miss a valuable anchor; those that invest in application-specific engineering can create defensible positions and longer contract cycles.
Regulatory Modeling and Portfolio Calibration
The third trend is the growing importance of regulatory modeling in portfolio decisions. Compliance documentation continues to provide detailed estimates of transmission cost, penetration assumptions, and scenario-based outcomes. These documents influence how automakers plan architectures and how suppliers anticipate commitment levels. The commercial opportunity here is foresight: firms that can interpret regulatory trajectories, translate them into volume and cost expectations, and align their product roadmaps accordingly will be better positioned to capture demand when scenarios shift in favor of CVTs, and to protect margins when alternative architectures gain relative weight. This is not about betting on a single future; it is about building optionality and responding quickly to changes in compliance expectations.
Risks and Uncertainties to Watch
No forecast is complete without identifying where the model could break. The most immediate risk is supply chain disruption in specialized components, which can affect production continuity and unit cost. A second risk is the ongoing recalibration of electrification strategies, which could alter the relative attractiveness of internal combustion optimization in certain segments. A third risk is perception persistence: if reliability concerns resurface in high-mileage or extreme-duty conditions, brand trust can erode quickly, reversing some of the gains made through product refinement. A fourth risk is regulatory assumption shifts, where modeling scenarios change how CVT penetration is projected under different compliance pathways. Each of these risks is manageable, but only if firms monitor the signals early and build flexibility into sourcing, product design, and portfolio planning.
Strategic Playbook for Decision Makers
The CVT market rewards participants who combine technical credibility with operational discipline and regulatory awareness. The most useful actions are not generic; they are tailored to the role each organization plays in the value chain.
For Manufacturers and Suppliers
- Double down on reliability as a marketable asset. Invest in durability validation, thermal management, and launch performance, and align product messaging with model-year continuity to strengthen consumer and fleet trust.
- Treat the supply chain as a strategic moat. Develop multi-source strategies for critical components, maintain buffer capacity for specialized steel push-belts and pulleys, and coordinate logistics resilience with OEMs to reduce exposure to disruption.
- Expand application-specific engineering where it pays. Focus development on commercial and specialty segments that value torque, duty-cycle performance, and serviceability, and use these segments to stabilize volume and reinforce engineering credibility.
For Investors
- Assess scale and learning curve advantages rather than headline growth alone. Concentration, cumulative production experience, and supplier integration often determine who can sustain cost improvement and margin stability.
- Monitor compliance modeling signals closely. Changes in regulatory assumptions, cost estimates, and penetration scenarios can shift portfolio preferences more quickly than product trends, and early interpretation can create timing advantages.
- Look for durable demand anchors in commercial and specialty applications, where functional value and total cost of ownership can support recurring volume even as consumer preferences fluctuate.
For Procurement and Fleet Decision Makers
- Evaluate CVTs within the full operating context, not just on efficiency claims. Consider warranty performance, serviceability, supplier continuity, and total cost of ownership across the expected vehicle lifecycle.
- Request evidence of durability and reliability improvements, especially for higher-mileage or commercial use, and align procurement criteria with the reliability narrative that manufacturers are actively reinforcing in current model years.
- Build procurement flexibility around specialized components and delivery continuity to reduce exposure to supply disruptions that can affect uptime and operating cost.
The strategic takeaway is that the CVT market is advancing through disciplined refinement, regulatory alignment, and selective application expansion, not through indiscriminate growth. The companies that will capture the most value are those that understand this nuance and act on it: improving reliability, protecting the supply chain, and positioning CVTs where they deliver the strongest marginal benefit. For leaders who need to go beyond directional trends and make precise decisions on segment allocation, cost modeling, supplier selection, or product roadmaps, detailed segmentation data and customized analysis are available in the complete PW Consulting report on the Continuously Variable Transmission market.
For detailed analysis of this topic, please visit the official page: Continuously Variable Transmissions (CVT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


