



Cochlear Implants Market: Why 7.5% CAGR Growth and $3B Valuation Reshape 2032 Strategy

Strategic Shifts and Commercial Opportunities in the Cochlear Implants Market
Market Overview: Scale, Growth, and the Emerging Equilibrium
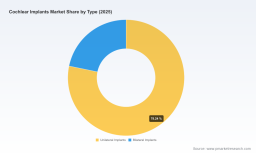
The global cochlear implants market has entered a phase of steady expansion, underpinned by advancements in implant technology, broader clinical indications, and sustained reimbursement support across major healthcare systems. Valued at approximately 1,280.0 million USD in 2020, the market has progressed through consistent year-over-year gains to reach an estimated 1,850.0 million USD in 2025. Over the 2020-2025 historical period, growth reflects both volume expansion and incremental pricing power tied to product innovation. Looking ahead, the trajectory is expected to accelerate modestly, with the market projected to reach 3,064.02 million USD by 2032, translating to a compound annual growth rate of 7.5 percent across the 2026-2032 forecast window.
PW Consulting
This growth path is not uniform. The pace of adoption is increasingly shaped by the interaction of clinical evidence, device capabilities, and reimbursement stability rather than raw demographic demand alone. Market concentration remains pronounced, with the top three players accounting for 62.0 percent of total revenue and the top five representing 85.0 percent. Such concentration signals a mature competitive order, yet the underlying dynamics are shifting as technology differentiation, geographic expansion, and regulatory flexibility create space for strategic repositioning.
For executives and investors, the central implication is that growth in this space will be earned through differentiation and access, not simply through volume. The companies and capital that navigate the technical and commercial inflection points effectively will capture disproportionate value as the market expands toward the 3 billion USD threshold.
Key Challenges and Inflection Points
Despite the favorable growth backdrop, the market is confronting a set of structural challenges that will define competitive outcomes over the next several years. Three stand out as particularly consequential.
1. The Technology-Reimbursement Tension
Device capabilities are advancing rapidly, with smart implant platforms, firmware-upgradeable architectures, and expanded pediatric candidacy reshaping clinical value propositions. At the same time, reimbursement frameworks remain stable but not infinitely elastic. The persistence of established coding and coverage structures provides predictability for providers and patients, but it also places a ceiling on how quickly premium pricing can be transferred through the system. Manufacturers that introduce higher-cost, feature-rich platforms must demonstrate differentiated outcomes and total-cost-of-care advantages to secure broad adoption without triggering payer resistance.
2. Geographic Adoption Asymmetry
Demand is not materializing at the same pace across regions. Mature markets benefit from established clinical pathways, higher awareness, and favorable reimbursement, while emerging regions face a combination of access barriers, cost sensitivity, and unevenly distributed surgical capacity. This asymmetry creates both a growth opportunity and a commercial risk: companies that can adapt product portfolios, service models, and pricing to lower-threshold markets can unlock volume, but generic expansion without local clinical and reimbursement strategy often underperforms.
3. Competitive Moats Under Pressure from Programmatic Procurement
The participation of major implant systems in government volume-based procurement programs introduces a new dimension of price competition in large addressable markets. While such programs can expand access and stabilize volume, they also compress margins and reward scale, supply-chain efficiency, and local partnerships. Incumbents with strong clinical heritage must now balance their differentiation narrative against the reality of organized price discovery in key public procurement environments.
Core Growth Drivers
Technology Innovation and the Shift Toward Upgradable Platforms
One of the most significant drivers of commercial momentum is the transition from static implant systems to architectures that support post-implant enhancement. The approval of the Nucleus Nexa System as the world's first smart cochlear implant with firmware upgrade capability marks a notable change in how value can be delivered over the device lifecycle. Rather than relying solely on surgical revision to access newer capabilities, this model opens the door to ongoing performance improvements, feature additions, and potentially longer effective device longevity. For clinicians and patients, the appeal lies in future-proofing the implant; for manufacturers, it creates a platform narrative that can support both initial adoption and long-term engagement.
At the same time, expansion of pediatric candidacy is broadening the addressable population. Recent regulatory progress allowing implantation for children from 7 months of age onward with bilateral sensorineural hearing loss extends the intervention window earlier in development, which can strengthen the clinical case for timely cochlear implantation. Earlier intervention aligns with longstanding optimization arguments in pediatric hearing care, and it gives manufacturers a stronger foundation to engage pediatric centers and referral networks.
Stable Policy and Reimbursement Foundations
A second driver is the durability of the reimbursement and coding environment in key markets. The continued effect of the relevant cochlear device implantation code without revision supports billing predictability for providers, while sustained coverage under national framework decisions maintains a stable pathway for patient access. This stability does not eliminate pricing pressure, but it reduces one category of uncertainty that often slows adoption in medical device markets. In practical terms, it allows manufacturers and healthcare providers to invest in program development, surgeon training, and patient identification with greater confidence that the procedural and coverage basis will remain in place.
Demand-Side Evolution: Earlier Intervention and Broader Candidacy
Demand is being reshaped not only by technology but by clinical behavior. The combination of smarter implant platforms and wider pediatric indications encourages earlier referrals and more aggressive candidacy assessment. As clinical confidence grows around earlier intervention and long-term outcomes, the pool of eligible patients expands beyond the traditional severe-to-profound loss segment. This shift is especially relevant in pediatric care, where timing can influence language development and educational trajectories, and in adult populations, where evolving expectations around auditory performance and connectivity are raising the bar for what patients consider an acceptable outcome.
Supply Chain, Cost Structures, and Programmatic Access
A third driver is the reorientation of cost structures around scale and public procurement. Participation in volume-based procurement programs can lower per-unit pricing but also secures volume commitments and broadens access in large markets. For manufacturers, this dynamic rewards operational efficiency, disciplined cost management, and the ability to sustain quality while competing on program terms. It also encourages strategic positioning around local service, training, and aftercare, since procurement wins often depend on more than the implant itself. In this environment, cost structure is not merely an internal efficiency issue; it is a market-access strategy.
Competitive Landscape and Leading Strategies
The market's concentration profile reflects the strength of established incumbents, but the strategic playbooks differ in ways that matter for future positioning.
Cochlear Limited: Platform Leadership and Smart Implant Differentiation
Cochlear has built its position on a broad implant and bone conduction portfolio, and its recent smart implant milestone reinforces a platform-oriented strategy. By delivering an FDA-approved system with firmware upgrade capability, Cochlear is emphasizing lifecycle value rather than a one-time device transaction. This approach supports clinicians who want to offer patients a more future-ready solution and gives the company a narrative that ties innovation to long-term patient engagement. The strategic advantage here is differentiation through architecture: if upgradability becomes a standard expectation, early leaders in this category can shape procurement criteria and clinical preference.
MED-EL: Pediatric Expansion and Indication Breadth
MED-EL's recent FDA approval expanding pediatric candidacy for children 7 months and older illustrates a strategy centered on indication breadth and early-life intervention. By extending the addressable pediatric population, MED-EL strengthens its relevance in one of the most clinically important and referral-sensitive segments. The broader implication is competitive: as more companies secure expanded pediatric indications, the market may see intensified activity around early identification programs, family engagement, and center-level partnerships. MED-EL's positioning suggests that indication expansion can be as commercially meaningful as hardware features when it opens a clearer path to earlier adoption.
Advanced Bionics: Scale, Procurement Alignment, and Portfolio Breadth
Advanced Bionics, supported by Sonova's broader hearing care ecosystem, demonstrates a different form of strength: alignment with large-scale public procurement and a diversified processor portfolio. Selection for China's volume-based procurement program highlights the importance of being competitive in organized purchasing environments while maintaining a credible clinical and product narrative. In practical terms, this positions the company to capture volume in markets where programmatic access is a decisive factor. The strategic lesson is that scale and procurement readiness can be just as important as feature leadership in certain geographies, especially where public spending shapes adoption.
How the Landscape Is Evolving
The competitive order is not static. Several trends are shaping its evolution:
- Differentiation is moving from device-only features to lifecycle and service value, including firmware upgradability, patient engagement, and clinical support.
- Pediatric and early-intervention indications are becoming a contested ground, with regulatory wins translating into center-level influence and referral momentum.
- Programmatic procurement is introducing structured price competition in major markets, rewarding scale, cost discipline, and local ecosystem partnerships.
- Geographic expansion remains a source of growth, but success increasingly depends on adapting to local reimbursement, surgical capacity, and pricing expectations rather than relying on global product uniformity.
For new entrants, the bar is high givenconcentration, but niches exist around specialized candidacy segments, regionally tailored access models, and complementary technologies that enhance outcomes or lower total cost of care. Consolidation is possible where scale and procurement readiness matter most, while fragmentation may persist in segments where clinical specialization and local relationships drive decisions.
Future Trends and Commercial Implications
Trend 1: Lifecycle Value Becomes a Purchase Criterion
As upgradable and smart implant platforms gain regulatory acknowledgment and clinical traction, procurement and clinical decisions may increasingly weigh post-implant enhancement potential. This shift creates opportunities for manufacturers that can credibly support firmware-based improvement, remote management compatibility, and long-term performance assurances. It also raises the stakes for companies whose portfolios remain oriented around static device value, since the comparison set may gradually move toward total lifecycle benefit rather than initial specification alone.
Dental Implants Market
The associated risk is that lifecycle claims must be substantiated with evidence and supported by manageable cost models. If payers or providers perceive upgradability as a source of added cost without clear outcome advantages, the premium may be difficult to sustain.
Trend 2: Earlier Pediatric Intervention Drives Referral and Program Competition
Expanded pediatric candidacy is likely to intensify competition for early identification pathways, family counseling, and center-level adoption. The commercial opportunity lies in building robust referral networks, supporting screening and diagnostic workflows, and demonstrating that earlier implantation can deliver meaningful developmental and educational value. Over the next three to five years, companies that invest in pediatric program enablement may see stronger repeat engagement and more resilient center relationships.
The uncertainty here is clinical and operational: earlier candidacy must be matched by appropriate patient selection, surgical capacity, and follow-up infrastructure. If capacity lags behind indicated demand, adoption may be uneven and program performance could vary by region.
Trend 3: Programmatic Procurement Reshapes Pricing and Access in Large Markets
Volume-based procurement and similar mechanisms are likely to remain influential where governments seek to broaden access while managing expenditure. This trend favors organizations that can combine competitive unit economics with reliable service, training, and supply assurance. It also encourages portfolio strategies that can perform on both clinical differentiation and program economics. For investors and executives, the implication is that revenue growth in these markets may come with margin discipline, making operational execution a strategic differentiator.
The downside risk is that procurement-driven pricing can pressure returns if not offset by volume scale, cost efficiencies, or value-added services. Companies that cannot adapt their cost structures or local operating models may find their market share vulnerable even when their clinical reputation remains strong.
Strategic Recommendations for Decision Makers
For Manufacturers and Commercial Leaders
Prioritize lifecycle differentiation and indication expansion as parallel growth levers. Firmware-upgradable platforms, stronger pediatric candidacy, and robust center support can reinforce both initial adoption and long-term value. At the same time, prepare for programmatic procurement by strengthening cost structure, supply reliability, and local partnership capabilities. In practical terms, product strategy and market-access strategy should be developed together rather than sequentially.
For Investors and Capital Allocators
Look beyond top-line growth and assess how companies are positioned for the three forces shaping the market: lifecycle value, pediatric indication breadth, and procurement-driven pricing. The most resilient business models will likely combine credible differentiation with operational discipline and the ability to win in organized purchasing environments. Evaluate exposure to regions where adoption asymmetry can be addressed through tailored access strategies, and consider whether a company's roadmap aligns with the direction of clinical and regulatory change.
For Providers, Procurement Teams, and Health System Leaders
Evaluate implant choices with a longer time horizon, weighing not only immediate performance but also upgrade potential, support infrastructure, and total cost of care. As candidacy expands and device architectures evolve, procurement decisions should account for clinical program needs, follow-up capacity, and the ability to serve broader patient populations. In procurement-intensive settings, prioritize partners that can demonstrate reliable delivery, training, and service alongside competitive pricing.
Breast Implants Market
Closing Perspective
The cochlear implants market is moving from a period of broad-based growth to a more nuanced environment where technology architecture, indication strategy, reimbursement stability, and procurement dynamics jointly determine commercial outcomes. The market's expansion toward the 3 billion USD range by 2032 is supported by a credible 7.5 percent CAGR, but the distribution of value will depend on how effectively companies convert innovation into access, evidence, and operational readiness. For executives, investors, and procurement leaders, the most valuable next step is to ground strategic choices in detailed segment, regional, and product-level intelligence that connects these macro trends to specific portfolio and market decisions.
For detailed analysis of this topic, please visit the official page: Cochlear Implants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


