



Oligosaccharide Market 2026: 6.5% CAGR Trajectory and Strategic Shifts Across Key Segments

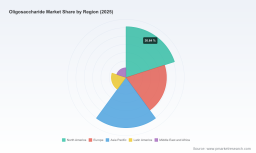
Oligosaccharide Market: Strategic Trends and Commercial Opportunities Through 2032
The global oligosaccharide market has entered a phase of structural expansion, transforming from a niche ingredient category into a mainstream strategic asset for food, nutrition, and pharmaceutical innovators. Valued at approximately USD 170.0 million in 2025, the market is projected to reach USD 261.0 million by 2032, advancing at a compound annual growth rate of 6.5 percent across the forecast horizon. This trajectory reflects more than incremental demand; it signals a fundamental recalibration of how manufacturers, regulators, and end consumers view complex carbohydrates as functional, health-modulating ingredients. For executives navigating long-cycle product portfolios, the window to shape positioning, secure supply resilience, and align with regulatory momentum is narrowing. Understanding where the market is headed, and why, separates reactive pricing plays from durable competitive advantage.
Market Snapshot and Structural Realities
The data points to a market that has consistently added value over the past five years, with revenue climbing from USD 122.0 million in 2020 to the current baseline of USD 170.0 million. Growth is not accelerating chaotically; it is compounding steadily, which suggests that buyer preferences, formulation science, and production economics are converging rather than shifting unpredictably. The market remains moderately fragmented in terms of concentration, with the top three players accounting for roughly 34.2 percent of revenue and the top five reaching 45.8 percent. This distribution matters because it indicates room for specialized entrants and regional champions to compete on formulation expertise, proprietary processing, or localized regulatory navigation, while the largest players leverage scale, integrated supply chains, and broad application portfolios.
The current environment is not characterized by unconstrained expansion. Instead, it is defined by several inflection points that will determine which organizations capture disproportionate value over the next three to five years. First, osmotic tolerance between health claims, formulation functionality, and cost efficiency remains a persistent tension for product developers. Oligosaccharides are no longer evaluated solely on prebiotic efficacy; they must also deliver taste, texture, stability, and dose usability across diverse matrices. Second, regulatory alignment is accelerating in key infant nutrition and functional food categories, effectively converting compliance requirements into competitive moats. Companies that anticipate claim substantiation and ingredient approval timelines will gain shelf and contract advantages, while laggards risk reformulation delays and market entry gaps. Third, feedstock and processing economics are becoming more sensitive to macro variables, making cost-to-serve and process flexibility strategic differentiators rather than back-office concerns. These dynamics do not weaken the market outlook; they clarify where value will be created and defended.
Core Drivers Reshaping the Competitive Equation
Market movement over the forecast period is being pulled by a small number of structural forces that interact across technology, regulation, demand behavior, and supply chain economics. Recognizing how these forces compound is essential for portfolio planning and investment coordination.
Technological innovation and process maturity are reshaping what is commercially viable. Advanced enzymatic synthesis, precision fermentation, and more selective purification methods are reducing the complexity gap between bulk carbohydrate production and high-purity functional ingredients. The practical effect is broader applicability across infant formula, dietary supplements, and pharmaceutical-adjacent formulations, where consistency, purity, and repeatability are non-negotiable. Public disclosures from late 2025 and early 2026 reinforce this direction: a major 2'-fucosyllactose supply initiative is moving into global distribution following collaboration between leading ingredient and chemical companies, while a dedicated short-chain fructo-oligosaccharide producer simultaneously expanded from three to four production lines and completed the full operation of a fourth facility equipped with automated quality control and advanced enzymatic synthesis. These moves indicate that leaders are not simply adding capacity; they are upgrading process capability to meet stricter specification requirements and higher batch-to-batch reliability expectations.
Xylooligosaccharides (XOS) Market
Regulatory and policy dynamics are converting scientific consensus into commercial clarity. In infant nutrition, regulatory frameworks are increasingly permitting oligosaccharide blends that better approximate the functional profile of human milk, creating formulation pathways that were more restrictive in prior cycles. European food safety authorities continue to maintain verification and health claim processes for key oligosaccharide categories in infant nutrition and functional foods, which raises the bar for documentation but also stabilizes demand for ingredients with established dossiers. Meanwhile, major Asian markets have updated infant-formula standards to align with international reference frameworks, coinciding with persistently large birth cohorts that sustain baseline demand for nutritionally complete early-life products. The strategic implication is that regulatory harmonization, when paired with clear claim routes, lowers perceived risk for manufacturers and accelerates adoption in categories that previously required lengthy internal validation.
Demand-side evolution is expanding the addressable use cases beyond traditional gut health narratives. Consumers and institutional buyers are increasingly treating oligosaccharides as multifunctional ingredients that support formulation goals across digestion, metabolic comfort, and product differentiation. This broadening mindset is especially visible in dietary supplements and food and beverage applications, where brands seek ingredients that can carry both functional positioning and label clarity. At the same time, procurement teams are placing greater weight on ingredient provenance, processing transparency, and supply consistency. The result is a buyer environment that rewards credible science, reproducible specification performance, and the ability to integrate into diverse production lines without compromising product stability.
Supply chain and cost structure shifts are introducing both pressure and opportunity. Feedstock pricing remains tied to broader commodity markets, with sucrose-linked inputs affecting enzymatic synthesis economics in regions where industrial energy costs are structurally elevated. This does not make cost management impossible, but it does make it a strategic variable. Organizations that design for feedstock flexibility, regional sourcing redundancy, and energy-efficient processing are better positioned to protect margins when input volatility spikes. Conversely, manufacturers that depend on narrow input channels or inflexible process designs face greater exposure to cost transmission that cannot be fully absorbed by downstream pricing.
Competitive Landscape and Strategic Positioning
The competitive field reflects a blend of global scale players, specialized ingredient manufacturers, and regional producers with distinct processing strengths. No single archetype dominates every application, and the market’s moderate concentration allows multiple winning strategies to coexist.
Fructooligosaccharide (FOS) Market
Large integrated companies are leveraged around application breadth, process know-how, and global distribution. In infant nutrition and specialized formulations, firms with fermentation and enzymatic capabilities are competing on purity, consistency, and the ability to supply human milk oligosaccharide-related ingredients such as 2'-fucosyllactose at commercial scale. Their advantage lies in the combination of scientific credibility, production repeatability, and the operational capacity to support stringent customer requirements across multiple geographies. These players also benefit from the ability to cross-link ingredient development with broader nutrition portfolios, which can shorten time-to-market for blended or multi-functional offerings.
Specialized manufacturers are competing on product range, application specificity, and responsiveness. Several firms focus on fructo-oligosaccharides, galacto-oligosaccharides, isomalto-oligosaccharides, and xylo-oligosaccharides for food, infant formula, and prebiotic uses, with differentiation rooted in chain-length control, format flexibility, and the ability to supply both powder and syrup forms. This group often wins by aligning closely with formulators’ practical needs, including solubility profiles, sweetness impact, stability under processing conditions, and dosage convenience. Regional players with strong local regulatory familiarity and efficient production layouts can also outperform on total delivered cost, particularly where logistics and import friction would otherwise erode competitiveness.
PW Consulting
Recent operational developments point to a landscape that is expanding in capability while tightening in quality expectations. Capacity additions are being paired with process modernization rather than treated as simple volume plays. The completion of dedicated production lines, implementation of automated quality control, and investment in enzymatic synthesis infrastructure suggest that the next phase of competition will center on reliability, specification control, and the ability to fulfill increasingly specific formulation briefs. At the same time, large dairy-linked and nutrition-oriented operators are expanding adjacent capacities that support broader functional ingredient portfolios. This signals an industry trend toward more integrated ingredient ecosystems, where oligosaccharides are not isolated commodities but components of broader formulation strategies spanning protein, lipid, and carbohydrate functionalities.
The market structure is likely to evolve through selective consolidation and continued differentiation rather than uniform concentration. Larger players may pursue strategic combinations that strengthen geographic coverage, application portfolios, or process technology. Smaller and mid-sized firms will likely continue to defend niches through formulation expertise, specialized molecule profiles, and fast response to customer formulation changes. New entrants will find opportunity primarily where they bring a distinct technical angle, such as novel purification routes, alternative feedstock pathways, or targeted health-claim positioning supported by robust documentation. The enduring competitive advantage will belong to organizations that can combine credible science, scalable and controllable production, and the commercial agility to serve multiple application categories without diluting quality.
Forward Outlook: Trends and Commercial Implications
The next three to five years will likely be shaped by three interlocking trends that translate directly into commercial opportunities and execution risks.
Precision and specification escalation will become the norm rather than the exception. As regulatory frameworks mature and application requirements become more demanding, buyers will increasingly differentiate between generic functional carbohydrate supply and ingredients that meet tightly controlled purity, chain-length, and batch-consistency parameters. The commercial opportunity here is clear: suppliers that can deliver repeatable specifications, transparent documentation, and application-specific formats will be able to command stronger commercial terms and longer-term supply relationships. The risk is equally clear. Organizations that compete primarily on price without corresponding quality and reliability infrastructure will face margin compression and reduced negotiating leverage as customers rationalize supplier bases.
Category convergence will expand the value pool across food, supplements, and infant nutrition. Regulatory alignment and formulation science are making it easier to position oligosaccharides across adjacent use cases without treating each category as entirely separate. This convergence creates opportunities for integrated product strategies, co-development with downstream brands, and portfolio architectures that capture demand across multiple consumption occasions. For manufacturers, the strategic task is to design ingredient platforms that can flex across applications while maintaining the documentation and consistency credentials required in higher-scrutiny categories. For investors, the opportunity lies in identifying operators whose process technology and application roadmap can serve more than one demand channel without sacrificing regulatory credibility.
Supply resilience and input-cost agility will move from operational concerns to strategic differentiators. As feedstock and energy cost sensitivity persists, the ability to source flexibly, manage regional cost structures, and engineer processing efficiency will shape both competitiveness and customer confidence. Companies that can demonstrate supply redundancy, predictable quality under variable input conditions, and transparent cost governance will be better positioned to secure long-term agreements. The uncertainty to monitor includes potential volatility in raw material markets, energy cost fluctuations in key production regions, and changes in trade or import dynamics that can alter delivered economics. Planning that assumes a single stable cost trajectory is likely to underprepare organizations for the range of plausible scenarios.
Actionable Priorities for Decision Makers
The commercial path forward depends on the role an organization plays in the value chain, but several priorities apply broadly.
- For ingredient and product manufacturers: invest in specification control and process modernization before expanding volume alone. The most durable position will come from repeatable purity, format flexibility, and documentation readiness that supports both food and supplement use cases. Align product development with regulatory and claim trajectories in target geographies rather than treating compliance as a late-stage checkpoint. Build feedstock and energy flexibility into sourcing strategies so that cost pressures do not force reactive discounting or inconsistent supply.
- For investors and corporate development teams: evaluate opportunities based on technological defensibility, application breadth, and the ability to meet rising quality expectations. Volume growth is attractive, but the more valuable question is whether a platform can sustain premium positioning as specifications tighten and buyer consolidation accelerates. Pay attention to companies that are upgrading enzymatic synthesis, automated quality control, and multi-format capability, because these capabilities tend to translate into longer-term commercial resilience rather than temporary capacity advantages.
- For procurement and R&D leaders: treat oligosaccharide sourcing as a multi-factor decision involving functionality, stability, documentation, and supply reliability, not just price per unit. Prioritize suppliers that can support application-specific requirements and provide clear evidence trails for regulatory and claim contexts. Diversify where feasible to reduce exposure to single-source risk, especially for formulations that depend on consistent performance across geographies or production lines.
The strategic stakes in this market are rising because the ingredient is becoming more central to product differentiation, regulatory positioning, and consumer-facing health narratives. That makes timely, granular intelligence valuable for anyone deciding where to allocate capital, how to structure supply relationships, or which formulation roadmaps to prioritize. Detailed segment-level demand splits, regional absorption patterns, company-specific capability mapping, and scenario-based volume and pricing assumptions can materially improve the quality of those decisions. For teams that need a sharper operational lens, the full PW Consulting research report provides the deeper segmentation, competitive benchmarking, and forward modeling required to convert these strategic signals into concrete plans.
For detailed analysis of this topic, please visit the official page: Oligosaccharide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


