



Automotive Cabin Air Filter Market: Why 5.8% CAGR and Shifting Segments Change Everything

The Automotive Cabin Air Filter Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
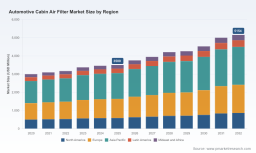
The automotive cabin air filter market has evolved from a commoditized replacement component to a strategic element of vehicle health, passenger safety, and OEM value engineering. Revenue across the global market reached approximately $3.5 billion in 2025, building on a steady expansion from roughly $3.0 billion in 2020. The trajectory reflects both volume growth in vehicle parc and a qualitative shift toward higher-performance filtration media, improved sealing, and integrated cabin health features. Forward estimates point to continued expansion through 2032, with a compound annual growth rate of 5.8 percent, indicating that incremental gains will increasingly come from premiumization and regulatory-driven specification changes rather than baseline replacement demand alone.
Europe and Asia Pacific together account for the largest share of revenue, reflecting dense vehicle populations, stringent emissions and air quality frameworks, and relatively fast fleet turnover in key markets. North America remains a meaningful contributor, supported by a high aftermarket penetration and a consumer base that has grown more attentive to in-cabin air quality. Latin America and the Middle East and Africa represent smaller but gradually expanding opportunities, often shaped by aftermarket service patterns and localized air quality concerns. The revenue distribution underscores a market where regional regulatory intensity, vehicle mix, and consumer awareness intersect to determine end-market appetite for advanced filtration.
Behind the top-line growth, the industry faces several structural challenges. First, the overlap between filtration performance, packaging constraints, and serviceability is becoming more complex. Modern vehicle architectures place cabin air filter housings in tighter spaces, sometimes near sensitive components such as wiring harnesses. This creates a design and service risk: a filter change that is intended to be routine can, if executed improperly, damage adjacent systems. Recent safety actions in the United States highlight this tension. A Part 573 safety recall report and a related service information bulletin addressed potential damage to air conditioning wiring harnesses during cabin air filter replacement on certain vehicles. An engineering investigation was initiated after field incidents involving thermal events in model year 2024 vehicles where the filter housing cover sits close to the air conditioning wiring harness. The follow-up bulletin mandated procedure modifications to avoid harness damage during replacement. For OEMs and service networks, these developments add a layer of process control, training, and design-risk management that did not exist when cabin filters were treated as simple consumables.
Second, the regulatory environment is tightening filtration expectations while simultaneously reshaping adjacent vehicle systems. More stringent ambient air quality standards for particulate matter are raising the bar for what consumers and regulators expect from in-cabin filtration. At the same time, the phase-down of high-global-warming-potential hydrofluorocarbons in model year 2025 has accelerated the adoption of advanced cabin air filtration systems as part of broader climate and refrigerant transitions. In Europe, Euro 7-style expectations are pushing particle filtration performance down to very small sizes, influencing both OEM specifications and aftermarket acceptable performance. The cumulative effect is a market where compliance is no longer a checkbox but a continuous performance requirement that can affect material selection, media layering, and validation cycles.
Third, the combination of rising performance expectations and cost sensitivity is reshaping competitive dynamics. Activated carbon and combination products command stronger positioning in segments where odor, gaseous pollutants, and allergen reduction matter, but they also increase material and manufacturing complexity. Electrostatic and media-engineered solutions offer efficiency gains, yet they must be balanced against airflow, load, noise, and service life. Suppliers and buyers alike are navigating a tension between specification ambition and total cost of ownership, especially in commercial fleets and price-sensitive aftermarket channels. The result is a market in transition: growth is real, but it is unevenly distributed across regions, vehicle types, and product tiers, and the competitive winners will be those who can manage performance, service risk, and cost at the same time.
Key Demand Drivers
The market is being pulled forward by a small number of high-impact forces that are reshaping both product design and commercial positioning.
Technology Innovation and Media Engineering
Media architecture remains the central differentiator. The industry is moving beyond basic particulate capture toward layered solutions that combine mechanical filtration, adsorption, and electrostatic effects. Activated carbon media continues to play a central role for odor and gaseous contaminant control, while nanofiber and electrostatically enhanced materials are increasingly used to raise capture efficiency without excessively restricting airflow. Multi-layer designs are also enabling more compact housings and better balance between filtration efficiency and system load. Recent product guidance from leading suppliers shows how these technologies are being adapted to specific vehicle categories, including motorhomes, where activated carbon protection against odors and harmful gases is being emphasized for prolonged cabin occupancy and varied operating environments.
This technology shift matters because it changes the basis of competition. A filter that was once evaluated primarily on particulate arrestance is now judged on odor management, allergen reduction, durability, and ease of integration. That, in turn, creates room for differentiation in both OEM sourcing and aftermarket branding, especially where consumers associate filtration quality with overall cabin health and comfort.
Automotive Cabin Air Quality Sensor Market
Policy and Regulatory Environment
Regulatory pressure is a growing source of demand for higher-efficiency cabin filtration. Stricter ambient particulate matter standards are reinforcing the value proposition of filters that can remove a very high proportion of fine particles. At the same time, tighter vehicle-level emissions frameworks and refrigerant transitions are indirectly raising the importance of cabin air quality, because they encourage broader system changes and a more holistic view of in-cabin environmental control. Europe’s push toward filtration of extremely small particles and the United States’ refrigerant-related transitions both illustrate how policy is influencing product expectations beyond traditional replacement cycles.
For manufacturers and fleet operators, the regulatory trajectory creates two practical effects. One is a rising floor for acceptable performance, which compresses the lowest end of the market and rewards suppliers with validated media and testing capabilities. The other is an opportunity to position advanced filtration as part of a broader safety, health, and compliance narrative, rather than as a standalone part number.
Demand-Side Shifts in Consumer and Fleet Behavior
Passenger car buyers are increasingly aware of air quality as a component of vehicle livability, particularly in urban environments and regions with seasonal pollutant spikes. That awareness has elevated the appeal of combination and activated carbon solutions in premium and mid-tier segments, and it has also influenced service behavior, where filter replacement is being viewed more proactively rather than purely reactively. In commercial vehicles, fleet operators are weighing cabin filtration alongside driver comfort, retention, and operational reliability, especially where vehicles operate in dusty or high-pollution conditions. In two-wheelers, demand is smaller but still growing in markets where exposure to traffic emissions and particulate matter is uneven and where affordable upgrade paths can improve rider experience.
These behavioral changes are important because they expand the conversation beyond technical specs. The commercial case for better filtration is increasingly tied to perceived health benefits, comfort, and brand positioning, which gives suppliers and automakers a stronger storytelling and value-selling platform.
Supply Chain and Cost Structure Evolution
The cost picture is being shaped by the interplay of media complexity, validation requirements, and the need to maintain serviceability. Higher-performance materials and layered constructions can improve capability, but they also create pressure on sourcing, manufacturing consistency, and quality control. At the same time, the service-side incidents discussed earlier are forcing reconfiguration of replacement procedures and, in some cases, packaging or access design. That adds indirect cost in training, documentation, and warranty-related risk management. Suppliers that can standardize high-quality media, control variability, and design for service-friendly installation are better placed to protect margins while meeting performance expectations.
Competitive Landscape and Leading Strategies
The competitive structure is moderately concentrated, with the top three players holding a notable share and the top five extending that advantage further. Concentration at this level indicates that scale, OEM relationships, media expertise, and brand recognition matter, but it also leaves room for specialized players to compete in niches such as performance filtration, aftermarket branding, or specific application segments.
European suppliers remain particularly prominent, reflecting deep OEM integration, strong engineering heritage, and broad coverage across passenger cars, trucks, and off-highway applications. One global filtration specialist has emphasized nanofiber and activated carbon technologies across OEM and aftermarket lines, with recent recommendations tailored to motorhomes that highlight activated carbon protection against odors and harmful gases. Another major German supplier has focused on both original equipment and retrofit applications, spanning particulate and combination filters. A third large industrial and automotive supplier has built a position around high-efficiency particle and activated carbon options for OEM integration, while a fourth German filtration technology company is known for advanced media aimed at protection against pollutants and allergens. Together, these players illustrate how leading vendors combine media science, broad application coverage, and channel strength to defend share.
In Asia, Japanese manufacturers have carved out strong positions through integration with vehicle programs and specialized media approaches. One major Japanese supplier has highlighted multi-layer media designed for optimal airflow and filtration efficiency, including particulate-electrostatic concepts, while another has developed OEM cabin filters integrated into Toyota and Lexus vehicle models. These examples show how regional strengths in manufacturing discipline and OEM relationships can support consistent volume and specification alignment.
North American participants bring a different set of advantages. Some focus on high-efficiency products for automotive and commercial vehicle applications across OEM and replacement markets, while others emphasize specialized filtration media or performance-oriented and washable solutions. A separate aftermarket-oriented group has expanded consumer visibility through branded variants, illustrating how retail presence and brand recognition can complement product capabilities in the replacement channel.
The strategic patterns among leaders are clear. First, differentiation is increasingly tied to media architecture and validated performance rather than commoditized fitment alone. Second, the most resilient players are those that can serve both OEM and aftermarket channels, because OEM programs provide scale and specification influence while aftermarket channels provide reach and margin flexibility. Third, application breadth matters: suppliers that address passenger cars, commercial vehicles, and select two-wheeler or niche segments can smooth cyclicality and capture cross-segment learning. At the same time, the landscape is evolving. Consolidation pressure persists among smaller players that cannot match validation costs or OEM integration requirements, while new entrants and specialist media companies can still gain ground where they offer distinct efficiency, serviceability, or branding advantages. The recent regulatory and serviceability issues also suggest that design integration, documentation, and field support will become more important competitive factors, not just filter performance on a spec sheet.
Future Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape where value is created in this market.
PW Consulting Automotive & Machinery Research Center
Performance Premiumization with Serviceability as a Design Constraint
Demand for higher-efficiency and odor-controlling products should continue to rise, especially where air quality concerns and consumer expectations overlap. However, the most successful offerings will be those that balance performance with accessible replacement design and clear service instructions. The recent safety and service bulletin activity is a reminder that a filter’s value proposition is not limited to filtration efficiency; it also includes the risk profile of the replacement process. Suppliers and vehicle programs that design for both performance and safe service access will be better positioned to reduce field issues and protect customer trust.
Worldwide Automotive Air Filter Housing Market
The commercial opportunity here is twofold: advanced media can support higher-margin product tiers, and service-friendly design can reduce warranty exposure and strengthen OEM and fleet relationships. The risk is that performance gains are undermined by packaging compromises or by replacement procedures that are too easy to mishandle.
Regulatory-Driven Specification Escalation
As ambient air quality standards tighten and vehicle-level expectations evolve, filtration requirements will continue to move up the performance curve. This will likely compress the lowest tier of the market and increase reliance on validated media, repeatable manufacturing, and testing capability. It also creates an opening for suppliers that can translate regulatory requirements into practical, cost-effective product architectures for both OEM and aftermarket use.
The risk is that compliance pressure becomes fragmented across regions and programs, making it harder to scale a single solution globally. Companies that can maintain a core platform while adapting media and sealing options to local requirements will have an advantage in managing complexity without sacrificing margin.
Channel Blending and Aftermarket Brand Building
The aftermarket will remain a major growth driver, but its composition is changing. Consumer awareness is supporting demand for higher-quality replacement filters, while commercial buyers are looking for consistent performance and reduced operational disruption. At the same time, branded aftermarket offerings and performance-oriented products are expanding visibility and choice. This blending of channels means that competitive success will depend not only on supply reliability but also on consumer communication, fitment clarity, and distribution reach.
A key commercial opportunity is to build recognizable value propositions in the replacement channel around health, comfort, and reliability, rather than competing solely on price. A key risk is channel conflict and margin erosion if premium claims are not backed by visibly differentiated performance or service experience.
Strategic Recommendations for Decision-Makers
For manufacturers and product developers, the priority is to treat cabin air filtration as a system-level attribute rather than a low-cost replaceable part. That means investing in media architecture that can address particulate, odor, and allergen concerns while maintaining airflow and durability, and validating designs against real-world service scenarios. It also means coordinating packaging, access, and documentation so that replacement does not create avoidable risk. Companies that can demonstrate consistent performance across OEM and aftermarket use, with clear instructions and robust quality control, will be better positioned as performance expectations rise.
For investors, the most interesting signals are the shift toward premiumized media, the growing importance of regulatory-driven specification changes, and the channel dynamics that favor suppliers with both OEM credibility and aftermarket visibility. Evaluation should focus on whether a company has defensible media technology, the ability to serve multiple applications, and the operational discipline to manage serviceability and compliance risk. In a market growing at a mid-single-digit rate, differentiation and execution quality matter more than volume alone.
For procurement and fleet buyers, the strategic question is not whether to buy a better filter, but how to make filtration choices that align with operating conditions, service processes, and total cost goals. That calls for selecting products with validated performance for the relevant environment, ensuring that replacement procedures are clear and compatible with the vehicle, and avoiding low-cost options that may compromise airflow, seal integrity, or service safety. In commercial operations, standardization can reduce complexity, but it should be paired with enough performance headroom to handle variable pollution and dust exposure.
The market’s direction is becoming clearer: growth will continue, but the most valuable opportunities will belong to those who can integrate filtration performance, regulatory readiness, service safety, and channel execution into a coherent offering. For decision-makers who need detailed segmentation data, company-level positioning, and tailored guidance for specific regions or applications, the full research report provides a deeper evidence base and more granular recommendations to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Automotive Cabin Air Filter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


