



PGMEA for Electronic Materials Market: Beyond the 6.2% CAGR Story

Strategic Trends and Commercial Opportunities in the PGMEA Market for Electronic Materials
Propylene glycol methyl ether acetate (PGMEA) has evolved from a niche specialty solvent into a critical enabler of advanced electronics manufacturing. Its unique balance of solubility, evaporation rate, and purity makes it indispensable in photoresist formulation, semiconductor wafer processing, and display panel fabrication. As the electronics industry pushes toward finer geometries, higher packaging densities, and larger-area displays, the demand profile for PGMEA is shifting in both volume and specification. Understanding this solvent through the lens of market structure, technological inflection points, and supply chain dynamics is essential for executives navigating procurement, capacity planning, and capital allocation decisions.
Market Landscape: Scale, Trajectory, and Structural Tensions
The PGMEA market for electronic materials has demonstrated steady expansion over the last half-decade, with revenue climbing from approximately $101.0 million in 2020 to an estimated $136.78 million in 2025. The trajectory reflects a compound annual growth rate of 6.2 percent across the forecast window extending to 2032, when the market is projected to reach $207.08 million. This growth is not merely cyclical; it is structurally anchored in the intensification of semiconductor fabrication capacity, the maturation of advanced packaging workflows, and the ongoing migration toward higher-resolution display architectures.
Electronic Packaging Materials Market
Despite the headline growth figures, the market operates under a concentrated supply structure. The top three producers capture roughly 52 percent of total revenue, while the top five account for 68 percent. This concentration creates a dual reality: it provides stability through established technical expertise and long-term supply agreements, but it also heightens vulnerability to capacity disruptions, grade-specific shortages, and pricing asymmetries across regions. Buyers cannot assume seamless substitution when a single electronic-grade specification dominates their process window.
Key Challenges and Inflection Points
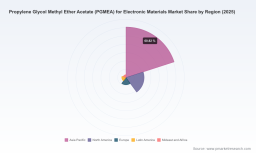
Several structural tensions are reshaping how stakeholders approach PGMEA procurement and investment. First, the divergence between electronic-grade and industrial-grade specifications is widening. Electronic-grade requirements demand ultra-high purity, trace-metal control, and consistent batch-to-batch performance, which translates into premium pricing tiers and more stringent quality assurance protocols. Second, geographic supply dynamics are introducing persistent regional cost differentials. Asia-Pacific producers supply the majority of global volume, but freight costs, insurance, import tariffs, and local emissions compliance add layered complexity for North American and European buyers. Third, the market is entering a phase where regulatory friction around chemical manufacturing, emissions, and substance notification is no longer a peripheral compliance concern; it is becoming a determinant of capacity siting, grade qualification timelines, and time-to-market for new formulations.
These inflection points matter because PGMEA is not a commodity that can be easily re-sourced without process re-qualification. In semiconductor wafer manufacturing, where the largest share of demand concentrates, even minor solvent variability can affect photoresist coating uniformity, line edge roughness, and defectivity. That reality gives incumbents with proven electronic-grade track records a durable advantage, while simultaneously raising the bar for new entrants and for buyers seeking to diversify supply.
Core Drivers Shaping Market Direction
Technological Innovation and Process Evolution
The most direct driver of PGMEA demand is the semiconductor industry's pursuit of advanced patterning and higher-throughput wafer processing. As device architectures become more complex, the solvent environment surrounding photoresist application, rinse, and strip operations must maintain ultra-low particulate and metallic contamination levels. PGMEA's ability to dissolve and carry resist components with controlled drying characteristics positions it as a preferred medium in many advanced patterning workflows. The same logic extends to IC packaging, where increasing use of redistribution layers, micro-bumps, and fine-pitch interconnects creates additional solvent demand for etching, cleaning, and coating stages. In display panel manufacturing, larger substrate sizes and tighter optical requirements also support solvent consumption, though the growth trajectory there is more cyclical and tied to panel investment cycles.
A practical indicator of this technological pull is the premium attached to electronic-grade PGMEA. Industry market data from mid-2026 places electronic-grade PGMEA in the $3.2 to $4.8 per kilogram range, reflecting the cost of achieving and maintaining ultra-high purity for semiconductor applications. That price band signals that end users are willing to pay for performance certainty, not merely solvent volume. For manufacturers, this reinforces a strategy centered on grade consistency, contamination control, and certification rigor rather than volume-only competition.
Policy and Regulatory Environment
Regulatory developments are reshaping both the cost structure and the qualification pathway for PGMEA. In the United States, PGMEA falls under the Toxic Substances Control Act, which requires pre-manufacture notification for novel grades. This means that any differentiation in formulation, impurity profile, or production route can trigger additional regulatory steps before commercial deployment. For incumbents, this is a competitive moat; for new entrants or formulators seeking alternate grades, it adds time and friction to market entry.
Beyond substance notification, tightening emissions requirements across North American and European jurisdictions are increasingly influencing chemical manufacturing processes and downstream applications such as coatings and inks. These standards affect not only the solvent itself but also the processing environment in which it is used. Facilities that can demonstrate lower emissions intensity, closed-loop handling, or improved recovery may gain an advantage in customer qualification and sourcing decisions. Regulatory alignment is therefore becoming a strategic consideration, not just a compliance checklist.
Demand-Side Shifts in Electronics End Markets
Demand for PGMEA is being shaped by the broader electronics investment cycle. Semiconductor wafer manufacturing continues to drive the largest application share, supported by capacity additions in logic, memory, and specialty devices. IC packaging demand is growing as advanced packaging becomes a primary lever for performance and cost optimization, creating incremental solvent requirements in underfill, etching, and surface preparation processes. Display panel manufacturing remains relevant, particularly where high-resolution and larger-format production sustain solvent intensity. The demand picture is less about a single product surge and more about compounding pressure across multiple process steps as device complexity increases.
From a buyer perspective, this trend translates into more frequent grade reviews, longer qualification cycles, and greater emphasis on dual-sourcing where feasible. However, qualification timelines are themselves a source of friction because process sensitivity makes rapid substitution difficult. The result is a demand environment that supports volume growth but also rewards suppliers that can reduce qualification risk through documentation, consistency, and technical collaboration.
Supply Chain and Cost Structure Dynamics
The upstream cost structure of PGMEA is tied closely to propylene oxide and acetic acid, which serve as primary feedstocks for PGMEA synthesis. Pricing for these inputs has been volatile, and that volatility transmits directly to downstream production costs. For producers, this creates margin pressure when feedstock spikes are not fully passed through, and for buyers, it reinforces the need to understand cost pass-through mechanisms, contract structures, and inventory strategies. The connection between feedstock volatility and finished-solvent pricing is a reminder that PGMEA should be evaluated as part of a broader chemicals value chain rather than as an isolated material.
Regional logistics further shape the cost picture. Asian producers supply most PGMEA globally, but freight, insurance, and import tariffs generate regional price differentials for North American and European buyers. These differentials are not static; they fluctuate with trade policy, shipping conditions, and localized capacity additions. The practical implication is that landed cost optimization now requires examining grade suitability, lead times, and supply reliability alongside unit price. A lower ex-works price does not necessarily translate into lower total cost of ownership when qualification risk, delivery variability, and logistics exposure are factored in.
Competitive Landscape and Strategic Positioning
Incumbent Profiles and Differentiation
The competitive field includes large diversified chemical producers and specialized regional players that have built credibility through electronic-grade performance. Dow Inc. supplies DOWANOL PMA for electronic materials, including photoresist, PCB processing aids, and color resist applications. Its differentiation rests on a broad solvent platform, established formulation relationships, and the ability to support multiple electronics end uses from a single product architecture. Eastman Chemical Company offers EastaPure high-purity PGMEA specifically developed for semiconductor, photoresist, LCD display, and electronic chemicals applications. The brand emphasis on high purity aligns directly with the premium pricing and qualification demands of semiconductor customers. LyondellBasell Industries N.V. manufactures PGMEA through integrated propylene-based operations, which can provide feedstock integration advantages and support coatings, inks, and electronics solvent applications. Shell plc supplies Methyl PROXITOL acetate for semiconductor and electronics processing aids, leveraging integrated chemical supply capabilities and global logistics reach.
BASF SE produces and supplies PGMEA and glycol ether acetates for electronics and semiconductor solvent systems, benefiting from scale, technical service infrastructure, and the ability to offer families of related solvents. In Japan, KH Neochem Co., Ltd. offers PGMEA across coatings, inks, electronics materials, adhesives, and polymeric applications, while Shinko Organic Chemical Industry Ltd. specializes in high-purity acetic esters and solvents, including PGMEA for electronic materials. The Japanese specialists illustrate how focused purity expertise and application-specific service can sustain a strong position in a concentrated market, particularly where semiconductor customers value batch consistency and technical responsiveness.
Strategic Positioning and Market Evolution
Leading players are differentiating along three axes: purity assurance, application engineering, and regional supply reliability. Purity assurance is the foundation because electronic-grade PGMEA commands premium pricing and because semiconductor processes are highly sensitive to contamination. Application engineering is the differentiator that converts a solvent purchase into a process partnership, helping customers optimize coating, drying, and cleaning parameters. Regional supply reliability is increasingly decisive as buyers confront logistics volatility and want to reduce exposure to single-region dependence.
The market is likely to evolve through a combination of consolidation pressure and selective specialization. Large players with integrated feedstock access, regulatory expertise, and global distribution can capture scale advantages and cross-sell across electronics and industrial segments. At the same time, specialists that can guarantee electronic-grade consistency, support fast qualification, and offer localized technical service remain attractive to semiconductor and display customers. Capacity investments are already reflecting this dynamic. In August 2025, for example, Eastman Chemical Company expanded manufacturing capacity in Asia-Pacific by more than $150 million to meet surging demand for high-purity PGMEA in the electronics sector. Moves of this kind signal that producers are aligning capacity with electronic-grade demand growth rather than treating PGMEA as a generic solvent line.
For new entrants, the barrier is not only capital but qualification. Electronic customers will not switch grades simply because a lower price is available; they require documented purity, reproducibility, and process compatibility. That reality favors incumbents with established credentials and creates an environment where new capacity must be paired with a clear grade strategy, robust analytical support, and credible customer engagement.
Forward Outlook: Three Trends Shaping the Next 3 to 5 Years
Trend One: Electronic-Grade Premium Will Become More Structurally Entrenched
As patterning requirements tighten and defectivity targets become more demanding, the gap between electronic-grade and industrial-grade PGMEA will likely widen in both specification rigor and price. Process owners will continue to prioritize consistency and contamination control over marginal cost savings, particularly in leading-edge wafer manufacturing and advanced packaging. The commercial opportunity here lies in services that reinforce grade confidence: certified lot documentation, impurity traceability, stability testing, and responsive technical support. Sellers that can reduce qualification risk will be able to defend premium positioning even as feedstock volatility creates cost pressure.
The risk side of this trend is that any relaxation in semiconductor investment cycles could slow the rate of volume growth, even if unit pricing remains elevated. Buyers should therefore assess PGMEA not only against near-term project pipelines but also against longer-duration fab and packaging capacity plans, where qualification lead times make early supplier engagement valuable.
Trend Two: Regional Supply Reconfiguration and Qualification-Driven Sourcing
Over the next several years, procurement teams will increasingly treat PGMEA sourcing as a regional risk-management decision. Asian supply dominance will persist, but freight variability, import tariffs, and localized emissions requirements will keep regional price differentials in play. Some buyers will pursue qualification of additional sources to reduce single-region exposure, while others will optimize around a primary supplier with strong technical credentials and reliable logistics. The key variable is not the number of qualified suppliers but the speed and confidence with which a buyer can onboard an alternate grade without disrupting process yield.
This trend creates an opportunity for producers and distributors that can offer clear grade equivalence documentation, predictable lead times, and regionally appropriate inventory strategies. It also raises the importance of understanding landed cost holistically, including the cost of qualification delays, batch failures, and schedule variability. The commercial implication is straightforward: reliability and service quality are becoming priced attributes, not optional extras.
Trend Three: Regulation and Sustainability as Competitive Filters
Regulatory coverage under frameworks such as the Toxic Substances Control Act, plus tightening emissions expectations for chemical manufacturing and downstream applications, will increasingly shape where capacity is built, how grades are introduced, and which suppliers are favored in qualification. Producers that invest early in emissions control, solvent recovery, and transparent regulatory documentation will likely experience smoother customer qualification and fewer interruptions when new grades are introduced. For buyers, this trend means that supplier selection will incorporate not only purity and price but also regulatory readiness and sustainability alignment, especially in North American and European operations.
PW Consulting
The uncertainty here lies in the pace and specificity of regulatory changes across jurisdictions. Shifts in substance notification expectations, emissions limits, or reporting obligations can alter the relative attractiveness of different production routes and regions. Stakeholders should monitor regulatory developments as part of supply strategy, not as a separate compliance function, because these changes can influence both cost and availability with limited warning.
Decision-Maker Playbook: Actions by Stakeholder Type
For Manufacturers and Producers
Build differentiation around grade reliability and application support rather than competing on volume alone. Electronic-grade customers reward purity consistency, documented impurity control, and fast technical response, so investment in analytical capability, process control, and customer-facing engineering will likely yield stronger retention than price-led strategies. Feedstock integration can provide cost resilience, but it must be paired with a credible electronic-grade offering to capture premium segments. Regional capacity decisions should account for both demand growth and logistics exposure, especially where tariff and freight volatility affect competitiveness in North America and Europe.
Manufacturers should also treat regulatory readiness as a strategic asset. Early engagement on substance notification, emissions control, and grade documentation can shorten qualification timelines and reduce the risk of delays when introducing new grades. Capacity additions, such as the $150 million Asia-Pacific expansion announced by Eastman Chemical Company in August 2025, illustrate how targeted investment aligned with high-purity electronics demand can reinforce market position. Producers that can demonstrate similar alignment between capacity, grade strategy, and regional demand will be better placed to capture durable share.
For Investors and Strategic Capital Allocators
Evaluate PGMEA exposure as a proxy for electronics process intensity rather than as a standalone chemical product. Demand strength correlates with semiconductor wafer manufacturing activity, advanced packaging adoption, and display investment cycles, so investment theses should be tied to capacity pipelines and grade requirements in those end markets. The concentrated supplier base suggests that incumbents with electronic-grade credibility, feedstock access, and regional supply reliability will likely capture a disproportionate share of premium volume, but it also means that capacity expansion decisions should be scrutinized for grade specificity and qualification readiness.
Investors should also pay attention to regional supply reconfiguration. Capacity additions in Asia-Pacific are enhancing high-purity availability, but North American and European buyers continue to face freight, tariff, and emissions-related cost differentials. Companies that can address those differentials through localized service, inventory positioning, or differentiated grade offerings may gain negotiating strength and customer stickiness. The most attractive opportunities are those where a supplier can combine purity assurance, technical support, and reliable regional supply in a way that reduces qualification risk for high-value electronics customers.
For Procurement and Supply Chain Leaders
Treat PGMEA sourcing as a total-cost and qualification-risk decision. The wide premium band for electronic-grade material reflects real process sensitivity, so sourcing strategies should weigh purity consistency, documentation quality, and supplier technical capability alongside unit price. Where feasible, develop qualification pathways for alternate sources before they are urgently needed, because process re-qualification can be time-consuming and risky. Regional price differentials should be evaluated in terms of landed cost, lead-time reliability, and exposure to logistics or trade disruptions rather than purely on ex-works price.
Propylene Glycol Solvent Market
Procurement teams should also align contracting strategies with feedstock volatility and grade specificity. Fixed-price contracts may reduce short-term exposure, but they can obscure the link between propylene oxide and acetic acid dynamics and finished-solvent costs. Mechanisms that share visibility on feedstock movements, while protecting grade certification and delivery reliability, are often more effective than simple price Minimization. Finally, keep regulatory developments in view, especially where new grades or new supply regions may trigger additional notification or emissions-related requirements that affect qualification timelines and total cost.
Closing Perspective
The PGMEA market for electronic materials is entering a phase where growth is increasingly tied to grade specificity, regional supply reliability, and regulatory readiness. The combination of structural demand from semiconductor wafer manufacturing, advanced packaging, and display fabrication supports a positive medium-term trajectory, while feedstock volatility, regulatory friction, and concentrated supply introduce meaningful risk for both producers and buyers. In this environment, the most valuable commercial advantage is not simply access to solvent volume; it is the ability to deliver consistent electronic-grade performance with predictable qualification timelines and resilient regional supply. Stakeholders who evaluate PGMEA through that lens will be better positioned to capture opportunity and manage exposure as the market evolves through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


