



Zinc Sulfide Market: Why 99.99% Purity and Asia Pacific Reshape Competition

Strategic Trends and Commercial Opportunities in the Zinc Sulfide Market
The global Zinc Sulfide market represents a specialized yet strategically vital segment within the broader advanced materials landscape. With a market valuation reaching approximately $128.0 million in 2025, the sector has demonstrated steady expansion over the preceding five years, reflecting a compound annual growth rate of 2.9 percent projected through 2032. This trajectory, while modest in percentage terms, masks significant underlying shifts in application demand, technological capability, and regional supply dynamics. For executives and investors navigating specialty chemicals and advanced materials, understanding the structural forces shaping this market is essential for informed capital allocation and strategic positioning.
PW Consulting
The market's growth path reveals interesting inflection points. Following recovery from earlier disruptions, the sector has settled into a pattern of incremental but consistent expansion. The transition from mid-2020s consolidation toward broader application diversification suggests a maturing market that is simultaneously deepening its technological sophistication while broadening its commercial footprint. Industry participants who recognize these dual dynamics are better positioned to capture value across the value chain.
Market concentration data indicates a relatively fragmented competitive environment, with the top three players commanding approximately 28.5 percent of total share and the top five holding around 32.0 percent. This concentration level suggests opportunities for both consolidation among established players and continued emergence of specialized competitors targeting niche applications or regional markets.
Key Challenges and Inflection Points
Several structural challenges are reshaping how market participants approach strategy and investment decisions. The first centers on raw material sourcing and cost volatility. The primary upstream feedstock derives from zinc ore concentrate from sphalerite deposits, with LME zinc prices averaging $1.33 per pound in recent years. This raw material dependency creates exposure to commodity price fluctuations that can pressure margins, particularly for producers operating with narrow differentiation in standard-grade products. Concurrent pressure from sulfur and energy costs affecting downstream compounds like zinc sulfate compounds the input cost challenge, particularly in European markets where energy dynamics remain uncertain.
A second critical inflection point involves regulatory frameworks and trade policy uncertainty. The United States reached a point in 2024 where imports of refined zinc constituted 73 percent of domestic consumption, and ongoing tariff considerations on Canadian and Mexican supplies continue to reshape supply chain planning. Simultaneously, China's December 2024 decision to ban exports of gallium, germanium, antimony, and superhard materials to the United States has created ripple effects across downstream semiconductor and advanced manufacturing inputs. More recently, China's temporary suspension of export controls on key raw materials including rare earths and lithium batteries from November 2025 through November 2026 introduces a dynamic regulatory environment that demands agile supply chain responses.
Third, the market faces the challenge of balancing purity differentiation with cost efficiency. The dominance of high-purity grades in market composition reflects strong demand from optical and electronic applications, yet the premium associated with ultra-high-purity production creates barriers for new entrants while pressuring existing producers to continuously invest in process optimization. Companies that fail to achieve meaningful differentiation on purity, application performance, or regional service capabilities risk commoditization pressure in segments where technical barriers are lower.
Key Drivers Shaping Market Evolution
Technological Innovation and Application Expansion
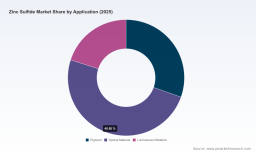
Technological advancement remains the primary engine of value creation in the Zinc Sulfide market. Optical material applications represent the largest demand segment, driven by the compound's unique luminescent and optical properties that enable performance in specialized lighting, display technologies, and advanced optical systems. The sustained demand from this segment reflects ongoing innovation in consumer electronics, industrial lighting solutions, and emerging display architectures that require materials with precise optical characteristics and high purity consistency.
Luminescent material applications constitute another significant demand pillar, supporting industries ranging from specialty coatings to security and authentication features. The growing integration of functional materials into advanced manufacturing processes creates incremental demand that rewards suppliers capable of delivering consistent quality and technical support. Pigment applications, while representing a more mature demand category, continue to benefit from formulation improvements and performance requirements in coatings, plastics, and specialized industrial applications where zinc sulfide offers distinct advantages in opacity, weather resistance, or chemical compatibility.
Innovation trajectories are not limited to end-use applications. Advances in production processes that enable tighter control over particle size distribution, surface treatment, and purity levels are expanding the addressable market for high-value applications. Suppliers investing in process capabilities that reduce variability, improve batch consistency, or enable new material configurations position themselves to capture premium value from demanding downstream customers.
Regulatory and Trade Policy Dynamics
Regulatory developments are exerting both constraining and enabling effects on market dynamics. The concentration of high-purity zinc sulfide production and related advanced material capabilities in specific geographic regions creates supply chain interdependencies that are increasingly subject to policy scrutiny. Export control measures affecting related materials such as gallium and germanium signal broader strategic considerations around materials critical to advanced manufacturing and technology sectors.
For market participants, regulatory uncertainty translates into the need for diversified sourcing strategies and enhanced supply chain visibility. Companies that proactively map their exposure to policy-dependent supply routes and develop alternative sourcing or regional production capabilities are better insulated against disruption. Conversely, regulatory developments that promote domestic production or strategic material self-sufficiency in key markets may create opportunities for localized production investments or partnerships.
The temporary relaxation of export controls observed in late 2025 illustrates the fluid nature of policy environments in key sourcing regions. While such developments may provide near-term supply relief, they underscore the importance of scenario planning and flexible procurement strategies that can adapt to shifting regulatory landscapes.
Shifting Demand Patterns and Customer Expectations
Demand-side evolution reflects broader industrial trends toward higher performance specifications, greater material consistency, and enhanced technical support. End-users in optical and electronic applications increasingly require suppliers who can provide not only consistent material quality but also application-specific technical assistance, customization capabilities, and reliable delivery performance. This shift from transactional purchasing to value-added supplier relationships rewards companies with strong technical capabilities and responsive service infrastructure.
Sodium Sulfide Market
In pigment and industrial application segments, demand patterns are influenced by broader economic activity, construction cycles, and manufacturing output. Customers in these segments typically prioritize price competitiveness and supply reliability, though performance requirements continue to rise as formulations become more sophisticated and application conditions more demanding. Suppliers serving these segments benefit from scale efficiencies, cost management discipline, and strong distribution networks that ensure consistent availability.
The interplay between these demand segments creates opportunities for companies that can effectively balance portfolio breadth with segment-specific technical depth. Attempting to serve all segments without clear differentiation or capability focus may dilute competitive advantage, while over-concentration in a single segment may increase exposure to cyclical or structural demand shifts.
Supply Chain Restructuring and Cost Considerations
Supply chain dynamics are undergoing meaningful adjustment as producers and customers recalibrate strategies in response to cost pressures and policy uncertainty. The vast majority of primary zinc consumption in key markets comes through imports, creating natural exposure to logistics costs, trade policy shifts, and currency effects. Producers with integrated upstream positions or diversified sourcing arrangements hold structural cost and supply assurance advantages.
Regional production footprints are gaining strategic importance as supply chain resilience becomes a priority for downstream customers. While certain regions retain advantages in production scale and technical capability, the trend toward regionalization encourages investment in production capacity closer to end markets or development of strong logistics partnerships to ensure supply reliability.
Cost structure management remains essential given raw material price exposure and energy cost pressures. Producers that achieve superior cost positions through scale, process efficiency, or feedstock advantages can maintain margins even in segments where pricing power is limited. Conversely, companies with higher cost structures face increasing pressure to justify premium pricing through demonstrable quality, service, or technical value.
Competitive Landscape and Strategic Positioning
Differentiation Strategies Among Key Players
The competitive environment features a diverse set of participants with varying strategic orientations and capability focuses. Large diversified chemical companies with zinc sulfide offerings typically leverage broader portfolios, established technical infrastructure, and global customer networks to serve high-value optical and industrial applications. These players compete on the basis of application expertise, quality consistency, and integration with broader customer material requirements rather than on commodity pricing.
Specialized producers focused on pigment grades or standard industrial applications compete primarily on cost efficiency, regional availability, and production reliability. Their strategic advantage typically derives from focused manufacturing operations, efficient feedstock access, and strong relationships with regional distribution channels. Success in this segment requires disciplined cost management and the ability to maintain consistent availability in competitive pricing environments.
High-tech material specialists and sputtering target suppliers occupy a distinct niche serving vacuum deposition and thin-film applications. These participants compete on technical precision, material specification compliance, and the ability to support demanding semiconductor and optical coating processes. The technical barriers in this segment are substantial, rewarding companies with strong process control, quality assurance capabilities, and application know-how.
Emerging and regional producers, particularly those developing capabilities in high-purity or specialty grades, are expanding their market presence by targeting specific application niches or leveraging regional cost advantages. Their growth trajectory depends on successful navigation of quality consistency requirements, customer qualification processes, and the technical credibility needed to displace established suppliers in demanding applications.
Market Structure Evolution and Strategic Implications
The competitive landscape is evolving along several axes. One trend involves increasing differentiation between commodity-oriented standard-grade producers and specialty-oriented high-purity suppliers. As optical and electronic applications grow in importance, the value attached to superior purity, consistency, and technical support increases, potentially expanding the premium available to differentiated suppliers while compressing margins for undifferentiated commodity players.
A second evolutionary dynamic involves regional supply chain reconfiguration. Policy developments and customer preferences for supply assurance are encouraging some degree of regional production diversification and near-shoring consideration. This may benefit regional producers with competitive cost positions and create opportunities for partnerships that bring material closer to end markets.
Consolidation remains a relevant dynamic, though the moderate market concentration level suggests that industry structure has not yet reached levels typical of highly mature commodity chemical sectors. Strategic acquisitions or partnerships may emerge as established players seek to expand technical capabilities, enter new application segments, or strengthen regional presence. Conversely, new entry remains possible in segments where technical barriers are manageable and cost or regional advantages can be exploited.
Recent industry activity illustrates the ongoing commercial dynamism. For instance, participation in major industry exhibitions such as ChinaCoat 2025 by producers showcasing zinc sulfide additives and new material grades alongside complementary products like PVC stabilizers reflects the trend toward integrated material solutions and proactive commercial engagement with downstream application markets. Such activity demonstrates how suppliers are working to expand their value proposition beyond standalone material supply toward broader formulation and application support.
Future Trends and Commercial Opportunities
Continued Premiumization Around High-Performance Applications
Over the next three to five years, the most significant demand growth is likely to originate from optical and advanced electronic applications where performance specifications continue to escalate. Suppliers that invest in purity capability, application testing infrastructure, and technical support services are positioned to capture disproportionate value from these high-margin segments. The commercial opportunity extends beyond material supply to include partnerships with customers on formulation development, process optimization, and new application exploration. Companies that build credible technical credibility and customer intimacy in demanding end markets strengthen their competitive positioning and develop switching costs that support long-term customer relationships.
Regional Supply Chain Adaptation and Strategic Sourcing
Supply chain adaptation to policy and cost dynamics is expected to accelerate. Customers and producers alike are increasingly valuing supply assurance and regional proximity alongside traditional considerations of price and quality. This creates opportunities for regional producers to strengthen their competitive position and for established global suppliers to enhance their service models through local inventory, technical support presence, or strategic partnerships. The commercial opportunity lies in developing supply chain solutions that demonstrably reduce customer risk while maintaining cost competitiveness. Players that proactively address supply chain concerns through tangible capability investments or contractual arrangements will differentiate from competitors who focus solely on price.
Process Innovation and Cost Competitiveness
Process innovation that improves yield, reduces variability, or lowers energy and feedstock consumption intensity represents a persistent opportunity across the value chain. As raw material and energy costs remain relevant considerations, producers with superior process economics can sustain margins even when pricing pressure emerges. Innovation in surface treatment, particle engineering, and grade customization also opens pathways to serve application segments with unique performance requirements. The key commercial insight is that process capability investment serves dual purposes: it enhances cost competitiveness in commodity segments while enabling the technical capabilities required for premium application segments. Companies that align process investments with clear application strategy are more likely to generate returns than those pursuing undifferentiated capacity expansion.
Risk Considerations
Several risks warrant attention in strategic planning. Raw material price volatility linked to zinc and sulfur commodity markets can compress margins, particularly for producers with limited ability to pass through cost increases or with weaker feedstock positions. Policy and trade policy uncertainty in key sourcing and consumption regions could disrupt established supply patterns, requiring agile response capabilities. Competition from new entrants leveraging regional cost advantages or breakthrough process approaches could pressure incumbents in segments where differentiation is modest. Additionally, cyclical or structural demand shifts in key end-use industries could alter growth trajectories, making portfolio diversification and demand monitoring important risk management practices.
Strategic Recommendations for Decision Makers
For Manufacturers and Producers
Maintain clear strategic clarity on the segments you serve and the basis on which you compete. Attempting undifferentiated competition across all segments without clear cost or technical advantage risks margin erosion. Instead, make deliberate choices about where to differentiate through purity, technical service, regional presence, or cost leadership, and align operational investments accordingly.
Invest proactively in supply chain resilience and supplier diversification, particularly for raw material inputs where policy or price volatility creates uncertainty. Developing alternative sourcing options, considering regional production alternatives, or securing long-term feedstock arrangements can protect margins and ensure supply continuity in volatile conditions.
Strengthen technical engagement with key customers in high-value segments. Material specifications alone are increasingly insufficient for winning and retaining business in optical and advanced electronic applications. Demonstrated application expertise, collaborative problem-solving, and consistent quality performance build the customer relationships and switching costs that support long-term competitive advantage.
For Investors
Assess companies on the basis of their segment positioning, technical capability, and supply chain strategy rather than on aggregate market presence alone. The divergent economics between premium high-purity segments and commodity-grade segments mean that similar top-line growth can mask very different margin and returns profiles. Understanding where a company competes and how differentiated its positioning is informs expectations about sustainability of performance.
Evaluate exposure to regulatory and trade policy dynamics, particularly for companies with significant dependence on cross-border material flows or concentrated sourcing from regions with active policy development. Scenario analysis around supply chain disruptions or policy shifts can reveal vulnerabilities or opportunities that are not apparent from baseline market projections.
Consider the strategic value of regional production capabilities and technical service infrastructure as competitive moats. Companies that have built credible regional presence and application support capabilities may be better positioned to defend margins and customer relationships than those competing primarily on scale or price. These attributes are not always visible in standard financial metrics but are increasingly relevant to long-term enterprise value.
For Procurement and Supply Chain Leaders
Develop supply chain strategies that balance cost optimization with resilience and technical assurance. Total cost of ownership considerations that include availability risk, quality consistency, technical support responsiveness, and logistics reliability provide a more complete basis for supplier selection than unit price comparison alone, particularly for high-value applications where material performance is critical.
Engage suppliers on technical and application development opportunities, not just transactional purchasing. Collaborative relationships with capable suppliers can yield benefits in formulation optimization, problem-solving, and access to new material grades that create value beyond initial purchase price. Treating key material suppliers as strategic partners rather than interchangeable vendors often generates superior long-term outcomes.
Monitor policy and trade developments proactively and incorporate scenario planning into supply chain design. Awareness of regulatory changes affecting zinc and related material flows, combined with flexible sourcing arrangements and qualified alternative suppliers, enables more confident decision-making and faster response to disruptions.
Conclusion
The Zinc Sulfide market is navigating a period of structural transition characterized by growing demand from high-performance optical and electronic applications, ongoing adjustment in supply chain configurations driven by cost and policy dynamics, and increasing differentiation between specialized high-value suppliers and commodity-oriented producers. While aggregate growth rates are moderate, the distribution of value creation is shifting toward participants who execute clearly on segment positioning, technical capability, and supply chain resilience.
For decision makers across manufacturing, investment, and procurement roles, the opportunity lies in moving beyond generic market participation toward deliberate strategic choices that align capabilities with the segments and customer relationships where differentiation is achievable and value is created. Supply chain adaptability, technical engagement, and clear competitive focus are the foundations of sustained performance in a market where commodity dynamics coexist with premium application opportunities.
For those seeking deeper segmentation data, detailed company profiling, regional market breakdowns, and customized strategic recommendations tailored to specific business contexts and investment criteria, access to the full market research report provides comprehensive data tables, granular forecasts, and analytical frameworks designed to support concrete decision-making. Detailed intelligence on market size by segment, competitive positioning maps, and application-level demand trends equips executives and investors with the precision required to translate broad strategic insight into actionable plans.
Zinc Sulfate Market
For detailed analysis of this topic, please visit the official page: Zinc Sulfide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


